



 Chat with AI
Exam 11: Pure Competition in the Long Run

Exam 1: Limits, Alternatives, and Choices107 Questions
Exam 2: The Market System and the Circular Flow287 Questions
Exam 3: Demand, Supply, and Market Equilibrium151 Questions
Exam 4: Market Failures Caused by Externalities Asymmetric Information229 Questions
Exam 5: Public Goods, Public Choice, and Government Failure268 Questions
Exam 6: Elasticity399 Questions
Exam 7: Utility Maximization358 Questions
Exam 8: Behavioral Economics311 Questions
Exam 9: Businesses and the Costs of Production445 Questions
Exam 10: Pure Competition in the Short Run342 Questions
Exam 11: Pure Competition in the Long Run250 Questions
Exam 12: Pure Monopoly407 Questions
Exam 13: Monopolistic Competition279 Questions
Exam 14: Oligopoly and Strategic Behavior362 Questions
Exam 15: Technology, RD, and Efficiency309 Questions
Exam 16: The Demand for Resources359 Questions
Exam 17: Wage Determination168 Questions
Exam 18: Rent, Interest, and Profit305 Questions
Exam 19: Natural Resource and Energy Economics337 Questions
Exam 20: Public Finance: Expenditures and Taxes336 Questions
Exam 21: Antitrust Policy and Regulation264 Questions
Exam 22: Agriculture: Economics and Policy265 Questions
Exam 23: Income Inequality, Poverty, and Discrimination324 Questions
Exam 24: Health Care280 Questions
Exam 25: Immigration259 Questions
Exam 26: International Trade347 Questions
Exam 27: The Balance of Payments, Exchange Rates, and Trade Deficits318 Questions
Exam 28: The Economics of Developing Countries277 Questions
Select questions type


Allocative efficiency is achieved by equalizing consumer surplus and producer surplus.
(True/False)
5.0/5  (73)
(73) If the entry or exit of firms does not affect the resource prices in an industry, we refer to it as a
(Multiple Choice)
4.8/5 (92)
(92) Assume a purely competitive decreasing-cost industry is initially in long-run equilibrium but then there is a decrease in market demand for the product. After all economic adjustments to this new situation have taken place, product price will be
(Multiple Choice)
4.7/5 (90)
(90) If a purely competitive firm is producing where price exceeds marginal cost, then
(Multiple Choice)
5.0/5 (92)
(92) In long-run equilibrium, a competitive firm produces where P = MR = MC = minimum ATC and the firm earns normal economic profits.
(True/False)
4.8/5 (74)
(74) 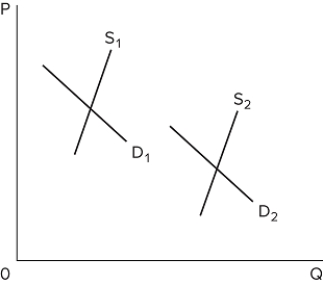 The industry represented by the accompanying graph must be one where
 (Multiple Choice)
4.9/5 (84)
(84) Augi's Art Shack sells art supplies in a perfectly competitive market. The firm is currently realizing economic profits of $25,000 in the short run. In the long run we would expect Augi's to
(Multiple Choice)
4.9/5 (70)
(70) Which of the following will not hold true for a competitive firm in long-run equilibrium?
(Multiple Choice)
4.9/5 (67)
(67) If the long-run supply curve of a purely competitive industry slopes upward, this implies that the prices of relevant resources
(Multiple Choice)
4.9/5 (77)
(77) Suppose a purely competitive, increasing-cost industry is in long-run equilibrium. Now assume that a decrease in consumer demand occurs. After all resulting adjustments have been completed, the new equilibrium price
(Multiple Choice)
4.9/5 (79)
(79) 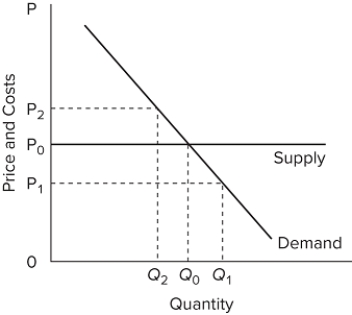 The accompanying graph shows the long-run supply and demand curves in a purely competitive market. We know that when this market reaches equilibrium, the marginal
 (Multiple Choice)
4.9/5 (72)
(72) Resources are efficiently allocated when production occurs at that output at which
(Multiple Choice)
4.7/5 (83)
(83) The theory of creative destruction was advanced many years ago by
(Multiple Choice)
4.9/5 (87)
(87) Efficiency or deadweight losses occur in purely competitive markets when P = MC = lowest ATC.
(True/False)
4.9/5 (79)
(79) 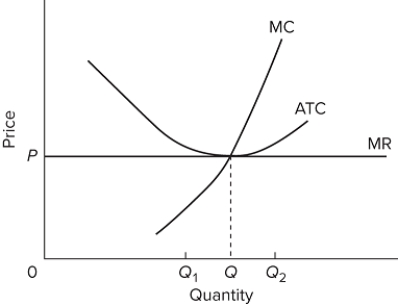 Refer to the diagram. By producing at output level Q,
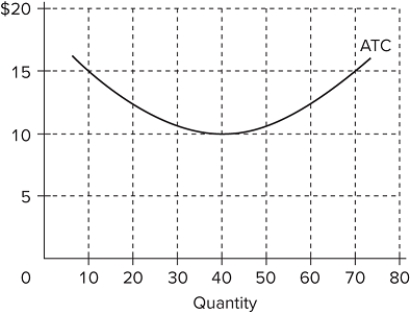 The diagram shows the average total cost curve for a purely competitive firm. At the long-run equilibrium level of output, this firm's total revenue
 (Multiple Choice)
4.8/5 (90)
(90) In the long run for a purely competitive market, firms will earn only normal profits.
(True/False)
4.8/5 (71)
(71) If there is a decrease in demand for a product in a purely competitive industry, it results in an industry contraction that will end when the product price is
(Multiple Choice)
5.0/5 (71)
(71) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)