



 Chat with AI
Exam 11: Pure Competition in the Long Run

Exam 1: Limits, Alternatives, and Choices107 Questions
Exam 2: The Market System and the Circular Flow287 Questions
Exam 3: Demand, Supply, and Market Equilibrium151 Questions
Exam 4: Market Failures Caused by Externalities Asymmetric Information229 Questions
Exam 5: Public Goods, Public Choice, and Government Failure268 Questions
Exam 6: Elasticity399 Questions
Exam 7: Utility Maximization358 Questions
Exam 8: Behavioral Economics311 Questions
Exam 9: Businesses and the Costs of Production445 Questions
Exam 10: Pure Competition in the Short Run342 Questions
Exam 11: Pure Competition in the Long Run250 Questions
Exam 12: Pure Monopoly407 Questions
Exam 13: Monopolistic Competition279 Questions
Exam 14: Oligopoly and Strategic Behavior362 Questions
Exam 15: Technology, RD, and Efficiency309 Questions
Exam 16: The Demand for Resources359 Questions
Exam 17: Wage Determination168 Questions
Exam 18: Rent, Interest, and Profit305 Questions
Exam 19: Natural Resource and Energy Economics337 Questions
Exam 20: Public Finance: Expenditures and Taxes336 Questions
Exam 21: Antitrust Policy and Regulation264 Questions
Exam 22: Agriculture: Economics and Policy265 Questions
Exam 23: Income Inequality, Poverty, and Discrimination324 Questions
Exam 24: Health Care280 Questions
Exam 25: Immigration259 Questions
Exam 26: International Trade347 Questions
Exam 27: The Balance of Payments, Exchange Rates, and Trade Deficits318 Questions
Exam 28: The Economics of Developing Countries277 Questions
Select questions type


If the long-run supply curve is upward sloping, it indicates that resource prices fall when
(Multiple Choice)
4.8/5  (68)
(68) Assume that the market for corn is purely competitive. Currently, firms growing corn are suffering economic losses. In the long run, we can expect
(Multiple Choice)
4.8/5 (93)
(93) 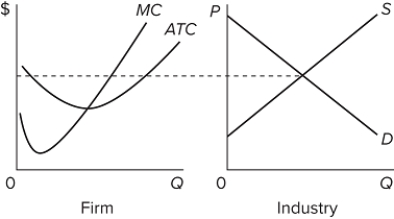 The accompanying graphs are for a purely competitive market in the short run. The graphs suggest that as long run adjustments consequently occur, the firms in the industry will find that
 (Multiple Choice)
4.8/5 (94)
(94) Assume the market for ball bearings is purely competitive. Currently, each of the firms in this market is earning positive economic profits. In the long run, as adjustments occur in the industry, we can expect the market price of ball bearings to
(Multiple Choice)
4.8/5 (73)
(73) We would expect an industry to expand if firms in that industry are
(Multiple Choice)
4.9/5 (85)
(85) Suppose losses cause industry X to contract and, as a result, the prices of relevant inputs decline. Industry X is
(Multiple Choice)
4.8/5 (63)
(63) Approximately what percentage of start-up firms in the United States go bankrupt within the first two years?
(Multiple Choice)
4.7/5 (73)
(73) Which firms will be the most likely to leave the industry when it is incurring losses?
(Essay)
4.7/5 (70)
(70) 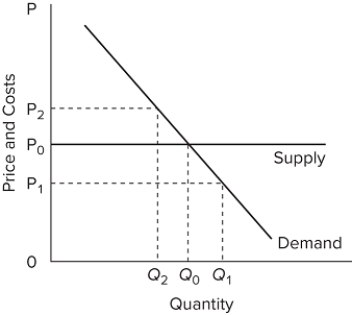 The accompanying graph shows the long-run supply and demand curves in a purely competitive market. We know that in this market, the marginal
 (Multiple Choice)
4.8/5 (76)
(76) "The long-run industry supply curve in a constant-cost industry graphs as a horizontal line. " Explain.
(Essay)
4.9/5 (70)
(70) 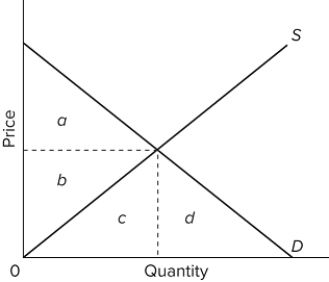 The accompanying graph represents the purely competitive market for a product. When the market is at equilibrium, the consumer surplus would be represented by the area
 (Multiple Choice)
4.8/5 (84)
(84) When a profit-maximizing competitive firm decides to produce at a loss because its price is below average cost but above average variable cost, that is a long-run decision.
(True/False)
4.8/5 (70)
(70) Suppose that Betty's Beads is a typical firm operating in a perfectly competitive market. Currently Betty's MR = $25, MC = $23, ATC = $20, and AVC = $16. Based on this information, we can conclude that
(Multiple Choice)
4.9/5 (71)
(71) 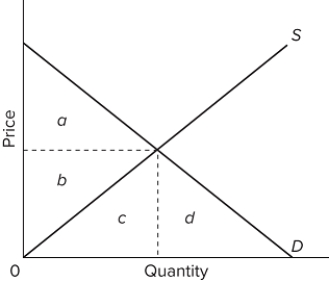 The accompanying graph represents the purely competitive market for a product. When the market is at equilibrium, the producer surplus would be represented by the area
 (Multiple Choice)
4.8/5 (74)
(74) The costs of competition's creative destruction are often widespread, while the benefits often accrue to only a few.
(True/False)
4.8/5 (74)
(74) When entrepreneurs in competitive industries successfully innovate to lower production costs, it usually results in long-run economic profits for the firm.
(True/False)
4.7/5 (82)
(82) Which of the following conditions is true for a purely competitive firm in long-run equilibrium?
(Multiple Choice)
5.0/5 (63)
(63) Which of the following distinguishes the short run from the long run in pure competition?
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)