



 Chat with AI
Exam 11: Pure Competition in the Long Run

Exam 1: Limits, Alternatives, and Choices107 Questions
Exam 2: The Market System and the Circular Flow287 Questions
Exam 3: Demand, Supply, and Market Equilibrium151 Questions
Exam 4: Market Failures Caused by Externalities Asymmetric Information229 Questions
Exam 5: Public Goods, Public Choice, and Government Failure268 Questions
Exam 6: Elasticity399 Questions
Exam 7: Utility Maximization358 Questions
Exam 8: Behavioral Economics311 Questions
Exam 9: Businesses and the Costs of Production445 Questions
Exam 10: Pure Competition in the Short Run342 Questions
Exam 11: Pure Competition in the Long Run250 Questions
Exam 12: Pure Monopoly407 Questions
Exam 13: Monopolistic Competition279 Questions
Exam 14: Oligopoly and Strategic Behavior362 Questions
Exam 15: Technology, RD, and Efficiency309 Questions
Exam 16: The Demand for Resources359 Questions
Exam 17: Wage Determination168 Questions
Exam 18: Rent, Interest, and Profit305 Questions
Exam 19: Natural Resource and Energy Economics337 Questions
Exam 20: Public Finance: Expenditures and Taxes336 Questions
Exam 21: Antitrust Policy and Regulation264 Questions
Exam 22: Agriculture: Economics and Policy265 Questions
Exam 23: Income Inequality, Poverty, and Discrimination324 Questions
Exam 24: Health Care280 Questions
Exam 25: Immigration259 Questions
Exam 26: International Trade347 Questions
Exam 27: The Balance of Payments, Exchange Rates, and Trade Deficits318 Questions
Exam 28: The Economics of Developing Countries277 Questions
Select questions type


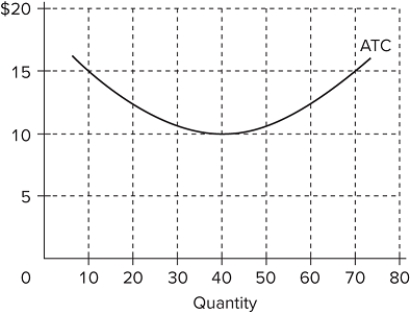 The diagram shows the average total cost curve for a purely competitive firm. At the long-run equilibrium level of output, this firm's total cost
 (Multiple Choice)
4.8/5  (94)
(94) The difference between the maximum price a consumer is willing to pay for a product and the actual price the consumer pays is
(Multiple Choice)
4.9/5 (82)
(82) 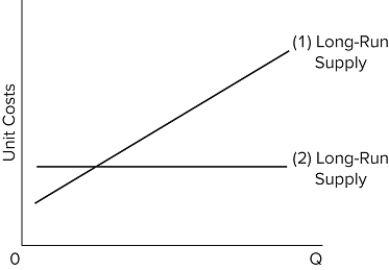 Line (1)in the diagram reflects the long-run supply curve for
 (Multiple Choice)
4.8/5 (99)
(99) An underallocation of resources is occurring in a purely competitive industry whenever the price of the product is greater than marginal cost.
(True/False)
4.9/5 (76)
(76) Which of the following outcomes is consistent with a purely competitive market in long-run equilibrium?
(Multiple Choice)
4.9/5 (85)
(85) Assume a purely competitive constant-cost industry is initially in long-run equilibrium, producing 9 million units at a market price of $18.00. Suppose that an increase in consumer demand occurs. After all economic adjustments have been completed, which output and price combination is most likely to occur?
(Multiple Choice)
5.0/5 (90)
(90)  If the firm shown in this graph is producing at the profit-maximizing level of output in the short run, then it is achieving productive and allocative efficiency.
 (True/False)
4.8/5 (78)
(78) 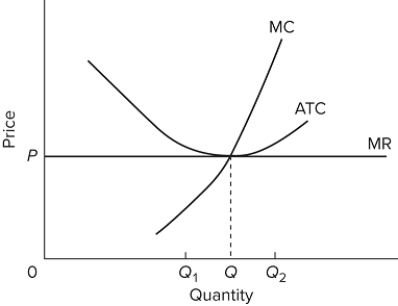 The diagram portrays
It is possible for a competitive firm that is maximizing profits in the short run to make its profits even bigger in the long run by expanding its plant, assuming that the product price stays the same.
(True/False)
4.9/5 (86)
(86) Which of the following is not a factor that automatically pushes firms in pure competition to earn only normal profits in the long run?
(Multiple Choice)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)