



 Chat with AI
Exam 6: Risks and Rates of Return

Exam 1: An Overview of Financial Management and the Financial Environment38 Questions
Exam 2: Financial Statements, Cash Flow, and Taxes3 Questions
Exam 3: Analysis of Financial Statements104 Questions
Exam 4: Time Value of Money139 Questions
Exam 5: Bonds, Bond Valuation, and Interest Rates100 Questions
Exam 6: Risks and Rates of Return132 Questions
Exam 7: Stocks and Their Valuation48 Questions
Exam 8: Financial Options and Applications in Corporate Finance22 Questions
Exam 9: The Cost of Capital87 Questions
Exam 10: The Basics of Capital Budgeting98 Questions
Exam 11: Cash Flow Estimation and Risk Analysis66 Questions
Exam 12: Financial Planning and Forecasting Financial Statements46 Questions
Exam 13: Corporate Valuation, Value-Based Management, and Corporate Governance24 Questions
Exam 14: Distributions to Shareholders: Dividends and Repurchases26 Questions
Exam 15: Capital Structure Decisions70 Questions
Exam 16: Working Capital Management129 Questions
Exam 17: Multinational Financial Management39 Questions
Exam 18: Lease Financing20 Questions
Exam 19: Hybrid Financing: Preferred Stock, Warrants, and Convertibles27 Questions
Exam 20: Initial Public Offerings, Investment Banking, and Financial Restructuring22 Questions
Exam 21: Mergers, Lbos, Divestitures, and Holding Companies41 Questions
Exam 22: Bankruptcy, Reorganization, and Liquidation8 Questions
Exam 23: Derivatives and Risk Management14 Questions
Exam 24: Portfolio Theory, Asset Pricing Models, and Behavioral Finance25 Questions
Exam 25: Real Options15 Questions
Exam 26: Analysis of Capital Structure Theory27 Questions
Exam 27: Providing and Obtaining Credit31 Questions
Exam 28: Advanced Issues in Cash Management and Inventory Control20 Questions
Exam 29: Pension Plan Management9 Questions
Exam 30: Financial Management in Not-For-Profit Businesses10 Questions
Select questions type


A highly risk-averse investor is considering adding one additional stock to a 3-stock portfolio, to form a 4-stock portfolio. The three stocks currently held all have b = 1.0, and they are perfectly positively correlated with the market. Potential new Stocks A and B both have expected returns of 15%, are in equilibrium, and are equally correlated with the market, with r = 0.75. However, Stock A's standard deviation of returns is 12% versus 8% for Stock B. Which stock should this investor add to his or her portfolio, or does the choice not matter?
(Multiple Choice)
4.9/5  (83)
(83) The realized return on a stock portfolio is the weighted average of the expected returns on the stocks in the portfolio.
(True/False)
4.7/5 (83)
(83) Stock A has a beta of 0.8, Stock B has a beta of 1.0, and Stock C has a beta of 1.2. Portfolio P has 1/3 of its value invested in each stock. Each stock has a standard deviation of 25%, and their returns are independent of one another, i.e., the correlation coefficients between each pair of stocks is zero. Assuming the market is in equilibrium, which of the following statements is CORRECT?
(Multiple Choice)
4.9/5 (71)
(71) When adding a randomly chosen new stock to an existing portfolio, the higher (or more positive) the degree of correlation between the new stock and stocks already in the portfolio, the less the additional stock will reduce the portfolio's risk.
(True/False)
4.8/5 (67)
(67) Linke Motors has a beta of 1.30, the T-bill rate is 3.00%, and the T- bond rate is 6.5%. The annual return on the stock market during the past 3 years was 15.00%, but investors expect the annual future stock market return to be 13.00%. Based on the SML, what is the firm's required return?
(Multiple Choice)
4.9/5 (74)
(74) The CAPM is a multi-period model that takes account of differences in securities' maturities, and it can be used to determine the required rate of return for any given level of systematic risk.
(True/False)
5.0/5 (86)
(86) The SML relates required returns to firms' systematic (or market) risk. The slope and intercept of this line can be influenced by a manager's actions.
(True/False)
4.8/5 (77)
(77) An individual stock's diversifiable risk, which is measured by its beta, can be lowered by adding more stocks to the portfolio in which the stock is held.
(True/False)
4.9/5 (77)
(77) A firm can change its beta through managerial decisions, including capital budgeting and capital structure decisions.
(True/False)
4.9/5 (88)
(88) Which of the following is NOT a potential problem when estimating and using betas, i.e., which statement is FALSE?
(Multiple Choice)
4.9/5 (79)
(79) Assume that your uncle holds just one stock, East Coast Bank (ECB), which he thinks has very little risk. You agree that the stock is relatively safe, but you want to demonstrate that his risk would be even lower if he were more diversified. You obtain the following returns data for West Coast Bank (WCB). Both banks have had less variability than most other stocks over the past 5 years. Measured by the standard deviation of returns, by how much would your uncle's risk have been reduced if he had held a portfolio consisting of 60% in ECB and the remainder in WCB? (Hint: Use the sample standard deviation formula.) 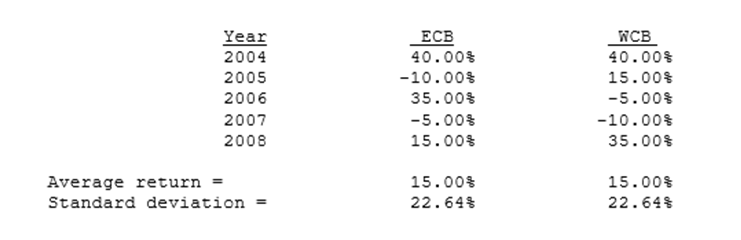
(Multiple Choice)
4.7/5 (83)
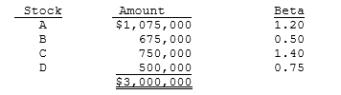
(83) Assume that you are the portfolio manager of the SF Fund, a $3 million hedge fund that contains the following stocks. The required rate of return on the market is 11.00% and the risk-free rate is 5.00%. What rate of return should investors expect (and require) on this fund?
(Multiple Choice)
4.8/5 (89)
(89) Assume that to cool off the economy and decrease expectations for inflation, the Federal Reserve tightened the money supply, causing an increase in the risk-free rate, rRF. Investors also became concerned that the Fed's actions would lead to a recession, and that led to an increase in the market risk premium, (rM - rRF). Under these conditions, with other things held constant, which of the following statements is most correct?
(Multiple Choice)
4.8/5 (92)
(92) The risk-free rate is 6%; Stock A has a beta of 1.0; Stock B has a beta of 2.0; and the market risk premium, rM − rRF, is positive. Which of the following statements is CORRECT?
(Multiple Choice)
4.8/5 (80)
(80) Which of the following is most likely to occur as you add randomly selected stocks to your portfolio, which currently consists of 3 average stocks?
(Multiple Choice)
4.9/5 (82)
(82) If the price of money (e.g., interest rates and equity capital costs) increases due to an increase in anticipated inflation, the risk-free rate will also increase. If there is no change in investors' risk aversion, then the market risk premium (rM − rRF) will remain constant. Also, if there is no change in stocks' betas, then the required rate of return on each stock as measured by the CAPM will increase by the same amount as the increase in expected inflation.
(True/False)
4.8/5 (75)
(75) Jim Angel holds a $200,000 portfolio consisting of the following stocks:
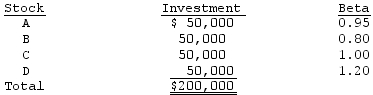 What is the portfolio's beta?
 (Multiple Choice)
4.8/5 (86)
(86) Portfolio A has but one stock, while Portfolio B consists of all stocks that trade in the market, each held in proportion to its market value. Because of its diversification, Portfolio B will by definition be riskless.
(True/False)
4.8/5 (78)
(78) Calculate the required rate of return for Climax Inc., assuming that
(1) investors expect a 4.0% rate of inflation in the future, (2) the real risk-free rate is 3.0%, (3) the market risk premium is 5.0%, (4) the firm has a beta of 1.00, and (5) its realized rate of return has averaged 15.0% over the last 5 years.
(Multiple Choice)
4.8/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)