



 Chat with AI
Exam 14: Decision Making: Relevant Costs and Benefits

Exam 1: The Changing Role of Managerial Accounting in a Dynamic Business Environment85 Questions
Exam 2: Basic Cost Management Concepts115 Questions
Exam 3: Product Costing and Cost Accumulation in a Batch Production Environment95 Questions
Exam 4: Process Costing and Hybrid Product-Costing Systems88 Questions
Exam 5: Activity-Based Costing and Management103 Questions
Exam 6: Activity Analysis, Cost Behavior, and Cost Estimation90 Questions
Exam 7: Cost-Volume-Profit Analysis109 Questions
Exam 8: Variable Costing and the Costs of Quality and Sustainability74 Questions
Exam 9: Financial Planning and Analysis: the Master Budget112 Questions
Exam 10: Standard Costing and Analysis of Direct Costs97 Questions
Exam 11: Flexible Budgeting and Analysis of Overhead Costs89 Questions
Exam 12: Responsibility Accounting, Operational Performance Measures, and the Balanced Scorecard89 Questions
Exam 13: Investment Centers and Transfer Pricing101 Questions
Exam 14: Decision Making: Relevant Costs and Benefits96 Questions
Exam 15: Target Costing and Cost Analysis for Pricing Decisions107 Questions
Exam 16: Capital Expenditure Decisions120 Questions
Exam 17: Allocation of Support Activity Costs and Joint Costs81 Questions
Exam 18: The Sarbanes-Oxley Act, Internal Controls, and Management Accounting20 Questions
Exam 19: Compound Interest and the Concept of Present Value27 Questions
Exam 20: Inventory Management20 Questions
Select questions type


In early July, Colin Marks purchased a $70 ticket to the December 15 game of the Sarasota Shippers. Parking for the game was expected to cost approximately $22, and Marks would probably spend another $15 for a souvenir program and food. It is now December 14. The Shippers were having a miserable season and the temperature was expected to peak at 5 degrees on game day. Marks therefore decided to skip the game and took his wife to the movies, with tickets and dinner costing $50. The sunk cost associated with this decision situation is:
(Multiple Choice)
4.8/5  (75)
(75) Which of the following characteristics would best explain the use of probabilities and expected values in a decision analysis?
(Multiple Choice)
4.9/5 (77)
(77) Use the following information to answer the following Questions
Jayleen Company makes two products: Carpet Kleen and Floor Deodorizer. Operating information from the previous year follows.
 Fixed costs of $20,000 per year are presently allocated equally between both products. If the product mix were to change, total fixed costs would remain the same.
-The contribution margin per machine hour for Floor Deodorizer is:
Fixed costs of $20,000 per year are presently allocated equally between both products. If the product mix were to change, total fixed costs would remain the same.
-The contribution margin per machine hour for Floor Deodorizer is: (Multiple Choice)
4.9/5 (72)
(72) An accounting information system should be designed to provide information that is useful. To be useful the information must be:
(Multiple Choice)
4.9/5 (88)
(88) Use the following information to answer the following Questions
Cheyenne Enterprises manufactures Nuts and Bolts from a joint process (cost = $80,000). Five thousand pounds of Nuts can be sold at split-off for $20 per pound; ten thousand pounds of Bolts can be sold at split-off for $15 per pound. For product costing purposes Cheyenne allocates joint costs using the relative sales value method.
-The amount of joint cost allocated to Nuts would be:
(Multiple Choice)
4.8/5 (86)
(86) Use the following information to answer the following Questions
Cheyenne Enterprises manufactures Nuts and Bolts from a joint process (cost = $80,000). Five thousand pounds of Nuts can be sold at split-off for $20 per pound; ten thousand pounds of Bolts can be sold at split-off for $15 per pound. For product costing purposes Cheyenne allocates joint costs using the relative sales value method.
-The amount of joint cost allocated to Bolts would be:
(Multiple Choice)
4.8/5 (73)
(73) Maine Company recently discontinued the manufacture of product J15. The standard costs for this product were:
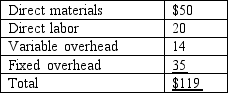 There are 800 units of this product in finished-goods inventory. The units are technologically obsolete, and the following alternatives are being considered:
1. Dispose of as scrap. The proceeds from the sale will equal the cost of transportation to the disposal site.
2. Sell to an exporter for sale in a developing country. The sales price to the exporter would be $12 per unit.
3. Remanufacture the products to convert them into model J16, a model that normally sells for $200. The additional cost to convert the J15 units would be $45; the standard cost to manufacture J16 is $125. Presently, there is sufficient capacity to manufacture product J16 directly or to do the necessary conversion work on J15.
Required:
A. Determine the current carrying value of the J15 inventory.
B. Evaluate each alternative and determine the financial benefit to Maine if the alternative is pursued.
There are 800 units of this product in finished-goods inventory. The units are technologically obsolete, and the following alternatives are being considered:
1. Dispose of as scrap. The proceeds from the sale will equal the cost of transportation to the disposal site.
2. Sell to an exporter for sale in a developing country. The sales price to the exporter would be $12 per unit.
3. Remanufacture the products to convert them into model J16, a model that normally sells for $200. The additional cost to convert the J15 units would be $45; the standard cost to manufacture J16 is $125. Presently, there is sufficient capacity to manufacture product J16 directly or to do the necessary conversion work on J15.
Required:
A. Determine the current carrying value of the J15 inventory.
B. Evaluate each alternative and determine the financial benefit to Maine if the alternative is pursued. (Essay)
4.7/5 (73)
(73) At which step or steps in the decision-making process do qualitative considerations generally have the greatest impact?
(Multiple Choice)
4.8/5 (84)
(84) The axes and constraints form an area for the solution to a linear program called the relevant region.
(True/False)
4.8/5 (76)
(76) In the final analysis of a decision, quantitative measures are more important than qualitative measures.
(True/False)
4.9/5 (91)
(91) A technique that is useful in exploring what would happen if a key decision prediction or assumption proved wrong is termed:
(Multiple Choice)
4.8/5 (71)
(71) Haverton Industries is studying whether to drop a product because of ongoing losses. Costs that would be relevant in this situation would include variable manufacturing costs as well as:
(Multiple Choice)
4.7/5 (81)
(81) Linear programming would be used by decision makers when there are:
(Multiple Choice)
4.7/5 (81)
(81) Deltones, a manufacturer of computer peripherals, has excess capacity. The company's Alabama plant has the following per-unit cost structure for item no. 89:
 The traceable fixed administrative cost was incurred at the Alabama plant; in contrast, the allocated administrative cost represents a "fair share" of Deltones' corporate overhead. Alabama has been presented with a special order of 5,000 units of item no. 89 on which no selling cost will be incurred. The proper relevant cost in deciding whether to accept this special order would be:
 (Multiple Choice)
4.8/5 (76)
(76) St. Luke's Hospital has been hit with a number of complaints about its food service from patients, employees, and cafeteria customers. These complaints, coupled with a very tight local labor market, have prompted the organization to contact Nationwide Institutional Food Service (NIFS) about the possibility of an outsourcing arrangement.
The hospital's business office has provided the following information for food service for the year just ended: food costs, $890,000; labor, $85,000; variable overhead, $35,000; allocated fixed overhead, $60,000; and cafeteria net income, $80,000.
Conversations with NIFS personnel revealed the following information:
· NIFS will charge St. Luke's Hospital $14 per day for each patient served. Note: This figure has been "marked up" by NIFS to reflect the firm's cost of operating the hospital cafeteria.
· St. Luke's 250-bed facility operates throughout the year and typically has an average occupancy rate of 70%.
· Labor is the primary driver for variable overhead. If an outsourcing agreement is reached, hospital labor costs will drop by 90%. NIFS plans to use St. Luke's facilities for meal preparation.
· Cafeteria net income is expected to increase by 15% because NIFS will offer an improved menu selection.
Required:
A. What is meant by the term "outsourcing"?
B. Should St. Luke's outsource its food-service operation to NIFS?
C. What factors, other than dollars, should St. Luke's consider before making the final decision?
(Essay)
4.9/5 (77)
(77) Under activity-based costing, the concepts underlying relevant-costing analysis are not valid because they may derive conclusions that are different than those obtained with conventional cost analyses.
(True/False)
4.8/5 (78)
(78) "It's close to a $40,000 loser and we ought to devote our efforts elsewhere," noted Cindy Mires, after reviewing financial reports of her company's attempt to offer a reduced-price daycare service to employees. The daycare's financial figures for the year just ended follow.
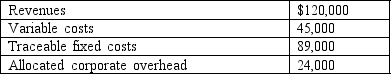 If the daycare service/center is closed, 70% of the traceable fixed cost will be avoided. In addition, the company will incur one-time closure costs of $6,800.
Required:
A. Show calculations that support Mires' belief that the daycare center lost almost $40,000.
B. Should the center be closed? Show calculations to support your answer.
C. What problem might the company experience if the center is closed?
If the daycare service/center is closed, 70% of the traceable fixed cost will be avoided. In addition, the company will incur one-time closure costs of $6,800.
Required:
A. Show calculations that support Mires' belief that the daycare center lost almost $40,000.
B. Should the center be closed? Show calculations to support your answer.
C. What problem might the company experience if the center is closed? (Essay)
4.9/5 (77)
(77) Use the following information to answer the following Questions
Cheyenne Enterprises manufactures Nuts and Bolts from a joint process (cost = $80,000). Five thousand pounds of Nuts can be sold at split-off for $20 per pound; ten thousand pounds of Bolts can be sold at split-off for $15 per pound. For product costing purposes Cheyenne allocates joint costs using the relative sales value method.
-The amount of joint cost allocated to Nuts and Bolts, respectively, would be:
(Multiple Choice)
5.0/5 (84)
(84) Cost predictions relevant to repetitive decisions typically can draw on a large amount of historical data.
(True/False)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)