



 Chat with AI
Exam 15: Non-Current Liabilities

Exam 1: Accounting in Action162 Questions
Exam 2: The Recording Process163 Questions
Exam 3: Adjusting the Accounts179 Questions
Exam 4: Completion of the Accounting Cycle151 Questions
Exam 5: Accounting for Merchandising Operations201 Questions
Exam 6: Inventory Costing176 Questions
Exam 7: Internal Control and Cash130 Questions
Exam 9: Long-Lived Assets243 Questions
Exam 10: Current Liabilities98 Questions
Exam 11: Accounting Principles116 Questions
Exam 12: Accounting for Partnerships153 Questions
Exam 13: Introduction to Corporations195 Questions
Exam 14: Corporations: Additional Topics and Ifrs136 Questions
Exam 15: Non-Current Liabilities139 Questions
Exam 16: The Cash Flow Statement158 Questions
Exam 17: Financial Statement Analysis155 Questions
Exam 18: Investments68 Questions
Select questions type


Stead, Inc. issued $600,000, 6%, 20-year bonds on January 1, 2014, at 102. Interest is payable semi-annually on July 1 and January 1. Stead has a December 31 year end. Assume amortization of $250 and $260 respectively for the first two semi-annual interest periods.
Instructions
Prepare all journal entries made in 2014 related to the bond issue.
(Essay)
4.9/5  (84)
(84) When authorizing bonds to be issued, the board of directors does NOT specify the
(Multiple Choice)
4.8/5 (87)
(87) Even if it is riskier to issue debt, most companies still choose to do this because
(Multiple Choice)
4.7/5 (89)
(89) When recording a retirement of bonds, a company must account for all of the following EXCEPT
(Multiple Choice)
4.9/5 (80)
(80) Hanna Manufacturing Limited receives $240,000 on January 1, 2013 when it issues a 6%, 3-year note payable to finance the purchase of equipment. The terms provide for annual payments each December 31. The first payment is due December 31, 2013.
Instructions
Prepare the journal entries to record the note and the first two instalment payments assuming:
a. the payment is a fixed principal payment of $80,000.
b. the payment is a blended payment of $89,786.76.
(Essay)
4.8/5 (77)
(77) The present value of a bond is the value at which the bond would sell in the marketplace.
(True/False)
4.8/5 (63)
(63) On January 1, 2013, Callahan Corporation issued $600,000, 9%, 5-year bonds, dated January 1, 2013, at 104. The bonds pay interest semi-annually on January 1 and July 1. The company has a December 31 year end. Assume amortization of $1,700 and $2,100 respectively for the first two semi-annual interest periods.
Instructions
Prepare the journal entries that Callahan Corporation would make related to the bond issue on the dates indicated below: 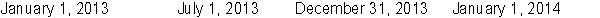
(Essay)
4.9/5 (71)
(71) Earnings per share is usually higher under debt financing because
(Multiple Choice)
4.8/5 (79)
(79) Bonds that are issued against the general credit of the issuer are termed
(Multiple Choice)
4.8/5 (87)
(87) If $100,000 face value bonds with a carrying value of $95,200 are redeemed at 97, a loss on redemption will be recorded.
(True/False)
4.8/5 (87)
(87) Match the items below by entering the appropriate code letter in the space provided.
Correct Answer: Verified
Premises:
Responses:
(Matching)
5.0/5 (82)
(82) If there is a loss on bonds redeemed before maturity, it is
(Multiple Choice)
4.8/5 (76)
(76) The entry to record an instalment payment on a non-current note payable is
(Multiple Choice)
4.8/5 (79)
(79) The effective-interest method of amortization results in varying amounts of amortization, and interest expense per period but a constant rate of interest.
(True/False)
4.8/5 (70)
(70) Bonds are usually sold in small denominations; as a result,
(Multiple Choice)
4.8/5 (82)
(82) Instalment notes with blended payments are repayable in variable periodic amounts that include the principal and the interest.
(True/False)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)