



 Chat with AI
Exam 15: Non-Current Liabilities

Exam 1: Accounting in Action162 Questions
Exam 2: The Recording Process163 Questions
Exam 3: Adjusting the Accounts179 Questions
Exam 4: Completion of the Accounting Cycle151 Questions
Exam 5: Accounting for Merchandising Operations201 Questions
Exam 6: Inventory Costing176 Questions
Exam 7: Internal Control and Cash130 Questions
Exam 9: Long-Lived Assets243 Questions
Exam 10: Current Liabilities98 Questions
Exam 11: Accounting Principles116 Questions
Exam 12: Accounting for Partnerships153 Questions
Exam 13: Introduction to Corporations195 Questions
Exam 14: Corporations: Additional Topics and Ifrs136 Questions
Exam 15: Non-Current Liabilities139 Questions
Exam 16: The Cash Flow Statement158 Questions
Exam 17: Financial Statement Analysis155 Questions
Exam 18: Investments68 Questions
Select questions type


Prairie Corporation issued $100,000 of 10 year, 6% bonds payable on January 1, 2014 for $92,900, at a time when market interest rates were 7%. Interest is payable semi-annually on June 30 and December 31. On January 1, 2015, 20% of the bonds were redeemed at 101. Prairie has a December 31 year end and uses the effective-interest method in accounting for bonds payable.
Instructions
a. Record the issue of the bonds on January 1, 2014.
b. Record the payment of interest on June 30 and December 31, 2014.
c. Show how the bonds would be reported on Prairie's December 31, 2014 balance sheet.
d. Record the redemption of the bonds on January 1, 2015.
(Essay)
4.9/5  (77)
(77) If the market rate of interest is greater than the contractual rate of interest, bonds will sell
(Multiple Choice)
4.8/5 (77)
(77) The present value of bonds always equals the face value of the bonds if the market interest rate equals the contractual interest rate at the time of the issuance of the bonds.
(True/False)
4.8/5 (72)
(72) Bonds that can be retired by the issuer at a stated dollar amount before they mature are known as
(Multiple Choice)
4.9/5 (78)
(78) Presented below are two independent situations:
a. Hillman Corporation redeemed $150,000 of its bonds on June 30, 2014, at 102. The amortized cost of the bonds on the retirement date was $137,700. The bonds pay semi-annual interest and the interest payment due on June 30, 2014, has been made and recorded.
b. Dalton Inc. redeemed $200,000 of its bonds at 96 on June 30, 2014. The amortized cost of the bonds on the retirement date was $196,500. The bonds pay semi-annual interest and the interest payment due on June 30, 2014, has been made and recorded.
Instructions
For each of the independent situations, prepare the journal entries to record the retirement or conversion of the bonds.
(Essay)
4.9/5 (83)
(83) On January 1, 2014, Kramer International Inc. issued $200,000, 9%, 5-year bonds for $192,278. The bonds were sold to yield an effective interest rate of 10%. Interest is paid semi-annually on June 30 and December 31. The company uses the effective-interest method of amortization.
Instructions
a. Prepare a bond discount amortization schedule which shows the amortization of discount for the first two interest payment dates. (Round to the nearest dollar.)
b. Prepare the journal entries that Kramer International would make on January 1, June 30, and December 31, 2014, related to the bond issue.
(Essay)
4.9/5 (70)
(70) The present value of a $10,000, 5-year bond, will be less than $10,000 if the
(Multiple Choice)
4.9/5 (80)
(80) On January 1, 2013, $1,000,000, 5-year, 5% bonds, were issued for $957,349. The interest rate in effect when the bonds were issued was 6%. Interest is paid semi-annually on January 1 and July 1. What would be the amortized cost of the bonds on January 1, 2014?
(Multiple Choice)
4.8/5 (77)
(77) On June 30, 2013, Layton, Inc. sold $1,200,000 (face value) of bonds. The bonds are dated June 30, 2013, pay interest semi-annually on December 31 and June 30, and will mature on June 30, 2016. The following schedule was prepared by the accountant for 2013: 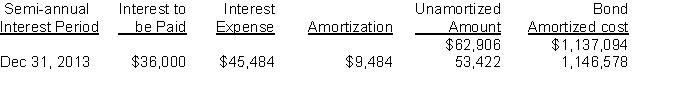 Instructions
On the basis of the above information, answer the following questions. (Round your answer to the nearest dollar or percent.)
a. What is the contractual rate of interest for this bond issue?
b. What is the market rate of interest for this bond issue?
c. What was the selling price of the bonds as a percentage of the face value?
d. Prepare the journal entry to record the sale of the bond issue on June 30, 2013.
e. Prepare the journal entry to record the payment of interest and amortization on December 31, 2013.
Instructions
On the basis of the above information, answer the following questions. (Round your answer to the nearest dollar or percent.)
a. What is the contractual rate of interest for this bond issue?
b. What is the market rate of interest for this bond issue?
c. What was the selling price of the bonds as a percentage of the face value?
d. Prepare the journal entry to record the sale of the bond issue on June 30, 2013.
e. Prepare the journal entry to record the payment of interest and amortization on December 31, 2013. (Essay)
4.9/5 (71)
(71) Under the effective interest method, the amount of premium or discount amortized is constant every period.
(True/False)
4.8/5 (90)
(90) If a corporation issued $4,000,000 in bonds which pay 5% annual interest, what is the annual net cash cost of this borrowing if the income tax rate is 30%?
(Multiple Choice)
4.9/5 (73)
(73) On February 1, 2014, the Happy Valley Corporation issued $100,000, 5%, 5-year bonds. Interest is payable semi-annually on August 1 and February 1.
Instructions
a. Prepare the journal entries that Happy Valley would make on February 1 if it issued the bonds at (1) 100, (2) 98, and (3) 102.
a.?
b. How much interest would Happy Valley Corporation pay on August 1, 2014 under each of the three issue prices listed in
(Essay)
4.8/5 (66)
(66) On January 1, 2013, $1,000,000, 5-year, 5% bonds, were issued for $957,349. The interest rate in effect when the bonds were issued was 6%. Interest is paid semi-annually on January 1 and July 1. What would be the amount of discount amortized on July 1, 2013?
(Multiple Choice)
4.9/5 (78)
(78) There are three steps required to calculate amortization using the effective interest method. Which one of the following is NOT a required step?
(Multiple Choice)
4.8/5 (94)
(94) Equity financing is riskier than debt financing because interest must be paid regularly and the principal must be paid on maturity.
(True/False)
4.7/5 (84)
(84) Kelsey Holdings Inc. requires $5,000,000 in new financing in order to expand its operations. The management team is in discussion about the best way to finance the expansion and has asked you, their accountant, for assistance. In order to provide them with the information they need, you analyze the following two options:
1. Issue 1,000,000 common shares at $5 which is the current market price of Kelsey's 2,000,000 issued common shares.
2. Issue $5,000,000 of 10-year, 4% bonds at 101. Kelsey currently has no bonds payable issued.
The financing would be required at the beginning of the next fiscal year. Kelsey's tax rate is 30%. The management team projects profit of $1,750,000 before financing costs and taxes. They are interested in comparing the net income after tax, the earnings per share, and the return on equity under each alternative. The management team's goal is to maximize return on equity in the first year. Kelsey's shareholder equity other than share capital includes retained earnings and accumulated other comprehensive income totaling $17,500,000.
Instructions
Calculate the amounts requested by the management team and present the two alternatives in comparative format. Recommend which alternative should be chosen.
(Essay)
4.9/5 (76)
(76) A mortgage note payable with a fixed interest rate requires the borrower to make blended principal and interest payments over the term of the loan. Each instalment payment includes interest on the unpaid balance of the loan and a payment on the principal. With each instalment payment, indicate the effect on the portion allocated to interest expense and the portion allocated to principal. 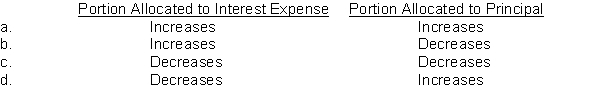
(Short Answer)
4.9/5 (90)
(90) If a corporation issued bonds at an amount less than face value, it indicates that the corporation has a weak credit rating.
(True/False)
4.8/5 (75)
(75) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)