



 Chat with AI
Exam 3: Review of a Company S Accounting System

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


The entire group of accounts for a company is referred to as the
(Multiple Choice)
4.9/5  (98)
(98) The following are selected account balances for Streamline Services: 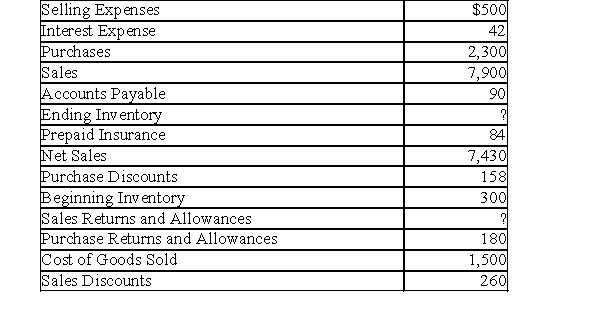 Required:
Prepare a partial income statement through gross profit on sales. Do not prepare the heading.
Required:
Prepare a partial income statement through gross profit on sales. Do not prepare the heading. (Essay)
5.0/5 (81)
(81) The primary purpose of an accounting system is to record, organize. summarize, and report useful information to external financial statement users and stakeholders, as well as to company management, who make operating, investing and financing decisions.
(True/False)
4.9/5 (88)
(88) The Nathan's Company rents numerous properties throughout the year. Nathan's pays rents in advance in some cases, and in other cases rents are paid after the rental period expires. The following data are included in Nathan's December 31 balance sheets:  During 2016, Nathan paid $200,000 in rentals. In its accrual basis income statement for the year ended December 31, 2016, Nathan should report rent expense of:
 (Multiple Choice)
4.8/5 (91)
(91) The accounting cycle followed each period by a company includes recording transactions, storing the data, organizing the information, summarizing the events and arrangements, adjusting the accounts, reporting the accounting information in financial statements, and then closing the books.
(True/False)
4.9/5 (84)
(84) Selected account balances from the December 31, 2015, trial balance of the Gracy Company are listed below: 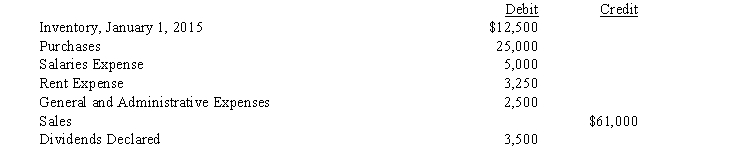 In addition, the following information is available:
· The cost of the ending inventory at December 31, 2015, is $7,500.
· $890 of salaries have accrued as of December 31.
· On March 30, Gracy purchased a 12-month insurance policy for $240. The purchase was debited to Prepaid Insurance.
· On December 1, the company paid 2 months' rent in advance. The $1500 payment was debited to Rent Expense.
· In December, a customer paid $1,000 in advance for merchandise that will be shipped by Gracy in 2016. The amount received was credited to Sales.
· Gracy estimates its bad debts to be 1% of sales after all adjustments).
· The income tax rate is 30%.
Gracy Company uses a periodic inventory system.
Required:
Using a general journal format, prepare the required adjusting entries.
In addition, the following information is available:
· The cost of the ending inventory at December 31, 2015, is $7,500.
· $890 of salaries have accrued as of December 31.
· On March 30, Gracy purchased a 12-month insurance policy for $240. The purchase was debited to Prepaid Insurance.
· On December 1, the company paid 2 months' rent in advance. The $1500 payment was debited to Rent Expense.
· In December, a customer paid $1,000 in advance for merchandise that will be shipped by Gracy in 2016. The amount received was credited to Sales.
· Gracy estimates its bad debts to be 1% of sales after all adjustments).
· The income tax rate is 30%.
Gracy Company uses a periodic inventory system.
Required:
Using a general journal format, prepare the required adjusting entries. (Essay)
4.8/5 (87)
(87) 
The general journal has all journal entry transactions listed by account title.
(True/False)
5.0/5 (75)
(75) Information regarding the Rainey Company follows:
· On November 1, 2014, Rainey accepted a $10,000, three-month note receivable from a major customer. Interest on the note, computed at a 12% annual rate, will be collected with the principal.
· On December 1, 2014, Rainey borrowed $12,000 from its bank. The principal, plus interest computed at a 10% annual rate, is due on June 1, 2015.
· Rainey uses the straight-line method to record depreciation on its equipment. The equipment, which cost $12,000, has an estimated life of 10 years and no expected residual value.
· $3,725 of salaries had accrued as of December 31, 2014.
Required:
a. Assuming that Rainey does use reversing entries, prepare December 31, 2014 adjusting entries and 2015 reversing entries.
b. Assuming that Rainey does not use reversing entries, prepare journal entries to record the collection of the note receivable and the payment of the note payable in 2015.
(Essay)
4.8/5 (77)
(77) When cash is debited for rents that are collected but are not yet earned, the amount credited should be
(Multiple Choice)
4.9/5 (83)
(83) Walker Company uses the accrual basis of accounting. Walker Company's wages expense account had a $610,000 balance at the end of the year. The wages payable account had a $23,000 balance at the beginning of the year and a $45,000 balance at the end of the year. How much cash was paid for wages during the year?
(Multiple Choice)
4.8/5 (79)
(79) What is the difference between a subsidiary ledger and a special journal?
(Essay)
4.8/5 (89)
(89) Graham Corp. engaged in the following transactions during the month of June:
June 1 Made cash sales of $15,000.
5 Made credit sales of $25,000.
9 Customers returned $800 of merchandise from the June 5 sale because it was defective.
14 Received payment for balance due on the June 5 sale.
19 Sold land that had originally cost $15,000 for $55,000 cash.
Required:
Record these transactions in a general journal, assuming Graham uses a periodic inventory system.
(Essay)
4.8/5 (64)
(64) On June 1, 2015, Little Corporation received $5,320 in advance for a two-year rental of some land and properly credited Unearned Rent. In the adjusting entry at December 31, 2015, there would be a
(Multiple Choice)
4.8/5 (72)
(72) Although optional, a reversing entry is usually made for adjusting entries that accrue expenses to be paid in the next accounting period.
(True/False)
5.0/5 (89)
(89) Little Company uses the cash basis of accounting. Little Company made $28,000 in payments to its suppliers during the year. Little's beginning inventory was $2,000, and its ending inventory was $1,000. In addition, Little had a beginning accounts payable of $7,000 and an ending accounts payable balance of $4,000. What is Little's cost of goods sold under the accrual basis of accounting?
(Multiple Choice)
4.9/5 (91)
(91) Marlin Company has all of the special journals that were described in your text other than the voucher register) as a part of its accounting system. Which of the following journal entries would therefore be recorded in Marlin's general journal?
(Multiple Choice)
4.8/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)