



 Chat with AI
Exam 8: Inventories: Special Valuation Issues

Exam 1: The Demand for and Supply of Financial Accounting Information85 Questions
Exam 2: Financial Reporting: Its Conceptual Framework83 Questions
Exam 3: Review of a Company S Accounting System148 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity127 Questions
Exam 5: The Income Statement and the Statement of Cash Flows Time Value of Money Module136 Questions
Exam 6: Cash and Receivables172 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions114 Questions
Exam 8: Inventories: Special Valuation Issues141 Questions
Exam 9: Current Liabilities and Contingent Obligations125 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments111 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal136 Questions
Exam 12: Intangibles136 Questions
Exam 13: Investments and Long-Term Receivables135 Questions
Exam 14: Financing Liabilities: Bonds and Long-Term Notes Payable192 Questions
Exam 15: Contributed Capital153 Questions
Exam 16: Retained Earnings and Earnings Per Share110 Questions
Exam 17: Advanced Issues in Revenue Recognition103 Questions
Exam 18: Accounting for Income Taxes113 Questions
Exam 19: Accounting for Post-Retirement Benefits94 Questions
Exam 20: Accounting for Leases116 Questions
Exam 21: The Statement of Cash Flows103 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Understanding Time Value of Money Formulas and Concepts142 Questions
Select questions type


If purchases are recorded correctly but ending physical inventory is understated, which one of the following situations occurs for the current year?
(Multiple Choice)
4.8/5  (73)
(73) The lower-of-cost-or-market rule must be applied to each individual inventory item but not to groups of items
(True/False)
4.9/5 (81)
(81) Which one of the following statements is not true with regard to the gross profit method of estimating inventories?
(Multiple Choice)
4.8/5 (74)
(74) Which one of the following statements is false concerning the retail inventory method?
(Multiple Choice)
4.9/5 (70)
(70) Debbie's Bling Shop uses the lower of average cost or market retail inventory method to determine its ending inventory. The accounting records for the current year for Debbie's contained the following information: 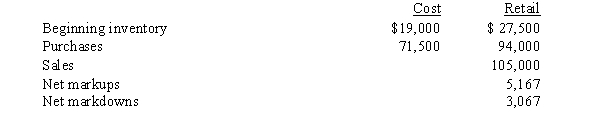 In addition, the accounting records for Debbie's disclosed that freight-in charges were $6,700 and sales returns were $2,833. What is the cost-to-retail percentage to be used for ending inventory calculations?
 (Multiple Choice)
4.9/5 (69)
(69) As a result of taking a physical inventory count on December 31, 2016, the Mona Lisa Company inventory was determined to be $61,500. The auditors for Mona Lisa suspected an inventory shortage and used the gross profit method to estimate the ending inventory. The accounting records for the company contained the following information: 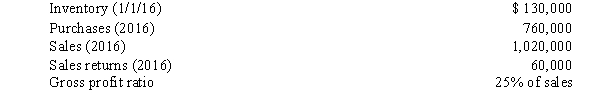 Using the gross profit method, what did the auditors estimate as the amount of the inventory that should have been on hand at December 31, 2016?
 (Multiple Choice)
4.9/5 (83)
(83) When applying lower of cost or net realizable value under the FIFO, average cost, or specific identification method, market value
(Multiple Choice)
4.8/5 (88)
(88) Scotland Inc. incurred a fire loss. Certain information follows: 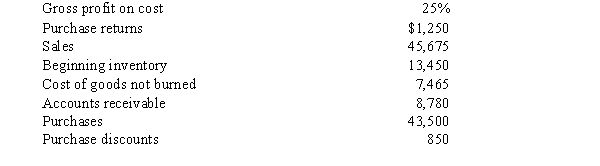 Required:
Using the gross profit method, compute the amount of the fire loss.
Required:
Using the gross profit method, compute the amount of the fire loss. (Essay)
5.0/5 (81)
(81) Given the following information for the Raquel Company who uses the periodic inventory system: 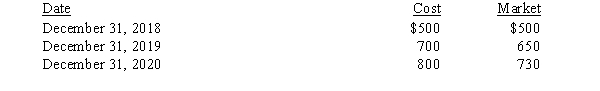 If the allowance method of recording lower of cost or NRV is in use, which December 31, 2020, journal entry is correct?
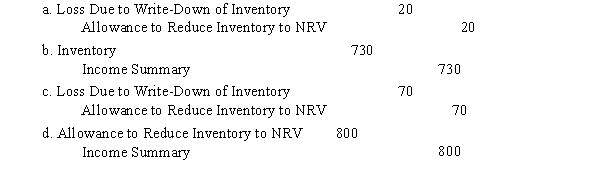
If the allowance method of recording lower of cost or NRV is in use, which December 31, 2020, journal entry is correct? (Short Answer)
4.8/5 (88)
(88) Ann Co. uses the dollar-value LIFO retail method. The beginning inventory, purchased when the price index was 100, had a retail value of $4,000 and a cost of $3,600. During the period, purchases amounted to $60,000 at retail $52,800 at cost). Sales amounted to $56,300. The year-end price index was 110. What is the cost of ending inventory?
(Multiple Choice)
4.8/5 (85)
(85) Which one of the following inventories may not be valued for balance sheet purposes at the inventory's selling price less distribution costs even if it is above the cost of the inventory?
(Multiple Choice)
4.8/5 (75)
(75) The Brad's Farm Company uses the retail inventory method to compute ending inventory. Information for last year is as follows: 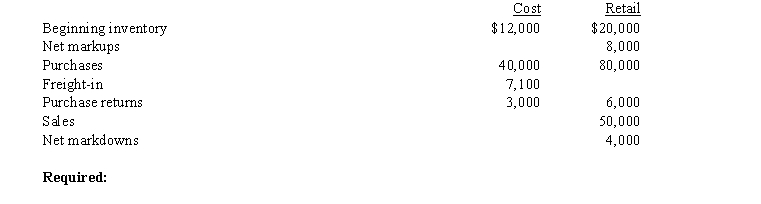 Determine Brad's Farm Company's ending inventory based on the retail lower of average cost or market method.
 (Essay)
4.8/5 (69)
(69) Lower of cost or NRV rule can be applied to periodic inventory. What are the two methods? Which one requires an entry to the loss due to write-down of inventory account?
(Short Answer)
4.9/5 (66)
(66) Companies may express their gross profit as a percentage of net sales or as a percentage of cost of goods sold. The following data are available on two different companies: 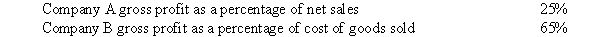 Required:
a. Compute the gross profit as a percentage of cost of goods sold for Company A.
b. Compute the gross profit as a percentage of net sales for Company B.
Required:
a. Compute the gross profit as a percentage of cost of goods sold for Company A.
b. Compute the gross profit as a percentage of net sales for Company B. (Essay)
4.9/5 (87)
(87) An auditor may not use the gross profit method to verify the accuracy of the reported cost of inventory.
(True/False)
4.8/5 (85)
(85) If a purchase on credit is omitted from the purchase account in error and ending inventory is correctly determined, net income for the period would be understated.
(True/False)
4.9/5 (87)
(87) Ending inventory is over stated due to an error, purchases were verified to be correct. What is the effect on the current year's income statement?
(Short Answer)
4.8/5 (80)
(80) The following information for five products A-E) was taken from the inventory records of the Walker Company who use the LIFO method: 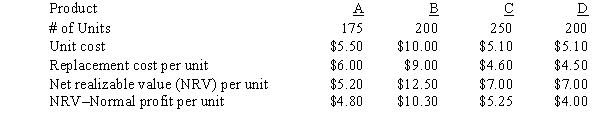 Required:
Determine the valuation of the inventory at the lower of cost or market applied to:
a. individual items
b. the inventory as a whole
Required:
Determine the valuation of the inventory at the lower of cost or market applied to:
a. individual items
b. the inventory as a whole (Essay)
4.7/5 (75)
(75) Audrey Company uses the LIFO retail inventory method and reports the following information: 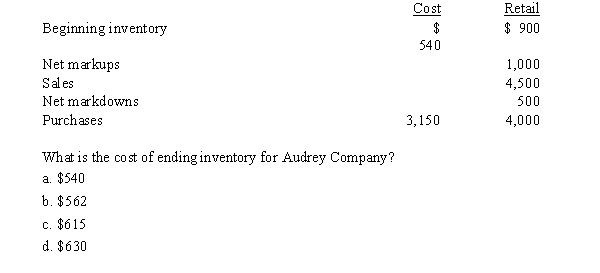
(Short Answer)
4.8/5 (94)
(94) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)