



 Chat with AI
Exam 11: Pricing Decisions and Profitability Analysis

Exam 1: Introduction to Management Accounting49 Questions
Exam 2: An Introduction to Cost Terms and Concepts64 Questions
Exam 3: Cost Assignment29 Questions
Exam 4: Accounting Entries for a Job Costing System15 Questions
Exam 5: Process Costing29 Questions
Exam 6: Joint and By-Product Costing61 Questions
Exam 7: Income Effects of Alternative Cost Accumulation Systems45 Questions
Exam 8: Cost-Volume-Profit Analysis60 Questions
Exam 9: Measuring Relevant Costs and Revenues for Decision-Making81 Questions
Exam 10: Activity-Based Costing40 Questions
Exam 11: Pricing Decisions and Profitability Analysis59 Questions
Exam 12: Decision-Making Under Conditions of Risk and Uncertainty29 Questions
Exam 13: Capital Investment Decisions: Appraisal Methods77 Questions
Exam 14: Capital Investment Decisions: the Impact of Capital Rationing, Taxation, Inflation and Risk25 Questions
Exam 15: The Budgeting Process86 Questions
Exam 16: Management Control Systems64 Questions
Exam 17: Standard Costing and Variance Analysis 181 Questions
Exam 18: Standard Costing and Variance Analysis 2: Further Aspects12 Questions
Exam 19: Divisional Financial Performance Measures51 Questions
Exam 20: Transfer Pricing in Divisionalized Companies50 Questions
Exam 21: Cost Management95 Questions
Exam 22: Strategic Management Accounting32 Questions
Exam 23: Cost Estimation and Cost Behaviour63 Questions
Exam 24: Quantitative Models for the Planning and Control of Stocks42 Questions
Exam 25: The Application of Linear Programming to Management Accounting30 Questions
Select questions type


Figure 12-3
The Lee Company must choose between two mutually exclusive alternatives. With alternative 1 an inferior product will be marketed that is best suited to low levels of demand whereas alternative 2 is a superior product that is best suited to high levels of demand. There are only two possible levels of demand - high and low and the probabilities of each event occurring is 0.5. The predicted profits for each alterative are: 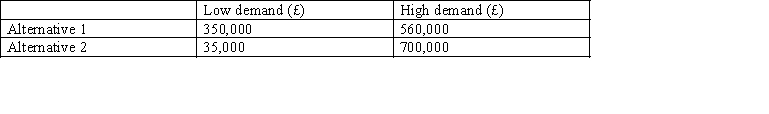 -The use of unit-based activity drivers to assign costs tends to
 (Multiple Choice)
4.8/5  (83)
(83) Maintenance of the production equipment would be classified as a
(Multiple Choice)
4.7/5 (72)
(72) Compare and contrast traditional organization-based costing with activity-based costing.
(Essay)
4.7/5 (73)
(73) An activity-based costing system uses which of the following procedures?
(Multiple Choice)
4.7/5 (76)
(76) Identify Cooper and Kaplan's four categories of activities and provide a brief description of each category.
(Essay)
4.8/5 (82)
(82) If activity-based costing is used, setups would be classified as a
(Multiple Choice)
4.9/5 (73)
(73) Figure 11-2
Owens Ltd. produces specially machined parts. The parts are produced in batches in one continuous manufacturing process. Each part is custom produced and requires special engineering design activity (based on customer specifications). Once the design is completed, the equipment can be set up for batch production. Once the batch is completed, a sample is taken and inspected to see if the parts are within the tolerances allowed. Thus, the manufacturing process has four activities: engineering, setups, machining, and inspecting. In addition, there is a sustaining process with two activities: providing utilities (plantwide) and providing space. Costs have been assigned to each activity using direct tracing and resource drivers:  Activity drivers for each activity have been identified and their practical capacities listed:
 The costs of facility-level activities are assigned using machine hours.
-Refer to Figure 11-2. What is the cost pool rate for the facility-level activities?
Activity drivers for each activity have been identified and their practical capacities listed: The costs of facility-level activities are assigned using machine hours.
-Refer to Figure 11-2. What is the cost pool rate for the facility-level activities? (Multiple Choice)
4.9/5 (67)
(67) The most critical step in activity-based costing is identifying cost drivers. Explain this statement.
(Essay)
4.7/5 (91)
(91) Figure 11-6
Peach, SA., has identified the following overhead costs and cost drivers for next year:  The following are two of the jobs completed during the year:
 The company's normal activity is 4,000 direct labour hours.
-Refer to Figure 11-6. If Peach, SA., used direct labour hours to assign overhead, the unit cost for Job 401 would be
The following are two of the jobs completed during the year: The company's normal activity is 4,000 direct labour hours.
-Refer to Figure 11-6. If Peach, SA., used direct labour hours to assign overhead, the unit cost for Job 401 would be (Multiple Choice)
4.9/5 (76)
(76) Figure 11-2
Owens Ltd. produces specially machined parts. The parts are produced in batches in one continuous manufacturing process. Each part is custom produced and requires special engineering design activity (based on customer specifications). Once the design is completed, the equipment can be set up for batch production. Once the batch is completed, a sample is taken and inspected to see if the parts are within the tolerances allowed. Thus, the manufacturing process has four activities: engineering, setups, machining, and inspecting. In addition, there is a sustaining process with two activities: providing utilities (plantwide) and providing space. Costs have been assigned to each activity using direct tracing and resource drivers: Activity drivers for each activity have been identified and their practical capacities listed: The costs of facility-level activities are assigned using machine hours.
-Refer to Figure 11-2. What is the cost pool overhead rate for the unit-level activities?
Activity drivers for each activity have been identified and their practical capacities listed: The costs of facility-level activities are assigned using machine hours.
-Refer to Figure 11-2. What is the cost pool overhead rate for the unit-level activities? (Multiple Choice)
4.8/5 (77)
(77) Hill Manufacturing uses an activity-based costing system. The company produces Model A and Model B. Information concerning the two products is as follows:  Required:
a.
Classify the following overhead activities as unit-level activities, batch-level activities, or product-level activities:
Power
Engineering
Setups
b.
Calculate the following:
A cost pool rate for power
A cost pool rate for setups
A cost pool rate for engineering
c.
Calculate the following:
Power costs assigned to Model B
Setups costs assigned to Model A
Engineering costs assigned to Model A
Required:
a.
Classify the following overhead activities as unit-level activities, batch-level activities, or product-level activities:
Power
Engineering
Setups
b.
Calculate the following:
A cost pool rate for power
A cost pool rate for setups
A cost pool rate for engineering
c.
Calculate the following:
Power costs assigned to Model B
Setups costs assigned to Model A
Engineering costs assigned to Model A (Essay)
4.9/5 (76)
(76) What is the initial step in implementing an activity-based costing system?
(Multiple Choice)
4.9/5 (93)
(93) Figure 11-1
Ubben Manufacturing uses an activity-based costing system. The company produces Model X and Model Y. Information relating to the two products is as follows:  The following costs are reported:
 -Refer to Figure 11-1. Setups would be classified as a
The following costs are reported:
-Refer to Figure 11-1. Setups would be classified as a (Multiple Choice)
4.8/5 (79)
(79) Figure 11-5
Granite, SA., has identified the following overhead costs and cost drivers for next year:  The following are two of the jobs completed during the year:
 The company's normal activity is 4,000 direct labour hours.
-Refer to Figure 11-5. If Granite, SA., used activity-based cost drivers to allocate overhead costs, the unit cost for Job 500 would be
The following are two of the jobs completed during the year: The company's normal activity is 4,000 direct labour hours.
-Refer to Figure 11-5. If Granite, SA., used activity-based cost drivers to allocate overhead costs, the unit cost for Job 500 would be (Multiple Choice)
4.8/5 (86)
(86) Ernest, SA., has identified the following overhead costs and cost drivers for next year:  The following are two of the jobs completed during the year:
 The company's normal activity is 32,000 direct labour hours. (Round amounts to two decimal places.)
Required:
a.
Determine the unit cost for each job using direct labour hours to apply overhead.
b.
Determine the unit cost for each job using the four cost drivers.
c.
Which method produces the more accurate cost assignment? Why?
The following are two of the jobs completed during the year: The company's normal activity is 32,000 direct labour hours. (Round amounts to two decimal places.)
Required:
a.
Determine the unit cost for each job using direct labour hours to apply overhead.
b.
Determine the unit cost for each job using the four cost drivers.
c.
Which method produces the more accurate cost assignment? Why? (Essay)
4.8/5 (69)
(69) Briefly discuss the problem with the unit-level approach to cost estimation and discuss some of the errors that may occur.
(Essay)
4.8/5 (74)
(74) Figure 12-3
The Lee Company must choose between two mutually exclusive alternatives. With alternative 1 an inferior product will be marketed that is best suited to low levels of demand whereas alternative 2 is a superior product that is best suited to high levels of demand. There are only two possible levels of demand - high and low and the probabilities of each event occurring is 0.5. The predicted profits for each alterative are:
-Riley, SA., has identified the following overhead costs and activity drivers for next year:  The following are two of the jobs completed during the year:
 The company's normal activity is 4,000 direct labour hours. If the activity drivers are used to allocate overhead costs, the unit cost (rounded to two decimal places) for Job BB would be
-Riley, SA., has identified the following overhead costs and activity drivers for next year: The following are two of the jobs completed during the year: The company's normal activity is 4,000 direct labour hours. If the activity drivers are used to allocate overhead costs, the unit cost (rounded to two decimal places) for Job BB would be (Multiple Choice)
5.0/5 (60)
(60) Figure 11-2
Owens Ltd. produces specially machined parts. The parts are produced in batches in one continuous manufacturing process. Each part is custom produced and requires special engineering design activity (based on customer specifications). Once the design is completed, the equipment can be set up for batch production. Once the batch is completed, a sample is taken and inspected to see if the parts are within the tolerances allowed. Thus, the manufacturing process has four activities: engineering, setups, machining, and inspecting. In addition, there is a sustaining process with two activities: providing utilities (plantwide) and providing space. Costs have been assigned to each activity using direct tracing and resource drivers: Activity drivers for each activity have been identified and their practical capacities listed: The costs of facility-level activities are assigned using machine hours.
-Refer to Figure 11-2. What is the cost pool rate for the batch-level activities?
Activity drivers for each activity have been identified and their practical capacities listed: The costs of facility-level activities are assigned using machine hours.
-Refer to Figure 11-2. What is the cost pool rate for the batch-level activities? (Multiple Choice)
4.9/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)