



 Chat with AI
Exam 16: Management Control Systems

Exam 1: Introduction to Management Accounting49 Questions
Exam 2: An Introduction to Cost Terms and Concepts64 Questions
Exam 3: Cost Assignment29 Questions
Exam 4: Accounting Entries for a Job Costing System15 Questions
Exam 5: Process Costing29 Questions
Exam 6: Joint and By-Product Costing61 Questions
Exam 7: Income Effects of Alternative Cost Accumulation Systems45 Questions
Exam 8: Cost-Volume-Profit Analysis60 Questions
Exam 9: Measuring Relevant Costs and Revenues for Decision-Making81 Questions
Exam 10: Activity-Based Costing40 Questions
Exam 11: Pricing Decisions and Profitability Analysis59 Questions
Exam 12: Decision-Making Under Conditions of Risk and Uncertainty29 Questions
Exam 13: Capital Investment Decisions: Appraisal Methods77 Questions
Exam 14: Capital Investment Decisions: the Impact of Capital Rationing, Taxation, Inflation and Risk25 Questions
Exam 15: The Budgeting Process86 Questions
Exam 16: Management Control Systems64 Questions
Exam 17: Standard Costing and Variance Analysis 181 Questions
Exam 18: Standard Costing and Variance Analysis 2: Further Aspects12 Questions
Exam 19: Divisional Financial Performance Measures51 Questions
Exam 20: Transfer Pricing in Divisionalized Companies50 Questions
Exam 21: Cost Management95 Questions
Exam 22: Strategic Management Accounting32 Questions
Exam 23: Cost Estimation and Cost Behaviour63 Questions
Exam 24: Quantitative Models for the Planning and Control of Stocks42 Questions
Exam 25: The Application of Linear Programming to Management Accounting30 Questions
Select questions type


Figure 16-1
Armati, SA., is looking for feedback on company performance. The company compares the budget for the year with the actual costs. Data have been collected below:
Armati, SA., had the following budgeted data: 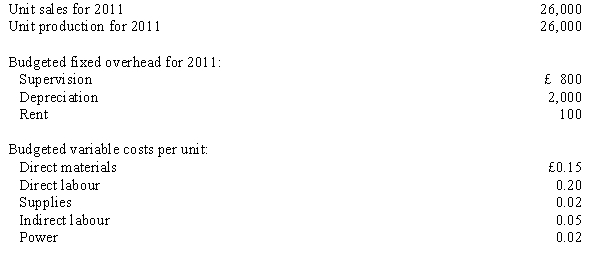 The following actually occurred:
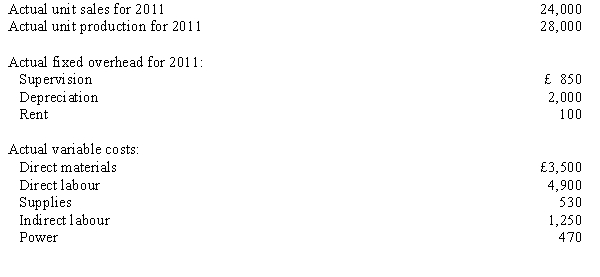 -Refer to Figure 16-1. The flexible budget variance for supervision for 2011 is
The following actually occurred:
-Refer to Figure 16-1. The flexible budget variance for supervision for 2011 is (Multiple Choice)
4.8/5  (90)
(90) Figure 16-1
Armati, SA., is looking for feedback on company performance. The company compares the budget for the year with the actual costs. Data have been collected below:
Armati, SA., had the following budgeted data: The following actually occurred:
-Refer to Figure 16-1. The flexible budget for rent in 2011 is
The following actually occurred:
-Refer to Figure 16-1. The flexible budget for rent in 2011 is (Multiple Choice)
4.9/5 (74)
(74) Classics, SA., uses a flexible budget for overhead costs. The company expects to produce 20,000 units of the product it manufactures. Half of the units require 0.50 direct labour hours per unit. The remainder requires 0.75 direct labour hours per unit. The cost formulas for each of the four overhead items is as follows: 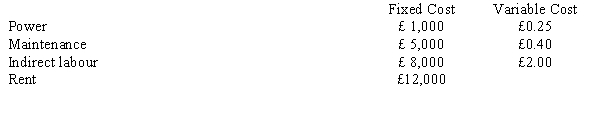 Required:
a.
Prepare an overhead budget for the expected activity level for the coming year.
b.
Prepare an overhead budget that reflects production that is 10 per cent higher than expected.
Required:
a.
Prepare an overhead budget for the expected activity level for the coming year.
b.
Prepare an overhead budget that reflects production that is 10 per cent higher than expected. (Essay)
4.7/5 (83)
(83) Figure 16-3
Harald, SA., has done a cost analysis for its production of bumper stickers. The following activities and cost drivers have been developed: 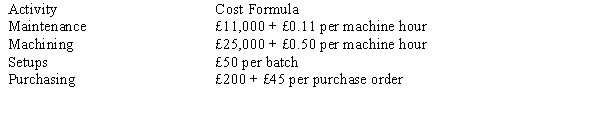 Following are the actual costs of producing 85,000 stickers: 5,000 machine hours; 10 batches; 20 purchase orders
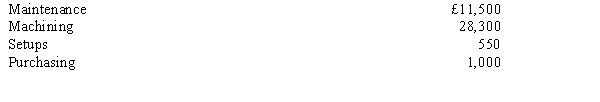 -Refer to Figure 16-3. What is the budget variance for setups in an activity-based performance report?
Following are the actual costs of producing 85,000 stickers: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-3. What is the budget variance for setups in an activity-based performance report? (Multiple Choice)
4.8/5 (72)
(72) Figure 16-3
Harald, SA., has done a cost analysis for its production of bumper stickers. The following activities and cost drivers have been developed: Following are the actual costs of producing 85,000 stickers: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-3. What is the budget variance for purchasing in an activity-based performance report?
Following are the actual costs of producing 85,000 stickers: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-3. What is the budget variance for purchasing in an activity-based performance report? (Multiple Choice)
4.8/5 (72)
(72) The static budget variance for materials is £200 F and the budgeted cost for materials is £52,000. If the budgeted volume is 13,000 and the actual volume is 13,500, then the flexible budget variance is
(Multiple Choice)
4.7/5 (79)
(79) Figure 16-5
Torino, SA., manufactures machine parts. Torino has developed a static budget for its plant at an activity level of 10,000 direct labour hours for the month of March. The actual level of activity was 11,000 hours. The following table summarizes the static budget and the actual costs for March: 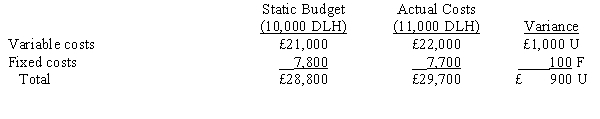 -Which of the following departments is likely to be evaluated as a discretionary cost centre?
 (Multiple Choice)
5.0/5 (75)
(75) Figure 16-4
Villafane, SA., has done a cost analysis for its production of decals. The following activities and cost drivers have been developed: 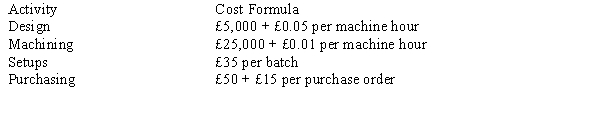 Following are the actual costs of producing 35,000 decals: 1,000 machine hours; 5 batches; 30 purchase orders
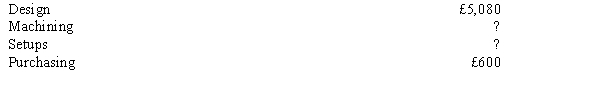 The following variances were given in the activity performance report:
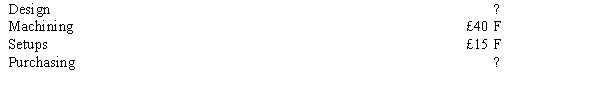 -Refer to Figure 16-4. What is the actual cost of setups?
Following are the actual costs of producing 35,000 decals: 1,000 machine hours; 5 batches; 30 purchase orders The following variances were given in the activity performance report:
-Refer to Figure 16-4. What is the actual cost of setups? (Multiple Choice)
4.7/5 (78)
(78) Figure 16-5
Torino, SA., manufactures machine parts. Torino has developed a static budget for its plant at an activity level of 10,000 direct labour hours for the month of March. The actual level of activity was 11,000 hours. The following table summarizes the static budget and the actual costs for March:
-What results could be expected by placing pressure on management to perform at certain levels?
-What results could be expected by placing pressure on management to perform at certain levels? (Multiple Choice)
4.7/5 (85)
(85) Which of the following is NOT a key feature of an ideal budgetary system?
(Multiple Choice)
4.9/5 (85)
(85) Figure 16-2
Glenn, SA., has done a cost analysis for its production of T-shirts. The following activities and cost drivers have been developed: 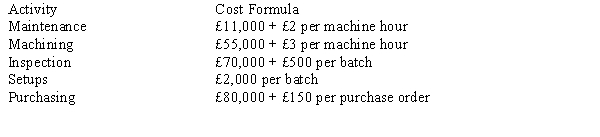 Following are the actual costs of producing 75,000 T-shirts: 5,000 machine hours; 10 batches; 20 purchase orders
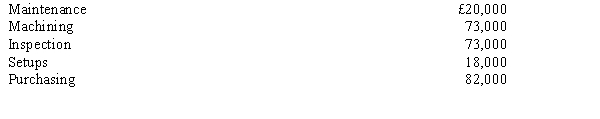 -Refer to Figure 16-2. What is the budget variance for purchasing in an activity-based performance report?
Following are the actual costs of producing 75,000 T-shirts: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-2. What is the budget variance for purchasing in an activity-based performance report? (Multiple Choice)
4.7/5 (76)
(76) Which of the following is NOT a potential disadvantage of participative budgeting?
(Multiple Choice)
4.8/5 (83)
(83) Which of the following is NOT a key feature of an ideal budgetary system?
(Multiple Choice)
4.8/5 (89)
(89) Figure 16-5
Torino, SA., manufactures machine parts. Torino has developed a static budget for its plant at an activity level of 10,000 direct labour hours for the month of March. The actual level of activity was 11,000 hours. The following table summarizes the static budget and the actual costs for March:
-Refer to Figure 16-5. What is the flexible budget for March?
-Refer to Figure 16-5. What is the flexible budget for March? (Multiple Choice)
4.9/5 (88)
(88) Figure 16-3
Harald, SA., has done a cost analysis for its production of bumper stickers. The following activities and cost drivers have been developed: Following are the actual costs of producing 85,000 stickers: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-3. What is the budget variance for maintenance in an activity-based performance report?
Following are the actual costs of producing 85,000 stickers: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-3. What is the budget variance for maintenance in an activity-based performance report? (Multiple Choice)
4.9/5 (81)
(81) Figure 16-2
Glenn, SA., has done a cost analysis for its production of T-shirts. The following activities and cost drivers have been developed: Following are the actual costs of producing 75,000 T-shirts: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-2. What is the budget variance for total costs in an activity-based performance report?
Following are the actual costs of producing 75,000 T-shirts: 5,000 machine hours; 10 batches; 20 purchase orders
-Refer to Figure 16-2. What is the budget variance for total costs in an activity-based performance report? (Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)