



 Chat with AI
Exam 17: Trusts

Exam 1: Taxation-Its Role in Decision Making8 Questions
Exam 2: Fundamentals of Tax Planning6 Questions
Exam 3: Liability for Tax, Income Determination, and Administration of the Income Tax System5 Questions
Exam 4: Income From Employment7 Questions
Exam 5: Income From Business7 Questions
Exam 6: The Acquisition, Use, and Disposal of Depreciable Property6 Questions
Exam 7: Income From Property6 Questions
Exam 8: Gains and Losses on the Disposition of Capital Property-Capital Gains7 Questions
Exam 9: Other Income, Other Deductions, and Special Rules for Completing Net Income for Tax Purposes6 Questions
Exam 10: Individuals: Determination of Taxable Income and Taxes Payable10 Questions
Exam 11: Corporations-An Introduction9 Questions
Exam 12: Organization, Capital Structures, and Income Distributions of Corporations9 Questions
Exam 13: The Canadian-Controlled Private Corporation9 Questions
Exam 14: Multiple Corporations and Their Reorganization7 Questions
Exam 15: Partnerships8 Questions
Exam 16: Limited Partnerships and Joint Ventures8 Questions
Exam 17: Trusts6 Questions
Exam 18: Business Acquisitions and Divestitures-Assets Versus Shares6 Questions
Exam 19: Business Acquisitions and Divestitures-Tax-Deferred Sales6 Questions
Exam 20: Domestic and International Business Expansion4 Questions
Exam 21: Tax Aspects of Corporate Financing7 Questions
Exam 22: Gsthst Overview5 Questions
Exam 23: Business Valuations7 Questions
Select questions type


Which of the following applies to a testamentary trust that is designated as a graduated rate estate (GRE)?

Free
(Multiple Choice)
5.0/5  (82)
(82) Correct Answer: Verified
B
Which of the following statements is TRUE regarding trusts?
Free
(Multiple Choice)
4.8/5 (74)
(74) Correct Answer:Verified
VerifiedB
Jasmine is the beneficiary of an inter vivos trust. During 20x4 the trust received the following income:
Capital gains: $16,000
Interest: $10,000
Non-eligible dividends: $8,000
One half of the trust's income from 20x4 was paid to Jasmine, who does not currently have any other sources of income. The remainder of the income remained in the trust.
Required:
a) Determine Jasmine's personal federal tax.
b) Calculate the federal tax for the trust.
(Round all amounts to zero decimal places. Apply rates for 2019.)
Free
(Essay)
4.8/5 (75)
(75) Correct Answer:Verified
Verified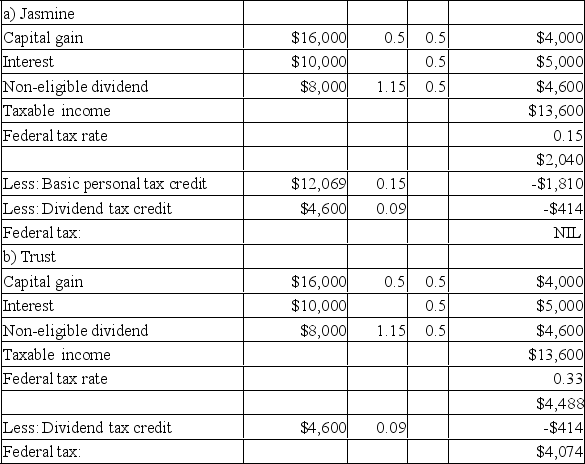
Briefly answer the following questions:
With regard to non-spousal trusts:
A) What is the purpose of the 21-Year Rule?
B) What event occurs on the 21st anniversary of a trust?
C) What types of properties are subject to the 21-Year Rule?
D) How can the consequences of the 21-Year Rule be avoided?
With regard to spousal trusts:
E) What is the exception to the 21-Year Rule for spousal trusts?
(Essay)
4.9/5 (88)
(88) Walter passed away this year, leaving a will bequeathing his wife with $80,000 in cash, in addition to his stocks and land, to be held in a spousal trust on her behalf. The trust will pay her the annual income generated by the trust during her lifetime.
Additionally, Walter's-33-year old son, Steven, is to receive a building to be held in a trust until Steven reaches the age of 45. Steven will also receive the assets in his mother's (Walter's wife) trust upon her death.
The assets transferred to Walter's wife consist of land with an ACB of $100,000 and a FMV of $300,000, and stocks valued at $200,000 with a cost base of $150,000.
The building transferred to Steven has an ACB of $200,000, UCC of $180,000, and FMV of $300,000.
Required:
A) What are the immediate tax consequences (identify the income type and amount) for Walter? Show calculations.
B) What are the immediate tax consequences for the assets received by the trust for Walter's wife?
(Essay)
4.8/5 (84)
(84) Which of the following statements is false with regard to spousal trusts?
(Multiple Choice)
5.0/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)