



 Chat with AI
Exam 9: Joint Product and By-Product Costing

Exam 1: The Role of Accounting Information in Ethical Management Decision Making100 Questions
Exam 2: Cost Concepts, Behaviour, and Estimation129 Questions
Exam 3: Cost-Volume-Profit Analysis147 Questions
Exam 4: Relevant Information for Decision Making135 Questions
Exam 5: Job Costing133 Questions
Exam 6: Process Costing114 Questions
Exam 7: Activity-Based Costing and Management132 Questions
Exam 8: Measuring and Assigning Support Department Costs115 Questions
Exam 9: Joint Product and By-Product Costing121 Questions
Exam 10: Static and Flexible Budgets128 Questions
Exam 11: Standard Costs and Variance Analysis128 Questions
Exam 12: Strategic Investment Decisions37 Questions
Exam 13: Pricing Decisions109 Questions
Exam 14: Strategic Management of Costs111 Questions
Exam 15: Measuring and Assigning Costs for Income Statements88 Questions
Exam 16: Performance Evaluation and Compensation39 Questions
Select questions type


Johnson Manufacturing Company buys Fluron for $0.80 per litre. At the end of processing in Department 1, Fluron splits off into products Alphon, Cryon, and Runon. Alphon is sold at the split-off point, with no further processing. Cryon and Runon require further processing before they can be sold. Cryon is processed in Department 2 and Runon is processed in Department 3. Following is a summary of costs and other related data for the year ended June 30, 20x5: 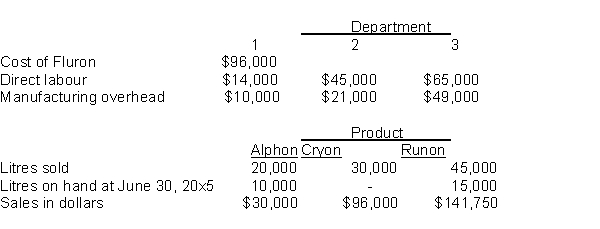 There were no inventories on hand at July 1, 20x4, and there was no Fluron on hand at June 30, 20x5. All litres on hand at June 30, 20x5 were complete as to processing. Johnson uses the net realizable value method of allocating joint costs.
For allocating joint costs, the net realizable value of Alphon for the year ended June 30, 20x5 would be:
There were no inventories on hand at July 1, 20x4, and there was no Fluron on hand at June 30, 20x5. All litres on hand at June 30, 20x5 were complete as to processing. Johnson uses the net realizable value method of allocating joint costs.
For allocating joint costs, the net realizable value of Alphon for the year ended June 30, 20x5 would be: (Multiple Choice)
4.8/5  (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)