



 Chat with AI
Exam 9: Joint Product and By-Product Costing

Exam 1: The Role of Accounting Information in Ethical Management Decision Making100 Questions
Exam 2: Cost Concepts, Behaviour, and Estimation129 Questions
Exam 3: Cost-Volume-Profit Analysis147 Questions
Exam 4: Relevant Information for Decision Making135 Questions
Exam 5: Job Costing133 Questions
Exam 6: Process Costing114 Questions
Exam 7: Activity-Based Costing and Management132 Questions
Exam 8: Measuring and Assigning Support Department Costs115 Questions
Exam 9: Joint Product and By-Product Costing121 Questions
Exam 10: Static and Flexible Budgets128 Questions
Exam 11: Standard Costs and Variance Analysis128 Questions
Exam 12: Strategic Investment Decisions37 Questions
Exam 13: Pricing Decisions109 Questions
Exam 14: Strategic Management of Costs111 Questions
Exam 15: Measuring and Assigning Costs for Income Statements88 Questions
Exam 16: Performance Evaluation and Compensation39 Questions
Select questions type


Jordan, Inc. produces 2 products from a joint process costing $24,000. The results from the most recent period follow: Sales Value Separable Sales Value After Product Tons at Split-Off Costs Further Processing Alpha-1 800 \ 10,000 \ 12,000 \ 24,000 Alpha-2 400 8,000 4,000 20,000 Waste 200 -- --- --
If Jordan uses the net realizable value method, the joint costs allocated to Alpha-1 would be:
(Multiple Choice)
4.9/5  (76)
(76) When individual products/services become separately identifiable, this is called the:
(Multiple Choice)
4.8/5 (78)
(78) HGT Corporation produces four products from a common production process. Selected data from HGT's accounting system for the four products appears below:  Joint costs for the accounting period totalled $5,000. Each product line has a different product manager who is evaluated based on product line profitability. Therefore each manager is motivated to reduce his / her total product line costs as much as possible. The managers have been given information about potential joint cost allocations using the following three methods: physical output, sales at split-off point, and net realizable value. The managers are comparing the joint cost allocations under each method so that they can give the accountant input about their preferred method(s).
If HGT allocates joint costs using the physical output method, the total joint cost allocated to standard pillows will be:
Joint costs for the accounting period totalled $5,000. Each product line has a different product manager who is evaluated based on product line profitability. Therefore each manager is motivated to reduce his / her total product line costs as much as possible. The managers have been given information about potential joint cost allocations using the following three methods: physical output, sales at split-off point, and net realizable value. The managers are comparing the joint cost allocations under each method so that they can give the accountant input about their preferred method(s).
If HGT allocates joint costs using the physical output method, the total joint cost allocated to standard pillows will be: (Multiple Choice)
4.8/5 (60)
(60) Which joint cost allocation method best reflects the idea that joint costs cannot be separated?
(Multiple Choice)
4.8/5 (72)
(72) The Great Foods Company processes milk into skim milk and butter. This year 70,000 litres of milk will be processed, costing $40,000. If processed to the split-off point, this will yield 40,000 litres of skim milk and 10,000 kilograms of butter. Skim milk is sold to distributors for $1 per litre and butter is sold for $0.75 per kilogram. Great Foods has the option of processing the two products further. Skim milk can be processed into canned, sweetened and condensed skim milk and sold for $0.80 per can. One litre of skim milk makes 2 cans of condensed milk. To process 40,000 litres of skim milk it will cost $18,000. Butter can be processed into cake frosting and sold in containers for $2 each. One kilogram of butter goes into each container of frosting. The cost of processing 10,000 kilograms of butter into frosting costs $15,000.
What is the per-unit joint cost allocated to condensed milk and frosting under the physical output method if the number of units of output after further processing is used to measure output?
(Multiple Choice)
5.0/5 (77)
(77) Which method of allocating joint costs is most likely to develop a true cost per unit of product?
(Multiple Choice)
5.0/5 (79)
(79) Costs allocated to joint products are generally referred to as separable costs.
(True/False)
4.8/5 (83)
(83) Johnson Manufacturing Company buys Fluron for $0.80 per litre. At the end of processing in Department 1, Fluron splits off into products Alphon, Cryon, and Runon. Alphon is sold at the split-off point, with no further processing. Cryon and Runon require further processing before they can be sold. Cryon is processed in Department 2 and Runon is processed in Department 3. Following is a summary of costs and other related data for the year ended June 30, 20x5: 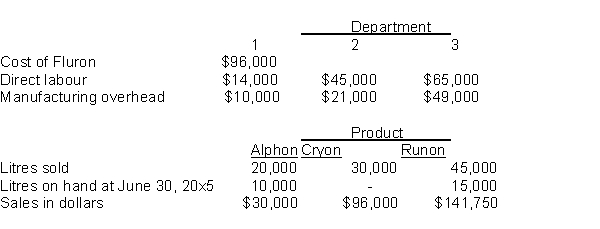 There were no inventories on hand at July 1, 20x4, and there was no Fluron on hand at June 30, 20x5. All litres on hand at June 30, 20x5 were complete as to processing. Johnson uses the net realizable value method of allocating joint costs.
The value of the ending inventory for Alphon is:
There were no inventories on hand at July 1, 20x4, and there was no Fluron on hand at June 30, 20x5. All litres on hand at June 30, 20x5 were complete as to processing. Johnson uses the net realizable value method of allocating joint costs.
The value of the ending inventory for Alphon is: (Multiple Choice)
4.7/5 (75)
(75) A joint input costing $500 results in four distinct products at the point of split-off. Relevant data follows: Sales Value Separable Sales Value After Product at Split-Off Cost Further Processing J \ 200 \ 100 \ 400 K 300 200 600 L 100 50 140 M 20 10 40
Assume that K is processed further and that management is considering an alternative to the current process. The new separable cost of processing would be $250. If the firm is to be no worse off, the product must sell for at least:
(Multiple Choice)
4.8/5 (79)
(79) RKH Corporation produces three joint products. During a recent accounting period, joint costs totalled $365 and RKH had no beginning inventories. Additional data appear below: Volume (kilograms) 150 50 300 Sales value at the split-off point \ 375 \ 155 \ 600 Sales value after further processing \ 450 \ 200 \ 900 Separable costs \ 50 \ 35 \ 100 Which of the following methods will result in the greatest total joint cost allocation among the three products?
I. Net realizable value
II. Sales value at split-off point
III. Physical output
IV. Constant gross margin NRV
(Multiple Choice)
4.9/5 (86)
(86) RKH Corporation produces three joint products. During a recent accounting period, joint costs totalled $365 and RKH had no beginning inventories. Additional data appear below: Volume (kilograms) 150 50 300 Sales value at the split-off point \ 375 \ 155 \ 600 Sales value after further processing \ 450 \ 200 \ 900 Separable costs \ 50 \ 35 \ 100 Using the constant gross margin NRV method, the combined gross margin percentage (rounded to the nearest whole percent) is:
(Multiple Choice)
4.9/5 (88)
(88) The sales value at split-off point method of joint cost allocation avoids the problem of negative contribution margins for some products.
(True/False)
4.9/5 (84)
(84) The choice of joint cost allocation method depends somewhat on the nature of the products' characteristics.
(True/False)
4.8/5 (83)
(83) By-products are:
I. Products of a joint process that are relatively immaterial compared to main products
II. Products of a joint process that are relatively material compared to main products
III. Not allocated joint costs
IV. Allocated joint costs
(Multiple Choice)
4.9/5 (71)
(71) Cost distortions are likely when products have differential incremental contributions under which of the following methods?
(Multiple Choice)
4.9/5 (60)
(60) J-M Company uses a joint process costing $15,000 to produce three main products. The company had no beginning inventory. Its current period operation data follow: Units Sales Value Separable Sales Value After Units Product Produced at Split-Off Costs Further Processing Sold S 500 \ 5,000 \ 500 \ 7,000 400 T 450 6,000 650 9,000 300 R 300 9,000 700 10,000 250 If J-M uses the sales value at split-off point method and sells products at the split-off point, what is the gross profit for product T? Note: the sales values above are based on units produced.
(Multiple Choice)
4.8/5 (77)
(77) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)