



 Chat with AI
Exam 15: Stockholders Equity

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Porter Corp. purchased its own par value stock on January 1, 2014 for $20,000 and debited the treasury stock account for the purchase price. The stock was subsequently sold for $12,000. The $8,000 difference between the cost and sales price should be recorded as a deduction from
(Multiple Choice)
4.8/5  (62)
(62) Pierson Corporation owned 10,000 shares of Hunter Corporation. These shares were purchased in 2011 for $90,000. On November 15, 2015, Pierson declared a property dividend of one share of Hunter for every ten shares of Pierson held by a stockholder. On that date, when the market price of Hunter was $28 per share, there were 90,000 shares of Pierson outstanding. What gain and net reduction in retained earnings would result from this property dividend? 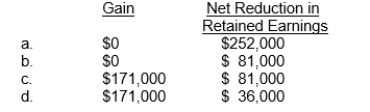
(Short Answer)
4.7/5 (77)
(77) Stock splits and large stock dividends have the same effect on a company's retained earnings and total stockholders' equity.
(True/False)
4.8/5 (77)
(77) A mining company declared a liquidating dividend. The journal entry to record the declaration must include a debit to
(Multiple Choice)
4.8/5 (87)
(87) Stinson Corporation owned 30,000 shares of Matile Corporation. These shares were purchased in 2011 for $270,000. On November 15, 2015, Stinson declared a property dividend of one share of Matile for every ten shares of Stinson held by a stockholder. On that date, when the market price of Matile was $28 per share, there were 270,000 shares of Stinson outstanding. What gain and net reduction in retained earnings would result from this property dividend? 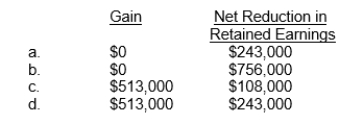
(Short Answer)
4.9/5 (80)
(80) If management wishes to "capitalize" part of the earnings, it may issue a
(Multiple Choice)
4.8/5 (90)
(90) The current project of the IASB and the FASB related to financial statement presentation indicates
(Multiple Choice)
4.9/5 (83)
(83) The preemptive right allows stockholders the right to vote for directors of the company.
(True/False)
4.8/5 (77)
(77) On January 1, 2014, Dodd, Inc., declared a 15% stock dividend on its common stock when the fair value of the common stock was $30 per share. Stockholders' equity before the stock dividend was declared consisted of: 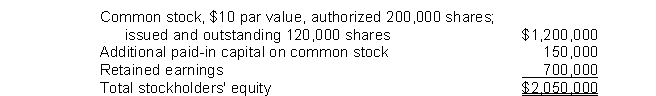 What was the effect on Dodd's retained earnings as a result of the above transaction?
 (Multiple Choice)
4.8/5 (73)
(73) At the beginning of 2015, Flaherty Company had retained earnings of $350,000. During the year Flaherty reported net income of $100,000, sold treasury stock at a "gain" of $36,000, declared a cash dividend of $60,000, and declared and issued a small stock dividend of 3,000 shares ($10 par value) when the fair value of the stock was $20 per share. The amount of retained earnings available for dividends at the end of 2015 was
(Multiple Choice)
4.8/5 (85)
(85) Under IFRS compliance requirements the revaluation surplus is not considered contributed capital.
(True/False)
4.9/5 (92)
(92) The declaration and issuance of a stock dividend larger than 25% of the shares previously outstanding
(Multiple Choice)
4.7/5 (86)
(86) How should a "gain" from the sale of treasury stock be reflected when using the cost method of recording treasury stock transactions?
(Multiple Choice)
4.8/5 (87)
(87) Written, Inc. has outstanding 600,000 shares of $2 par common stock and 120,000 shares of no-par 8% preferred stock with a stated value of $5. The preferred stock is cumulative and nonparticipating. Dividends have been paid in every year except the past two years and the current year.Assuming that $366,000 will be distributed, and the preferred stock is also participating, how much will the common stockholders receive?
(Multiple Choice)
4.9/5 (79)
(79) What effect does the issuance of a 2-for-1 stock split have on each of the following? 
(Short Answer)
4.9/5 (79)
(79) When a corporation sells treasury stock below its cost, it usually debits the difference between cost and selling price to Paid-in Capital from Treasury Stock.
(True/False)
4.8/5 (77)
(77) The payout ratio is determined by dividing cash dividends paid to common stockholders by net income available to common stockholders.
(True/False)
4.9/5 (84)
(84) All dividends, except for liquidating dividends, reduce the total stockholders' equity of a corporation.
(True/False)
4.8/5 (88)
(88) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)