



 Chat with AI
Exam 17: Investments

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


A debt security is transferred from one category to another. Generally acceptable accounting principles require that for this particular reclassification (1) the security be transferred at fair value at the date of transfer, and (2) the unrealized gain or loss at the date of transfer currently carried as a separate component of stockholders' equity be amortized over the remaining life of the security. What type of transfer is being described?
(Multiple Choice)
4.9/5  (83)
(83) Securities which could be classified as held-to-maturity are
(Multiple Choice)
4.9/5 (75)
(75) The accounting for fair value hedges records the derivative at its
(Multiple Choice)
4.9/5 (80)
(80) Use the following information for questions 74 and 75.
Landis Company purchased $2,000,000 of 8%, 5-year bonds from Ritter, Inc. on January 1, 2014, with interest payable on July 1 and January 1. The bonds sold for $2,083,160 at an effective interest rate of 7%. Using the effective-interest method, Landis Company decreased the Available-for-Sale Debt Securities account for the Ritter, Inc. bonds on July 1, 2014 and December 31, 2014 by the amortized premiums of $7,080 and $7,320, respectively.
-At December 31, 2014, the fair value of the Ritter, Inc. bonds was $2,120,000. What should Landis Company report as other comprehensive income and as a separate component of stockholders' equity?
(Multiple Choice)
4.8/5 (75)
(75) At February 1, 2015, Richman Company sold the Carlin bonds for $927,000. After accruing for interest, the carrying value of the Carlin bonds on February 1, 2015 was $930,375. Assuming Richman Company has a portfolio of available-for-sale debt investments, what should Richman Company report as a gain (or loss) on the bonds?
(Multiple Choice)
4.8/5 (77)
(77) Myers Company acquired a 60% interest in Gannon Corporation on December 31, 2014 for $1,575,000. During 2015, Gannon had net income of $1,000,000 and paid cash dividends of $250,000. At December 31, 2015, the balance in the investment account should be
(Multiple Choice)
4.8/5 (80)
(80) Which of the following is not generally correct about recording a sale of a debt security before maturity date?
(Multiple Choice)
4.9/5 (83)
(83) Companies that attempt to exploit inefficiencies in various derivative markets by attempting to lock in profits by simultaneously entering into transactions in two or more markets are called
(Multiple Choice)
4.8/5 (67)
(67) Under the equity method of accounting for investments, an investor recognizes its share of the earnings in the period in which the
(Multiple Choice)
4.8/5 (63)
(63) When an investment in an available-for-sale security is transferred to trading because the company anticipates selling the stock in the near future, the carrying value assigned to the investment upon entering it in the trading portfolio should be
(Multiple Choice)
4.8/5 (85)
(85) At December 31, 2015, Atlanta Company has a stock portfolio valued at $80,000. Its cost was $66,000. If the Securities Fair Value Adjustment (Available-for-Sale) has a debit balance of $4,000, which of the following journal entries is required at December 31, 2015? 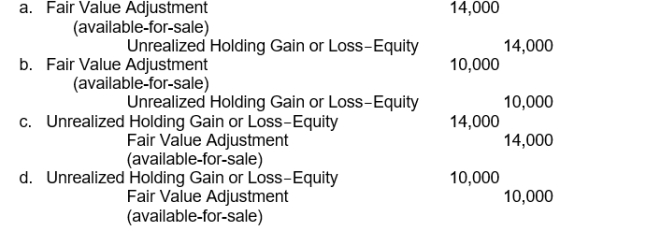
(Short Answer)
5.0/5 (70)
(70) Companies may not use the fair value option for investments that follow the equity method of accounting.
(True/False)
4.9/5 (81)
(81) When a company has acquired a "passive interest" in another corporation, the acquiring company should account for the investment
(Multiple Choice)
4.7/5 (79)
(79) On May 1, 2014, Kirmer Corporation purchased $900,000 of 12% bonds, interest payable on January 1 and July 1, for $843,900 plus accrued interest. The bonds mature on January 1, 2020. Amortization is recorded when interest is received by the straight-line method (by months and round to the nearest dollar). (Assume bonds are available for sale.)
Instructions
(a) Prepare the entry for May 1, 2014.
(b) The bonds are sold on August 1, 2015 for $565,000 plus accrued interest. Prepare all entries required to properly record the sale.
(Essay)
4.8/5 (85)
(85) Under IFRS, impairment charges related to held-for-collection debt securities may be reversed.
(True/False)
4.9/5 (79)
(79) The accounting profession has concluded that an investment of more than 50 percent of the voting stock of an investee should lead to a presumption of significant influence over an investee.
(True/False)
4.9/5 (66)
(66) The Unrealized Holding Gain/Loss-Equity account is reported as a part of other compre-hensive income.
(True/False)
5.0/5 (75)
(75) Companies report trading securities at fair value, with unrealized holding gains and losses reported in net income.
(True/False)
4.8/5 (70)
(70) On January 2, 2014, Sloan Company issued a 5-year, $9,000,000 note at LIBOR with interest paid annually. The variable rate is reset at the end of each year. The LIBOR rate for the first year is 6.8%Sloan Company decides it prefers fixed-rate financing and wants to lock in a rate of 6%. As a result, Sloan enters into an interest rate swap to pay 7% fixed and receive LIBOR based on $9 million. The variable rate is reset to 7.4% on January 2, 2015.
Instructions
(a) Compute the net interest expense to be reported for this note and related swap transactions as of December 31, 2014.
(b) Compute the net interest expense to be reported for this note and related swap transactions as of December 31, 2015.
(Essay)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)