



 Chat with AI
Exam 18: Revenue Recognition

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Fryman Furniture uses the installment-sales method. No further collections could be made on an account with a balance of $24,000. It was estimated that the repossessed furniture could be sold as is for $7,200, or for $8,400 if $400 were spent reconditioning it. The gross profit rate on the original sale was 40%. The loss on repossession was
(Multiple Choice)
4.9/5  (79)
(79) Use the following information for questions 80 and 81.
-If the completed-contract method of accounting was used, the amount of gross profit to be recognized for years 2014 and 2015 would be 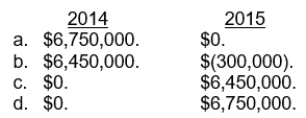
(Short Answer)
4.7/5 (83)
(83) The revenue recognition principle provides that revenue is recognized when (1) it is realized or realizable and (2) it is earned.
InstructionsExplain when revenues are
(a) realized, (b) realizable, and (c) earned.
(Essay)
4.9/5 (90)
(90) Which of the following is not a reason why revenue is recognized at the time of sale?
(Multiple Choice)
4.7/5 (77)
(77) Under the installment-sales method, companies defer revenue and income recognition until the period of cash collection.
(True/False)
4.7/5 (85)
(85) On January 1, 2015 Dairy Treats, Inc. entered into a franchise agreement with a company allowing the company to do business under Dairy Treats's name. Dairy Treats had performed substantially all required services by January 1, 2015, and the franchisee paid the initial franchise fee of $840,000 in full on that date. The franchise agreement specifies that the franchisee must pay a continuing franchise fee of $72,000 annually, of which 20% must be spent on advertising by Dairy Treats. What entry should Dairy Treats make on January 1, 2015 to record receipt of the initial franchise fee and the continuing franchise fee for 2015? 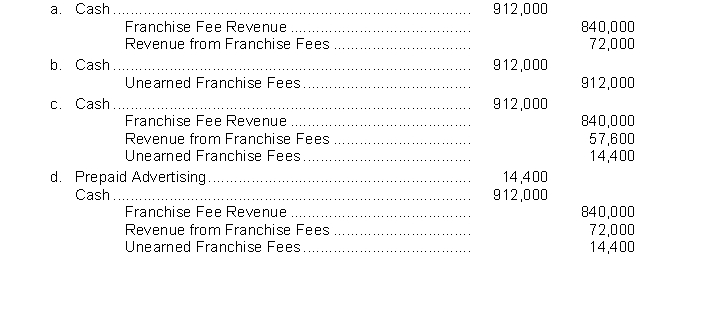
(Short Answer)
4.8/5 (86)
(86) Use the following information for questions 73 and 74.
In 2015, Fargo Corporation began construction work under a three-year contract. The contract price is $4,800,000. Fargo uses the percentage-of-completion method for financial accounting purposes. The income to be recognized each year is based on the proportion of costs incurred to total estimated costs for completing the contract. The financial statement presentations relating to this contract at December 31, 2015, follow:  -How much cash was collected in 2015 on this contract?
 (Multiple Choice)
4.9/5 (87)
(87) Crane, Inc. is a retailer of home appliances and offers a service contract on each appliance sold. Crane sells appliances on installment contracts, but all service contracts must be paid in full at the time of sale. Collections received for service contracts should be recorded as an increase in a
(Multiple Choice)
4.8/5 (73)
(73) Use the following information for questions 80 and 81.
-Horner Construction Co. uses the percentage-of-completion method. In 2014, Horner began work on a contract for $16,500,000; it was completed in 2015. The following cost data pertain to this contract:  The amount of gross profit to be recognized on the income statement for the year ended December 31, 2015 is
 (Multiple Choice)
4.7/5 (80)
(80) Use the following information for questions 73 and 74.
In 2015, Fargo Corporation began construction work under a three-year contract. The contract price is $4,800,000. Fargo uses the percentage-of-completion method for financial accounting purposes. The income to be recognized each year is based on the proportion of costs incurred to total estimated costs for completing the contract. The financial statement presentations relating to this contract at December 31, 2015, follow:
-What was the initial estimated total income before tax on this contract?
-What was the initial estimated total income before tax on this contract? (Multiple Choice)
4.8/5 (74)
(74) The provision for a loss on an unprofitable contract may be combined with the Construction in Process account balance under percentage-of-completion but not completed-contract.
(True/False)
4.8/5 (83)
(83) The installment-sales method defers only the gross profit instead of both the sales price and cost of goods sold.
(True/False)
4.9/5 (79)
(79) Once the separate units of accounting are determined under multiple-deliverable arrangement, the amount paid for the arrangement is allocated among the separate units based on cost of manufacturing the separate unit.
(True/False)
4.7/5 (90)
(90) The principal advantage of the completed-contract method is that reported revenue reflects final results rather than estimates.
(True/False)
4.9/5 (89)
(89) Under IFRS, the standard for revenue recognition states that the
I.Revenue be realized or realizable.
II.Economic benefits associated with the transaction will flow to the company selling the goods
III.Costs must be capable of being reliably measured.
(Multiple Choice)
4.9/5 (83)
(83) In certain cases, revenue is recognized at the completion of production even though no sale has been made. Which of the following statements is not true?
(Multiple Choice)
4.9/5 (88)
(88) In accounting for long-term construction contracts (those taking longer than one year to complete), the two methods commonly followed are the percentage-of-completion and completed-contract methods.
Instructions
(a) Discuss how earnings on long-term construction contracts are recognized and computed under these two methods.
(b) Under what circumstances should one method be used over the other?
(c) How are job costs and interim billings reflected on the balance sheet under the percentage-of-completion method and the completed-contract method?
(Essay)
4.8/5 (90)
(90) The principal advantage of the completed-contract method is that
(Multiple Choice)
4.8/5 (76)
(76) Spicer Corporation has a normal gross profit on installment sales of 30%. A 2013 sale resulted in a default early in 2015. At the date of default, the balance of the installment receivable was $32,000, and the repossessed merchandise had a fair value of $18,000. Assuming the repossessed merchandise is to be recorded at fair value, the gain or loss on repossession should be
(Multiple Choice)
4.9/5 (76)
(76) The method most commonly used to report defaults and repossessions is
(Multiple Choice)
4.9/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)