



 Chat with AI
Exam 21: Accounting for Leases

Exam 1: Financial Accounting and Accounting Standards103 Questions
Exam 2: Conceptual Framework for Financial Reporting155 Questions
Exam 3: The Accounting Information System144 Questions
Exam 4: Income Statement and Related Information139 Questions
Exam 5: Balance Sheet and Statement of Cash Flows127 Questions
Exam 6: Accounting and the Time Value of Money152 Questions
Exam 7: Cash and Receivables173 Questions
Exam 8: Valuation of Inventories: a Cost-Basis Approach173 Questions
Exam 9: Inventories: Additional Valuation Issues168 Questions
Exam 10: Acquisition and Disposition of Property, Plant, and Equipment170 Questions
Exam 11: Depreciation, Impairments, and Depletion156 Questions
Exam 12: Intangible Assets171 Questions
Exam 13: Current Liabilities and Contingencies170 Questions
Exam 14: Long-Term Liabilities140 Questions
Exam 15: Stockholders Equity155 Questions
Exam 16: Dilutive Securities and Earnings Per Share160 Questions
Exam 17: Investments141 Questions
Exam 18: Revenue Recognition145 Questions
Exam 19: Accounting for Income Taxes127 Questions
Exam 20: Accounting for Pensions and Postretirement Benefits137 Questions
Exam 21: Accounting for Leases128 Questions
Exam 22: Accounting Changes and Error Analysis103 Questions
Exam 23: Statement of Cash Flows143 Questions
Exam 24: Full Disclosure in Financial Reporting108 Questions
Exam 25: Appendix89 Questions
Select questions type


Hook Company leased equipment to Emley Company on July 1, 2014, for a one-year period expiring June 30, 2015, for $60,000 a month. On July 1, 2015, Hook leased this piece of equipment to Terry Company for a three-year period expiring June 30, 2018, for $75,000 a month. The original cost of the equipment was $4,800,000. The equipment, which has been continually on lease since July 1, 2010, is being depreciated on a straight-line basis over an eight-year period with no salvage value. Assuming that both the lease to Emley and the lease to Terry are appropriately recorded as operating leases for accounting purposes, what is the amount of income (expense) before income taxes that each would record as a result of the above facts for the year ended December 31, 2015? 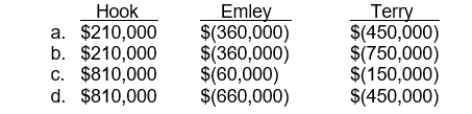
(Short Answer)
4.8/5  (85)
(85) IFRS requires that companies provide a year-by-year breakout of future noncancelable lease payments due in years 1 through 5.
(True/False)
4.9/5 (83)
(83) Eubank Company, as lessee, enters into a lease agreement on July 1, 2014, for equipment. The following data are relevant to the lease agreement:1. The term of the noncancelable lease is 4 years, with no renewal option. Payments of $782,757 are due on July 1 of each year.2. The fair value of the equipment on July 1, 2014 is $2,800,000. The equipment has an economic life of 6 years with no salvage value.3. Eubank depreciates similar machinery it owns on the sum-of-the-years'-digits basis.4. The lessee pays all executory costs."5. Eubank's incremental borrowing rate is 10% per year. The lessee is aware that the lessor used an implicit rate of 8% in computing the lease payments (present value factor for 4 periods at 8%, 3.57710; at 10%, 3.48685.
Instructions
(a) Indicate the type of lease Eubank Company has entered into and what accounting treatment is applicable.
(b) Prepare the journal entries on Eubank's books that relate to the lease agreement for the following dates: (Round all amounts to the nearest dollar. Include a partial amortization schedule.)"1. July 1, 2014.2. December 31, 2014.3. July 1, 2015.4. December 31, 2015.
(Essay)
4.9/5 (74)
(74) Use the following information for questions 65 and 66.
On January 1, 2014, Ogleby Corporation signed a five-year noncancelable lease for equipment. The terms of the lease called for Ogleby to make annual payments of $90,000 at the beginning of each year for five years with title passing to Ogleby at the end of this period. The equipment has an estimated useful life of 7 years and no salvage value. Ogleby uses the straight-line method of depreciation for all of its fixed assets. Ogleby accordingly accounts for this lease transaction as a capital lease. The minimum lease payments were determined to have a present value of $375,289 at an effective interest rate of 10%.
-With respect to this capitalized lease, for 2015 Ogleby should record
(Multiple Choice)
4.9/5 (92)
(92) Which of the following statements is true when comparing the accounting for leasing transactions under U.S. GAAP with IFRS?
(Multiple Choice)
4.8/5 (80)
(80) Jamar Co. sold its headquarters building at a gain, and simultaneously leased back the building. The lease was reported as a capital lease. At the time of the sale, the gain should be reported as
(Multiple Choice)
4.9/5 (80)
(80) Pisa, Inc. leased equipment from Tower Company under a four-year lease requiring equal annual payments of $172,076, with the first payment due at lease inception. The lease does not transfer ownership, nor is there a bargain purchase option. The equipment has a 4-year useful life and no salvage value. Pisa, Inc.'s incremental borrowing rate is 10% and the rate implicit in the lease (which is known by Pisa, Inc.) is 8%. Pisa, Inc. uses the straight-line method to depreciate similar assets. What is the amount of depreciation expense recorded by Pisa, Inc. in the first year of the asset's life? 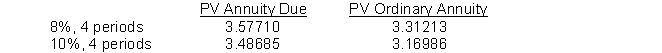
(Multiple Choice)
4.7/5 (69)
(69) Lucas, Inc. enters into a lease agreement as lessor on January 1, 2015, to lease an airplane to National Airlines. The term of the noncancelable lease is eight years and payments are required at the end of each year. The following information relates to this agreement:1. National Airlines has the option to purchase the airplane for $12,000,000 when the lease expires at which time the fair value is expected to be $20,000,000.2. The airplane has a cost of $51,000,000 to Lucas, an estimated useful life of fourteen years, and a salvage value of zero at the end of that time (due to technological obsolescence).3. National Airlines will pay all executory costs related to the leased airplane.4. Annual beginning of year lease payments of $1,172,753 allow Lucas to earn an 8% return on its investment."5. Collectibility of the payments is reasonably predictable, and there are no important uncertainties surrounding the costs yet to be incurred by Lucas.
Instructions
(a) What type of lease is this? Discuss.
(b) Prepare a lease amortization schedule for the lessor for the first two years (2015-2016). (Round all amounts to nearest dollar.)(c) Prepare the journal entries on the books of the lessor to record the lease agreement, to reflect payments received under the lease, and to recognize revenue, for 2015."
(Essay)
4.9/5 (89)
(89) What impact does a bargain purchase option have on the present value of the minimum lease payments computed by the lessee?
(Multiple Choice)
4.9/5 (69)
(69) A lessor with a sales-type lease involving an unguaranteed residual value available to the lessor at the end of the lease term will report sales revenue in the period of inception of the lease at which of the following amounts?
(Multiple Choice)
4.7/5 (80)
(80) Pisa, Inc. leased equipment from Tower Company under a four-year lease requiring equal annual payments of $172,076, with the first payment due at lease inception. The lease does not transfer ownership, nor is there a bargain purchase option. The equipment has a 4 year useful life and no salvage value. Pisa, Inc.'s incremental borrowing rate is 10% and the rate implicit in the lease (which is known by Pisa, Inc.) is 8%. Assuming that this lease is properly classified as a capital lease, what is the amount of principal reduction recorded when the second lease payment is made in Year 2? 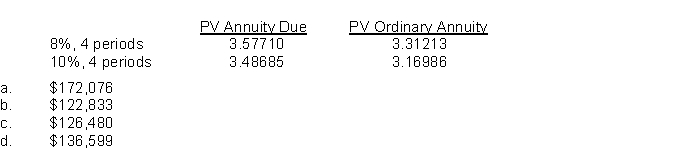
(Short Answer)
4.7/5 (87)
(87) What is the amount of the lessee's liability to the lessor after the December 31, 2016 payment? (Rounded to the nearest dollar.)
(Multiple Choice)
4.7/5 (76)
(76) Roman Company leased equipment from Koenig Company on July 1, 2015, for an eight-year period expiring June 30, 2023. Equal annual payments under the lease are $600,000 and are due on July 1 of each year. The first payment was made on July 1, 2015. The rate of interest contemplated by Roman and Koenig is 8%. The cash selling price of the equipment is $3,723,750 and the cost of the equipment on Koenig's accounting records was $3,300,000. Assuming that the lease is appropriately recorded as a sale for accounting purposes by Koenig, what is the amount of profit on the sale and the interest income that Koenig would record for the year ended December 31, 2015?
(Multiple Choice)
4.8/5 (77)
(77) On January 1, 2015, Dean Corporation signed a ten-year noncancelable lease for certain machinery. The terms of the lease called for Dean to make annual payments of $150,000 at the end of each year for ten years with the title passing to Dean at the end of this period. The machinery has an estimated useful life of 15 years and no salvage value. Dean uses the straight-line method of depreciation for all of its fixed assets. Dean accordingly accounted for this lease transaction as a capital lease. The lease payments were determined to have a present value of $1,006,512 at an effective interest rate of 8%. With respect to this capitalized lease, Dean should record for 2015
(Multiple Choice)
4.9/5 (69)
(69) Pye Company leased equipment to the Polan Company on July 1, 2015, for a ten-year period expiring June 30, 2025. Equal annual payments under the lease are $160,000 and are due on July 1 of each year. The first payment was made on July 1, 2015. The rate of interest contemplated by Pye and Polan is 9%. The cash selling price of the equipment is $1,120,000 and the cost of the equipment on Pye's accounting records was $992,000. Assuming that the lease is appropriately recorded as a sale for accounting purposes by Pye, what is the amount of profit on the sale and the interest revenue that Pye would record for the year ended December 31, 2015?
(Multiple Choice)
4.9/5 (71)
(71) Use the following information for questions 75 through 80. (Annuity tables on page 21-25.)
Alt Corporation enters into an agreement with Yates Rentals Co. on January 1, 2015 for the purpose of leasing a machine to be used in its manufacturing operations. The following data pertain to the agreement:
(a) The term of the noncancelable lease is 3 years with no renewal option. Payments of $287,432 are due on January 1 of each year.
(b) The fair value of the machine on January 1, 2015, is $800,000. The machine has a remaining economic life of 10 years, with no salvage value. The machine reverts to the lessor upon the termination of the lease.
(c) Alt depreciates all machinery it owns on a straight-line basis.
(d) Alt's incremental borrowing rate is 10% per year. Alt does not have knowledge of the 8% implicit rate used by Yates.
(e) Immediately after signing the lease, Yates finds out that Alt Corp. is the defendant in a suit which is sufficiently material to make collectibility of future lease payments doubtful.
-If the present value of the future lease payments is $800,000 at January 1, 2015, what is the amount of the reduction in the lease liability for Alt Corp. in the second full year of the lease if Alt Corp. accounts for the lease as a capital lease? (Rounded to the nearest dollar.)
(Multiple Choice)
4.8/5 (71)
(71) Which of the following is a correct statement of one of the capitalization criteria?
(Multiple Choice)
4.8/5 (74)
(74) Pisa, Inc. leased equipment from Tower Company under a four-year lease requiring equal annual payments of $172,076, with the first payment due at lease inception. The lease does not transfer ownership, nor is there a bargain purchase option. The equipment has a 4-year useful life and no salvage value. If Pisa, Inc.'s incremental borrowing rate is 10% and the rate implicit in the lease (which is known by Pisa, Inc.) is 8%, what is the amount recorded for the leased asset at the lease inception? 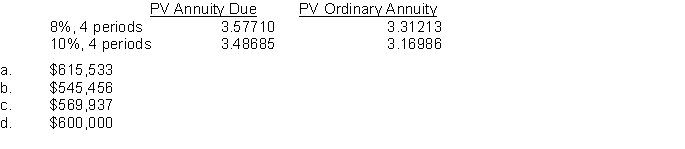
(Short Answer)
4.8/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)