



 Chat with AI
Exam 8: Perfect Competition

Exam 1: Introducing the Economic Way of Thinking251 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth202 Questions
Exam 3: Market Demand and Supply412 Questions
Exam 4: Markets in Action253 Questions
Exam 5: Price Elasticity of Demand and Supply280 Questions
Exam 6: Consumer Choice Theory272 Questions
Exam 7: Production Costs243 Questions
Exam 8: Perfect Competition237 Questions
Exam 9: Monopoly168 Questions
Exam 10: Monopolistic Competition and Oligopoly187 Questions
Exam 11: Labor Markets202 Questions
Exam 12: Income Distribution, Poverty, and Discrimination130 Questions
Exam 13: Antitrust and Regulation203 Questions
Exam 14: Environmental Economics106 Questions
Exam 15: International Trade and Finance241 Questions
Exam 16: Economies in Transition108 Questions
Exam 17: Growth and the117 Questions
Select questions type


In long-run equilibrium, the typical perfectly competitive firm will:
(Multiple Choice)
5.0/5  (88)
(88) A portrait photographer produces output in packages of 100 photos each. If the output sold increases from 600 to 700 photos, total revenue increases from $1,200 to $1,400. The marginal revenue per photo is:
(Multiple Choice)
4.9/5 (83)
(83) In long-run equilibrium, which of the following is not equal to price for a perfectly competitive firm?
(Multiple Choice)
4.8/5 (71)
(71) Assume that a firm's marginal revenue just barely exceeds marginal cost. Under these conditions the firm should:
(Multiple Choice)
4.9/5 (77)
(77) Suppose product price is fixed at $24; MR = MC at Q = 200; AFC = $6; AVC = $25. What do you advise this firm to do?
(Multiple Choice)
5.0/5 (72)
(72) If the market price is $5 and you are currently producing at a level where average total cost is $3 and falling, you should:
(Multiple Choice)
5.0/5 (94)
(94) Suppose a company increases production from a point where marginal cost equals average total cost to a point where marginal revenue and marginal cost are equal. Is it a good idea for the company to do this? Why?
(Multiple Choice)
4.9/5 (88)
(88) In a perfectly competitive industry, assume the short-run average total cost increases as the output of the industry expands. In the long run, the industry supply curve will:
(Multiple Choice)
4.8/5 (83)
(83) Competitive firms frequently use advertising to differentiate their product from their competitors' products.
(True/False)
4.8/5 (75)
(75) A perfectly competitive firm's short-run supply curve is the:
(Multiple Choice)
4.8/5 (75)
(75) Suppose that price is below the minimum average total cost (ATC) but above the minimum average variable cost (AVC), and the market price is expected to rise at least to ATC in the near future. In the short run, a firm that is a price taker would:
(Multiple Choice)
4.9/5 (71)
(71) Under perfect competition, a firm is a price taker because:
(Multiple Choice)
4.9/5 (78)
(78) Exhibit 8-19 Long-run perfectly competitive industry 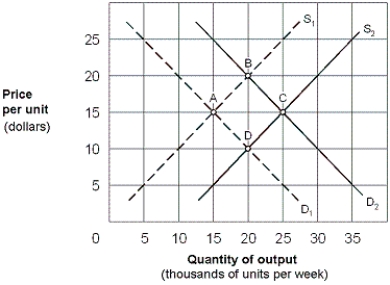 -As shown in Exhibit 8-19, assume that a perfectly competitive industry is in long-run equilibrium at point A. If the demand curve shifts from D1 to D2, the adjustment sequence between points will be:
 (Multiple Choice)
4.9/5 (83)
(83) Exhibit 8-4 Marginal cost and revenue for a firm Unit Quantity Marginal Cost Marginal Revenue 12 \ 5 \ 9 13 6 9 14 7 9 15 8 9 16 9 9 17 10 9
-In Exhibit 8-4, what is this firm's profit-maximizing rate of output?
(Multiple Choice)
4.9/5 (75)
(75) Assume the short-run average total cost for a perfectly competitive industry remains constant as the output of the industry expands. In the long run, the industry supply curve will:
(Multiple Choice)
4.9/5 (78)
(78) Exhibit 8-13 Price and cost per unit curves 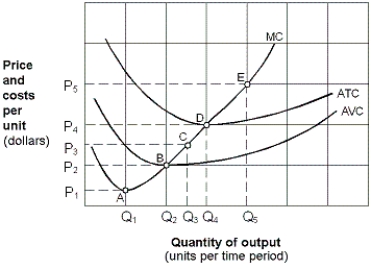 -In Exhibit 8-13, the firm will not produce when the price is between:
 (Multiple Choice)
4.9/5 (96)
(96) The long-run equilibrium condition for perfect competition is:
(Multiple Choice)
4.7/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)