



 Chat with AI
Exam 8: Perfect Competition

Exam 1: Introducing the Economic Way of Thinking251 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth202 Questions
Exam 3: Market Demand and Supply412 Questions
Exam 4: Markets in Action253 Questions
Exam 5: Price Elasticity of Demand and Supply280 Questions
Exam 6: Consumer Choice Theory272 Questions
Exam 7: Production Costs243 Questions
Exam 8: Perfect Competition237 Questions
Exam 9: Monopoly168 Questions
Exam 10: Monopolistic Competition and Oligopoly187 Questions
Exam 11: Labor Markets202 Questions
Exam 12: Income Distribution, Poverty, and Discrimination130 Questions
Exam 13: Antitrust and Regulation203 Questions
Exam 14: Environmental Economics106 Questions
Exam 15: International Trade and Finance241 Questions
Exam 16: Economies in Transition108 Questions
Exam 17: Growth and the117 Questions
Select questions type


If resource prices rise and the per-unit cost of producing a product increases as the firms in an industry expand output in response to an increase in demand, the long-run market supply curve for the product will:
(Multiple Choice)
4.8/5  (94)
(94) A perfectly competitive firm sells its output for $100 per unit and marginal cost is $100 per unit. To maximize short-run profit, the firm should:
(Multiple Choice)
5.0/5 (67)
(67) Exhibit 8-5 A firm's MR and MC curves 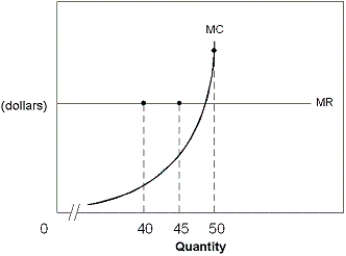 -In Exhibit 8-5, suppose a firm is currently producing 45 units of output. What would you advise this firm to do?
 (Multiple Choice)
4.9/5 (85)
(85) As the electronic components industry expands, the salaries paid to electrical engineers rise in response to higher demand. We can conclude that the electronic components industry is:
(Multiple Choice)
4.8/5 (79)
(79) Suppose that you have returned from your fishing expedition with 20,000 fish. The market price is $3 per fish. Your average fixed cost was $1 and your total variable cost was $5,000. If the price jumps to $3.50 before you sell your first fish, how much extra profit, if any, do you earn?
(Multiple Choice)
4.9/5 (77)
(77) A perfectly competitive firm's short-run supply curve is the:
(Multiple Choice)
4.8/5 (76)
(76) Consider a firm with the following cost information: ATC = $15, AVC = $12, and MC = $14. If we know that this firm has decided to produce Q = 20 by following the rule to maximize profits or minimize losses, then the price of the output is:
(Multiple Choice)
4.9/5 (70)
(70) Which of the following is characteristic of a perfectly competitive market?
(Multiple Choice)
4.9/5 (65)
(65) Assume the short-run average total cost for a perfectly competitive industry increases as the output of the industry expands. In the long run, the industry supply curve will:
(Multiple Choice)
4.8/5 (86)
(86) Exhibit 8-17 Marginal revenue and cost per unit curves 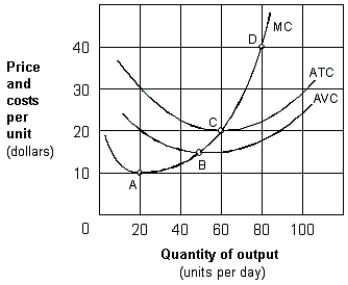 -If the price of the firm's product in Exhibit 8-17 is $15 per unit, the firm should:
 (Multiple Choice)
4.8/5 (86)
(86) If ABC Printing is producing an output level of 100, where MR is $5 and MC is $3, then the firm is:
(Multiple Choice)
4.8/5 (83)
(83) Exhibit 8-12 Marginal revenue and cost per unit curves 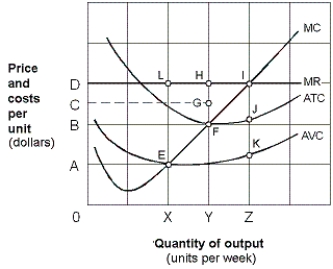 -As shown in Exhibit 8-12, the firm will not produce in the short-run if the price is below:
 (Multiple Choice)
4.7/5 (70)
(70) A firm is currently operating where the MC of the last unit produced = $84, and the MR of this unit = $70. What would you advise this firm to do?
(Multiple Choice)
4.7/5 (87)
(87) Exhibit 8-11 A firm's cost and marginal revenue curves 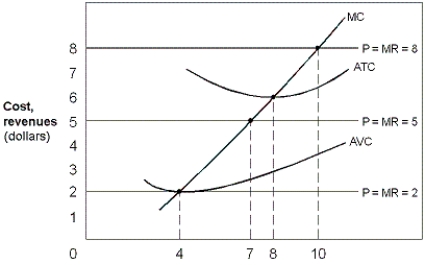 -In Exhibit 8-11, when the price is $2, the profit-maximizing (or loss-minimizing) firm:
 (Multiple Choice)
4.9/5 (75)
(75) Exhibit 8-6 A firm's cost and MC curves 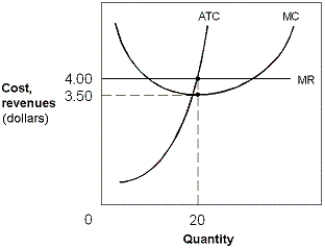 -In Exhibit 8-6, if this firm is currently producing 20 units of output, this firm:
 (Multiple Choice)
4.8/5 (92)
(92) Exhibit 8-1 Quantity and total revenue data for a firm Quantity Total Revenue 0 \ 0 1 62 2 124 3 186
-Exhibit 8-1 indicates that this firm is operating in which type of market structure?
(Multiple Choice)
4.7/5 (87)
(87) In long-run equilibrium, a perfectly competitive firm's short-run marginal cost curve crosses the long-run average cost curve at the lowest point on the long-run average cost curve.
(True/False)
4.8/5 (89)
(89) If the expansion of output in an industry leads to unchanged resource prices, the industry is most likely to be a(n):
(Multiple Choice)
4.8/5 (94)
(94) A perfectly competitive firm maximizes profits or minimizes losses in the short-run by producing at the output level at which:
(Multiple Choice)
4.7/5 (56)
(56) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)