



 Chat with AI
Exam 10: Monopolistic Competition and Oligopoly

Exam 1: Introducing the Economic Way of Thinking251 Questions
Exam 2: Production Possibilities, Opportunity Cost, and Economic Growth202 Questions
Exam 3: Market Demand and Supply412 Questions
Exam 4: Markets in Action253 Questions
Exam 5: Price Elasticity of Demand and Supply280 Questions
Exam 6: Consumer Choice Theory272 Questions
Exam 7: Production Costs243 Questions
Exam 8: Perfect Competition237 Questions
Exam 9: Monopoly168 Questions
Exam 10: Monopolistic Competition and Oligopoly187 Questions
Exam 11: Labor Markets202 Questions
Exam 12: Income Distribution, Poverty, and Discrimination130 Questions
Exam 13: Antitrust and Regulation203 Questions
Exam 14: Environmental Economics106 Questions
Exam 15: International Trade and Finance241 Questions
Exam 16: Economies in Transition108 Questions
Exam 17: Growth and the117 Questions
Select questions type


Which of the following is the best example of a firm operating in a monopolistically competitive market?
(Multiple Choice)
4.8/5  (77)
(77) In the short run, the monopolistic competitive firm will charge a price equal to marginal cost.
(True/False)
4.9/5 (79)
(79) As new firms enter a monopolistic competitive industry, it can be expected that:
(Multiple Choice)
4.8/5 (84)
(84) Compared to monopoly, the market results with monopolistic competition are usually expected to be:
(Multiple Choice)
4.8/5 (81)
(81) Which of the following is a game theory strategy for oligopolists to avoid a low-price outcome?
(Multiple Choice)
4.8/5 (90)
(90) Exhibit 10-2 A monopolistic competitive firm  -As presented in Exhibit 10-2, the long-run profit-maximizing output for the monopolistic competitive firm is:
 (Multiple Choice)
4.9/5 (73)
(73) Which of the following is true about advertising by a firm?
(Multiple Choice)
5.0/5 (87)
(87) A monopolistic competitive firm is inefficient because the firm:
(Multiple Choice)
5.0/5 (73)
(73) Exhibit 10-5 Two-Firm Payoff Matrix 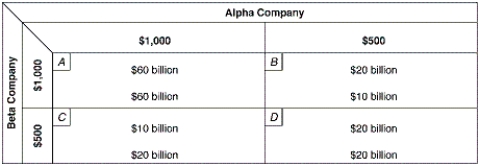 -Suppose costs are identical for the two firms in Exhibit 10-5. Each firm assumes without formal agreement that if it sets the high price its rival will not charge a lower price. Under these "tit-for-tat" conditions, equilibrium will be established by:
 (Multiple Choice)
4.9/5 (85)
(85) Which of the following statements best describes firms under monopolistic competition?
(Multiple Choice)
4.9/5 (85)
(85) Tombstones are produced in a monopolistic competitive market. One producer, Rolling Stones, sells 20 tombstones a week at a price of $500 each. Its average total cost is $600. From this information, we can tell:
(Multiple Choice)
4.9/5 (80)
(80) Cartel members have an incentive to cheat on the cartel because:
(Multiple Choice)
4.7/5 (88)
(88) Which of the following is true for a firm operating under perfect competition, monopolistic competition, and monopoly?
(Multiple Choice)
4.8/5 (86)
(86) Exhibit 10-4 Kinked demand curves 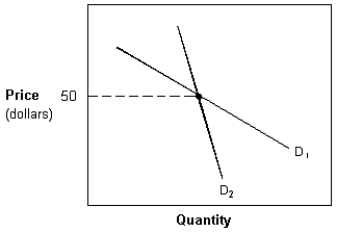 -In Exhibit 10-4, the exhibit represents a kinked-demand oligopoly model. Suppose the current price is $50. If one firm in the oligopoly now attempts to lower price, all firms will:
 (Multiple Choice)
4.7/5 (69)
(69) When Pepsi is considering a price hike, it needs to consider how Coke may react. This situation is called:
(Multiple Choice)
4.8/5 (68)
(68) The theory of monopolistic competition predicts that in long-run equilibrium a monopolistically competitive firm will:
(Multiple Choice)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)