



 Chat with AI
Exam 13: Accounting for Merchandise Inventory

Exam 1: Introduction to Accounting50 Questions
Exam 2: Analyzing Transactions: the Accounting Equation57 Questions
Exam 3: The Double-Entry Framework78 Questions
Exam 4: Journalizing and Posting Transactions94 Questions
Exam 5: Adjusting Entries and the Work Sheet101 Questions
Exam 6: Financial Statements and the Closing Process92 Questions
Exam 7: Accounting for Cash93 Questions
Exam 8: Payroll Accounting: Employee Earnings and Deductions85 Questions
Exam 9: Payroll Accounting: Employer Taxes and Reports79 Questions
Exam 10: Accounting for Sales and Cash Receipts66 Questions
Exam 11: Accounting for Purchases and Cash Payments79 Questions
Exam 12: Special Journals56 Questions
Exam 13: Accounting for Merchandise Inventory87 Questions
Exam 14: Adjustments and the Work Sheet for a Merchandising Business70 Questions
Exam 15: Financial Statements and Year-End Accounting for a Merchandising Business96 Questions
Exam 16: Accounting for Accounts Receivable77 Questions
Exam 17: Accounting for Notes and Interest97 Questions
Exam 18: Accounting for Long-Term Assets103 Questions
Exam 19: Accounting for Partnerships77 Questions
Exam 20: Corporations: Organization and Capital Stocks105 Questions
Exam 21: Corporations: Earnings, Taxes, Distributions, and the Retained Earnings Statement92 Questions
Exam 22: Corporations: Bonds98 Questions
Exam 23: Statement of Cash Flows102 Questions
Exam 24: Analysis of Financial Statements101 Questions
Exam 25: Departmental Accounting72 Questions
Exam 26: Manufacturing Accounting: The Job Order Cost System97 Questions
Exam 27: Manufacturing Accounting: The Work Sheet and Financial Statements66 Questions
Select questions type


The following data applies to a particular item of merchandise: On hand at start of period 300 \ 5.10 purchase 500 5.20 purchase 700 5.30 purchase 600 5.50 Number of units available for sale 2,100 On hand at end of period Number of units sold during period ? Of the 1,600 units sold during the period, 300 were from the beginning inventory; 500 from the first purchase; 600 from the second purchase; and 200 from the last purchase. Using the specific identification costing method, the value of inventory on hand at the end of the period would be
(Multiple Choice)
5.0/5  (69)
(69) The increasing use of computers and optical scanning devices at the point-of-sale probably will cause more businesses to switch from periodic to perpetual inventories.
(True/False)
4.9/5 (83)
(83) Match the terms with the definitions.
-The accounting practice that states that we should never anticipate gains, but always anticipate and account for losses.
(Multiple Choice)
4.9/5 (91)
(91) The April 1 inventory of Inotech Inc. had a cost of $35,505 and had a retail value of $79,000. During April, merchandise was purchased for $125,000 and marked to sell for $262,500. April sales totaled $201,000.
Required:
Calculate the following items using the retail method of inventory estimation. 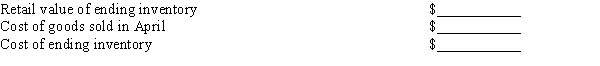
(Essay)
4.9/5 (72)
(72) If merchandise is shipped FOB destination, the merchandise is the property of the selling company until it is received by the buying company.
(True/False)
5.0/5 (76)
(76) When prices are rising, net income calculated by using the last-in, first-out method is smaller than the amount determined from using either the first-in, first-out or the weighted-average method.
(True/False)
5.0/5 (88)
(88) Last-in, first-out costing matches the most current cost of items purchased against the current sales revenue.
(True/False)
4.9/5 (70)
(70) The inventory system whereby the merchandise inventory account balance is merely a record of the most recent physical inventory count is called
(Multiple Choice)
4.8/5 (92)
(92) If market value is less than cost, the difference between the cost and market value of inventory is considered a loss due to holding inventory and should be reported on the income statement as an expense.
(True/False)
4.9/5 (71)
(71) The "FIFO" and "LIFO" inventory costing methods are based on assumed cost flows that are not required to reflect the actual physical movement of merchandise within the company.
(True/False)
4.8/5 (69)
(69) The principle of conservatism states that gains should not be anticipated but that all potential losses should be recognized.
(True/False)
4.8/5 (82)
(82) Match the terms with the definitions.
-A method of allocating merchandise cost which assumes that the first goods purchased were the first goods sold and, therefore, that the latest goods purchased remain in inventory.
(Multiple Choice)
4.8/5 (91)
(91) Match the terms with the definitions.
-A method of allocating merchandise cost in which each unit of inventory is recognized at its purchase price.
(Multiple Choice)
4.9/5 (71)
(71) Under conditions of rising prices, the FIFO inventory method provides the highest gross profit because the most recent purchase costs are matched against sales revenue.
(True/False)
4.8/5 (81)
(81) Assigning of the lower-of-cost-or-market to the items that comprise the inventory of merchandise at the end of the account period is an application of which of the following concepts?
(Multiple Choice)
4.8/5 (84)
(84) Delmar Industries uses the perpetual inventory method in accounting for inventory. Prepare the necessary adjusting entry for each of the following independent cases using the cost of goods sold account. 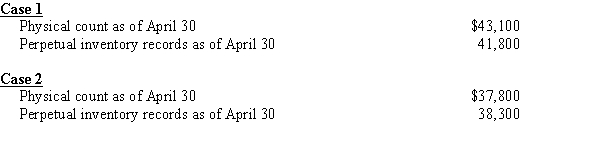
(Essay)
4.7/5 (93)
(93) If a difference is found between the physical count and the amount in the perpetual inventory records, the records must be corrected by an appropriate adjusting entry.
(True/False)
4.9/5 (81)
(81) Match the terms with the definitions.
-A variation of the gross profit method that is used by many retail businesses, to estimate the cost of goods sold and ending inventory.
(Multiple Choice)
4.8/5 (68)
(68) When merchandise is acquired on account and the perpetual system of inventory is used, the journal entry for the purchase would include
(Multiple Choice)
5.0/5 (76)
(76) An error in the reported inventory will cause errors in all of the following EXCEPT
(Multiple Choice)
4.9/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)