



 Chat with AI
Exam 19: Family Tax Planning

Exam 1: Understanding and Working With the Federal Tax Law71 Questions
Exam 2: Corporations: Introduction and Operating Rules94 Questions
Exam 3: Corporations: Special Situations99 Questions
Exam 4: Corporations: Organization and Capital Structure84 Questions
Exam 5: Corporations: Earnings Profits and Dividend Distributions114 Questions
Exam 6: Corporations: Redemptions and Liquidations88 Questions
Exam 7: Corporations: Reorganizations86 Questions
Exam 8: Consolidated Tax Returns138 Questions
Exam 9: Taxation of International Transactions163 Questions
Exam 10: Partnerships: Formation, Operation, and Basis122 Questions
Exam 11: Partnerships: Distributions, Transfer of Interests, and Terminations128 Questions
Exam 12: S Corporations135 Questions
Exam 13: Comparative Forms of Doing Business108 Questions
Exam 14: Taxes on the Financial Statements55 Questions
Exam 15: Exempt Entities100 Questions
Exam 16: Multistate Corporate Taxation123 Questions
Exam 17: Tax Practice and Ethics129 Questions
Exam 18: The Federal Gift and Estate Taxes188 Questions
Exam 19: Family Tax Planning145 Questions
Exam 20: Income Taxation of Trusts and Estates136 Questions
Select questions type


Match each statement with the correct choice. Some choices may be used more than once or not used at all
-Doubles the number of annual exclusions available.
(Multiple Choice)
4.9/5  (80)
(80) Match each statement with the correct choice. Some choices may be used more than once or not used at all
-Valuation of life estate interest created by transfer in trust.
(Multiple Choice)
4.9/5 (88)
(88) Match each statement with the correct choice. Some choices may be used more than once or not used at all
-Valuation of a life insurance policy that is not paid up.
(Multiple Choice)
4.8/5 (79)
(79) Match each statement with the correct choice. Some choices may be used more than once or not used at all
-Decedent owned stock that had depreciated in value.
(Multiple Choice)
4.8/5 (82)
(82) Harvey owns a certificate of deposit listed as: "Harvey, payable on proof of death to April." On Harvey's prior death, the CD is not subject to probate.
(True/False)
4.9/5 (72)
(72) Jim makes a gift of property (basis of $800,000; fair market value of $600,000) to his wife, Molly. Six months later Molly dies, and under her will, the property (now worth $700,000) returns to Jim. Jim's income tax basis in the property now is $800,000.
(True/False)
4.8/5 (66)
(66) Match each statement with the correct choice. Some choices may be used more than once or not used at all
-Decedent owned traditional IRA that has appreciated.
(Multiple Choice)
4.9/5 (82)
(82) Match each statement with the correct choice. Some choices may be used more than once or not used at all
-Valuation of a commercial annuity contract.
(Multiple Choice)
4.8/5 (87)
(87) Natalie creates a trust, income payable to Ava (age 12) for 10 years, remainder to Samantha (age 32). In determining the value of these two gifts (i.e., income interest for a term certain and a remainder interest), use of more than one IRS valuation table will be necessary.
(True/False)
4.9/5 (85)
(85) Under proper circumstances, a disclaimer by an heir may increase the charitable deduction allowed a decedent.
(True/False)
4.8/5 (73)
(73) A recapture of special use valuation will occur even if a qualified heir ceases to use the property for farming purposes but does not otherwise dispose of it.
(True/False)
4.9/5 (80)
(80) Liam and Isla are husband and wife and have always lived in a community property state. At the time of Isla's prior death, part of their community property includes: 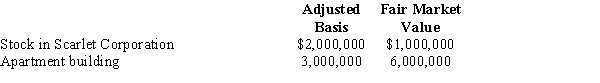 Under Isla's will, all of her property passes to Liam. After Isla's death, Liam's income tax basis in this property is:
 (Multiple Choice)
5.0/5 (77)
(77) Several years ago, Tad purchased land listing ownership as "Tad, Ellen, and Kay, equal tenants in common." In the current year, Kay dies first. One-third of the value of the land is included in Kay's probate estate.
(True/False)
4.9/5 (92)
(92) Describe the various tax advantages that are available from donating a conservation easement to charity.
(Essay)
4.9/5 (81)
(81) Two years ago, Ellen created a revocable trust-life estate to her children, remainder to her grandchildren. When Ellen dies in the current year, none of the trust is included in her gross estate or her probate estate.
(True/False)
4.7/5 (87)
(87) Andrew makes a gift of securities (basis of $1,100,000; fair market value of $800,000) to his son, Carl. As a result of the transfer, Andrew paid a gift tax of $80,000. What is Carl's income tax basis in the securities if the gift occurred in 2015?
(Essay)
4.8/5 (81)
(81) In January 2015 and when the annual exclusion was $14,000, Clint makes a gift of his beach house (basis of $114,000; fair market value of $414,000) to his aunt. As a result of the transfer, Clint pays a gift tax of $20,000. The aunt dies in December 2015, when the property is worth $420,000. Under the terms of the aunt's will, the property passes to Clint. Clint's income tax basis in the beach house is:
(Multiple Choice)
4.8/5 (74)
(74) Dustin owns all of the stock of Gold Corporation which includes both common and preferred shares. The preferred stock is noncumulative, has no redemption date, and possesses no liquidation preference. In 1995, Dustin makes a gift to his adult children of all of the common stock. He dies in 2015 still owning the preferred stock. The value of the Gold stock on the relevant dates is: 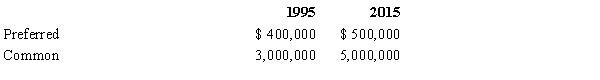 One of the tax consequences of this estate freeze is:
 (Multiple Choice)
4.9/5 (84)
(84) A decedent owned 25% of the voting stock of Siskin Corporation. Siskin has 53 shareholders. The decedent's estate cannot qualify for the § 6166 election.
(True/False)
4.9/5 (80)
(80) In satisfying the more-than-35% test for qualification under § 6166, interests in multiple closely held businesses are aggregated when the decedent's gross estate includes 20% or more of the value of each such business.
(True/False)
4.8/5 (72)
(72) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)