



 Chat with AI
Exam 13: Financing the Deal

Exam 1: Introduction to Mergers, Acquisitions, and Other Restructuring Activities139 Questions
Exam 2: The Regulatory Environment129 Questions
Exam 3: The Corporate Takeover Market:152 Questions
Exam 4: Planning: Developing Business and Acquisition Plans: Phases 1 and 2 of the Acquisition Process137 Questions
Exam 5: Implementation: Search Through Closing: Phases 310 of the Acquisition Process131 Questions
Exam 6: Postclosing Integration: Mergers, Acquisitions, and Business Alliances138 Questions
Exam 7: Merger and Acquisition Cash Flow Valuation Basics108 Questions
Exam 8: Relative, Asset-Oriented, and Real Option109 Questions
Exam 9: Financial Modeling Basics:97 Questions
Exam 10: Analysis and Valuation127 Questions
Exam 11: Structuring the Deal:138 Questions
Exam 12: Structuring the Deal:125 Questions
Exam 13: Financing the Deal149 Questions
Exam 14: Applying Financial Modeling116 Questions
Exam 15: Business Alliances: Joint Ventures, Partnerships, Strategic Alliances, and Licensing138 Questions
Exam 16: Alternative Exit and Restructuring Strategies152 Questions
Exam 17: Alternative Exit and Restructuring Strategies:118 Questions
Exam 18: Cross-Border Mergers and Acquisitions:120 Questions
Select questions type


Divisions of larger companies are generally poor candidates for successful leveraged buyouts.
(True/False)
4.8/5  (85)
(85) How will the investors be able to recover the 20% purchase price premium?
(Essay)
5.0/5 (83)
(83) Case Study Short Essay Examination Questions
Hollywood’s Biggest Independent Studios Combine in a Leveraged Buyout
LBOs allow buyouts using relatively little cash and often rely heavily on the target firm’s assets to finance the transaction.
Private equity investors often “cash out” of their investments by selling to a strategic buyer.
______________________________________________________________________________
The Lionsgate-Summit tie-up represented the culmination of more than four years of intermittent discussions between the two firms. The number of studios making and releasing movies has been shrinking amid falling DVD sales and continued efforts to transition to digital distribution. As the largest independent studios in Hollywood, both firms saw their cash flow whipsawed as one blockbuster hit would be followed by a series of failures. Film and TV program libraries offered the only source of cash flow stability due to the recurring fees paid by those licensing the rights to use this proprietary content.
Lionsgate first approached Summit about a buyout in 2008 in an effort to bolster its film and TV library. However, it was not until early 2012 that the two sides could reach agreement. The time was ripe because Summit’s investors were looking for a way to cash in on the success of the firm’s Twilight movies series. Consisting of four films, this series had grossed $2.5 billion worldwide. On February 2, 2012, Lionsgate announced that it had reached an agreement to acquire Summit Entertainment by paying Summit shareholders $412.5 million in cash and stock for all of their outstanding shares and assumed debt of $506.3 million. According to the merger agreement, Lionsgate would provide administrative, production, and distribution services to Summit for a 10% servicing fee. Layoffs are expected at both firms as they merge redundant departments in their film operations, such as marketing, production, and distribution. The acquisition provides a windfall to Summit’s investors, including eBay cofounder Jeff Skoll’s film company Media and private equity fund Traverse Management. These investors had previously received a $200 million dividend as part of a recapitalization in early 2011 and gained handsomely from the sale to Lionsgate.
Lionsgate is a diversified film and television production and distribution company, with a film library of 13,000 titles. The firm’s major distribution channels include home entertainment and prepackaged media (DVDs); digital distribution (on-demand TV) and pay TV (premium network programming). Summit, also a producer and distributor of film and TV content, has a less consistent track record in realizing successful releases, with the Twilight “franchise” its primary success. However, Summit does have strong international licensing operations, with arrangements in the United States, Canada, Germany, France, Scandinavia, Spain, and Australia. The acquisition also strengthens Lionsgate’s position as a leading content supplier and, controlling the Twilight and Hunger Games franchises, positions Lionsgate as a market leader for young adult audiences. The combination also results in cost and revenue synergies, more diversified cash flow streams, and greater access to international distribution channels.
Figure 13.3 illustrates the subsidiary structure for completing the buyout of Summit Entertainment LLC. As is typical of such transactions, Lionsgate created a merger subsidiary (Merger Sub) and funded the subsidiary with its equity contribution of $100 million in cash and $69 million in Lionsgate stock, receiving 100% of the subsidiary’s stock in exchange. Merger Sub was further capitalized by a bank term loan of $500 million. Following a tender offer to Summit’s shareholders by Merger Sub, Merger Sub was merged into Summit Entertainment, with Summit surviving as a wholly owned subsidiary of Lionsgate in a reverse triangular merger. At closing, $284.4 million of Summit’s excess cash was used to finance the total cost of the deal.
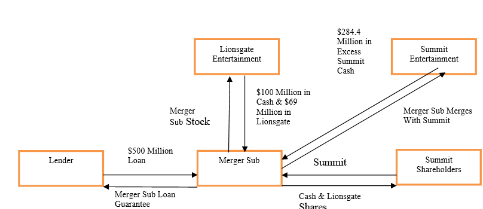 Lionsgate-Summit Legal and Financing Structure.
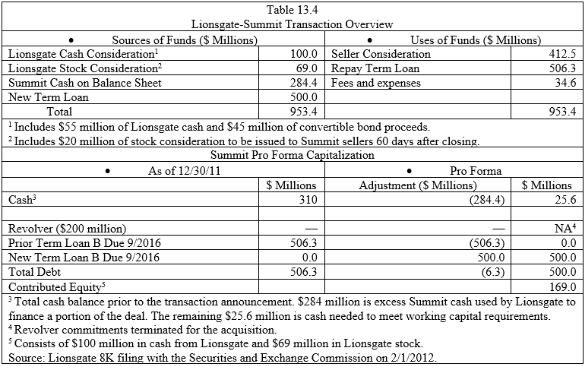
Table 13.4 summarizes the sources of financing for the buyout and shows how these funds were used to pay for the deal. Lionsgate financed the total cost of the deal of $953.4 million (consisting of $412.5 million for Summit stock + the pretransaction term loan of $506.3 million + $34.6 million in transaction-related fees and expenses) as follows: $100 million in cash from Lionsgate and $69 million in Lionsgate stock + $284.4 million of the $310 million in cash on Summit’s balance sheet at closing + a new $500 million term loan. Summit’s $506.3 million term loan B was refinanced with the new term loan for $500 million as part of the transaction. The new term loan is an obligation of and is secured by the assets of Summit and its subsidiaries. It also is secured by a loan guarantee provided by Merger Sub, created by Lionsgate to consummate the transaction. The guarantee is secured by the equity in Summit held by Merger Sub. Lionsgate anticipates paying off the term loan well in advance of its 2016 maturity date out of future cash flows from new movie releases. Summit’s pretransaction net debt was $196.3 million (pretransaction term loan of $506.3 less total cash on the balance sheet of $310 million). Postclosing net debt increased to $474.4 million (postclosing term loan of $500 million less $25.6 million in total cash of the balance sheet).
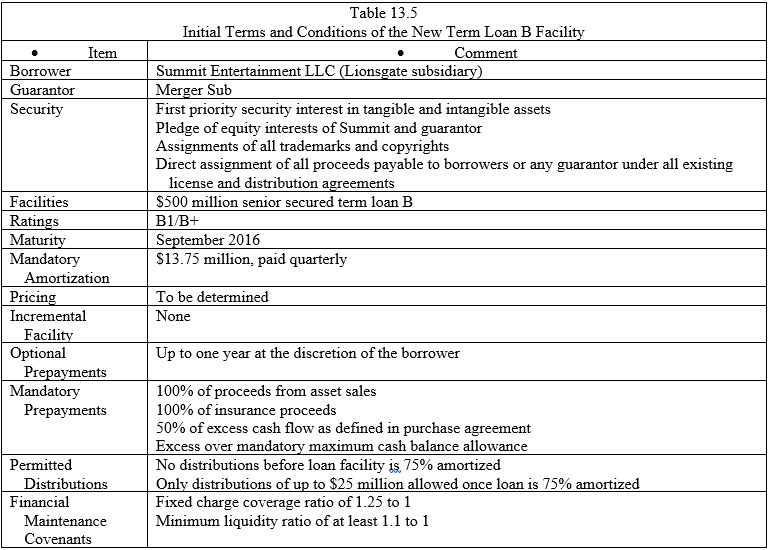
 presents the key features of the new term loan B facility. Note how Summit’s assets are used as collateral to secure the loan. In addition, the lender has first priority on the proceeds from certain types of transactions, giving them priority access to such funds. Cash distributions are not possible until the loan is almost paid off, and even then the size of such distributions is limited. Finally, loan covenants require Summit to maintain a comparatively liquid position during the term of the loan.
 -How are $34.6 million in fees and expenses associated with the transaction paid for? Be specific.
Lionsgate-Summit Legal and Financing Structure.
Table 13.4 summarizes the sources of financing for the buyout and shows how these funds were used to pay for the deal. Lionsgate financed the total cost of the deal of $953.4 million (consisting of $412.5 million for Summit stock + the pretransaction term loan of $506.3 million + $34.6 million in transaction-related fees and expenses) as follows: $100 million in cash from Lionsgate and $69 million in Lionsgate stock + $284.4 million of the $310 million in cash on Summit’s balance sheet at closing + a new $500 million term loan. Summit’s $506.3 million term loan B was refinanced with the new term loan for $500 million as part of the transaction. The new term loan is an obligation of and is secured by the assets of Summit and its subsidiaries. It also is secured by a loan guarantee provided by Merger Sub, created by Lionsgate to consummate the transaction. The guarantee is secured by the equity in Summit held by Merger Sub. Lionsgate anticipates paying off the term loan well in advance of its 2016 maturity date out of future cash flows from new movie releases. Summit’s pretransaction net debt was $196.3 million (pretransaction term loan of $506.3 less total cash on the balance sheet of $310 million). Postclosing net debt increased to $474.4 million (postclosing term loan of $500 million less $25.6 million in total cash of the balance sheet).
presents the key features of the new term loan B facility. Note how Summit’s assets are used as collateral to secure the loan. In addition, the lender has first priority on the proceeds from certain types of transactions, giving them priority access to such funds. Cash distributions are not possible until the loan is almost paid off, and even then the size of such distributions is limited. Finally, loan covenants require Summit to maintain a comparatively liquid position during the term of the loan.
-How are $34.6 million in fees and expenses associated with the transaction paid for? Be specific. (Essay)
4.8/5 (67)
(67) RJR NABISCO GOES PRIVATE-
KEY SHAREHOLDER AND PUBLIC POLICY ISSUES
Background
The largest LBO in history is as well known for its theatrics as it is for its substantial improvement in shareholder value. In October 1988, H. Ross Johnson, then CEO of RJR Nabisco, proposed an MBO of the firm at $75 per share. His failure to inform the RJR board before publicly announcing his plans alienated many of the directors. Analysts outside the company placed the breakup value of RJR Nabisco at more than $100 per share-almost twice its then current share price. Johnson's bid immediately was countered by a bid by the well-known LBO firm, Kohlberg, Kravis, and Roberts (KKR), to buy the firm for $90 per share (Wasserstein, 1998). The firm's board immediately was faced with the dilemma of whether to accept the KKR offer or to consider some other form of restructuring of the company. The board appointed a committee of outside directors to assess the bid to minimize the appearance of a potential conflict of interest in having current board members, who were also part of the buyout proposal from management, vote on which bid to select.
The bidding war soon escalated with additional bids coming from Forstmann Little and First Boston, although the latter's bid never really was taken very seriously. Forstmann Little later dropped out of the bidding as the purchase price rose. Although the firm's investment bankers valued both the bids by Johnson and KKR at about the same level, the board ultimately accepted the KKR bid. The winning bid was set at almost $25 billion-the largest transaction on record at that time and the largest LBO in history. Banks provided about three-fourths of the $20 billion that was borrowed to complete the transaction. The remaining debt was supplied by junk bond financing. The RJR shareholders were the real winners, because the final purchase price constituted a more than 100% return from the $56 per share price that existed just before the initial bid by RJR management.
Aggressive pricing actions by such competitors as Phillip Morris threatened to erode RJR Nabisco's ability to service its debt. Complex securities such as "increasing rate notes," whose coupon rates had to be periodically reset to ensure that these notes would trade at face value, ultimately forced the credit rating agencies to downgrade the RJR Nabisco debt. As market interest rates climbed, RJR Nabisco did not appear to have sufficient cash to accommodate the additional interest expense on the increasing return notes. To avoid default, KKR recapitalized the company by investing additional equity capital and divesting more than $5 billion worth of businesses in 1990 to help reduce its crushing debt load. In 1991, RJR went public by issuing more than $1 billion in new common stock, which placed about one-fourth of the firm's common stock in public hands.
When KKR eventually fully liquidated its position in RJR Nabisco in 1995, it did so for a far smaller profit than expected. KKR earned a profit of about $60 million on an equity investment of $3.1 billion. KKR had not done well for the outside investors who had financed more than 90% of the total equity investment in KKR. However, KKR fared much better than investors had in its LBO funds by earning more than $500 million in transaction fees, advisor fees, management fees, and directors' fees. The publicity surrounding the transaction did not cease with the closing of the transaction. Dissident bondholders filed suits alleging that the payment of such a large premium for the company represented a "confiscation" of bondholder wealth by shareholders.
Potential Conflicts of Interest
In any MBO, management is confronted by a potential conflict of interest. Their fiduciary responsibility to the shareholders is to take actions to maximize shareholder value; yet in the RJR Nabisco case, the management bid appeared to be well below what was in the best interests of shareholders. Several proposals have been made to minimize the potential for conflict of interest in the case of an MBO, including that directors, who are part of an MBO effort, not be allowed to participate in voting on bids, that fairness opinions be solicited from independent financial advisors, and that a firm receiving an MBO proposal be required to hold an auction for the firm.
The most contentious discussion immediately following the closing of the RJR Nabisco buyout centered on the alleged transfer of wealth from bond and preferred stockholders to common stockholders when a premium was paid for the shares held by RJR Nabisco common stockholders. It often is argued that at least some part of the premium is offset by a reduction in the value of the firm's outstanding bonds and preferred stock because of the substantial increase in leverage that takes place in LBOs.
Winners and Losers
RJR Nabisco shareholders before the buyout clearly benefited greatly from efforts to take the company private. However, in addition to the potential transfer of wealth from bondholders to stockholders, some critics of LBOs argue that a wealth transfer also takes place in LBO transactions when LBO management is able to negotiate wage and benefit concessions from current employee unions. LBOs are under greater pressure to seek such concessions than other types of buyouts because they need to meet huge debt service requirements.
-What were the RJR Nabisco board's fiduciary responsibilities to the shareholders? How well did they satisfy these responsibilities? What could/should they have done differently?
(Essay)
4.9/5 (81)
(81) TXU Goes Private in the Largest Private Equity Transaction in History-The Dark Side of Leverage
Key Points
The 2007/2008 financial crisis left many LBOs excessively leveraged.
As structured, the TXU buyout (now Energy Future Holdings) left no margin for error.
Excessive leverage severely limits the firm's future financial options.
_____________________________________________________________________________
Before the buyout, TXU, a Dallas-based energy giant, was a highly profitable utility. Historically low interest rates and an overly optimistic outlook for natural gas prices set the stage for the largest private equity deal in history. The 2007 buyout of TXU was valued at $48 billion and, at the time, appeared to offer such promise that several of Wall Street's largest lenders --including the likes of Lehman Brothers and Citigroup-invested, along with such storied names in private equity as KKR, TPG, and Goldman Sachs. However, the price of gas plummeted, eroding TXU's cash flow. Since the deal closed in October 2007, investors who bought $40 billion of TXU's debt have experienced losses as high as 70% to 80% of their value. The other $8 billion used to finance the deal came from the private equity investors, banks, and large institutional investors. They, too, have suffered huge losses. Having met its obligations to date, the firm faces a $20 billion debt repayment coming due in 2014.
Wall Street banks were competing in 2007 to make loans to buyout firms on easier terms, with the banks also investing their own funds in the deal. The allure to the banks was the prospect of dividing up as much as $1.1 billion in fees for originating the loans, repackaging such loans into pools called collateralized loan obligations, and reselling them to long-term investors such as pension funds and insurance companies. In doing so, the loans would be removed from the banks' balance sheets, eliminating potential losses that could arise if the deal soured at a later date. Furthermore, the deal appeared to be attractive as an investment opportunity because some banks put up $500 million of their own cash for a stake in TXU.
The financial sponsor group, consisting of Kohlberg Kravis Roberts & Co, Texas Pacific Group, and Goldman Sachs, created a shell corporation, referred to as Merger Sub Parent, and its wholly owned subsidiary Merger Sub. TXU was merged into Merger Sub, with Merger Sub surviving. Each outstanding share of TXU common stock was converted into the right to receive $69.25 in cash. Total cash required for the purchase was provided by the financial sponsor group and lenders (Creditor Group) to Merger Sub. Regulatory authorities required that the debt associated with the transaction be held at the level of the Merger Sub Parent holding company so as not to leverage the utility further.
Subsequent to closing, the new company was reorganized into independent businesses under a new holding company, controlled by the Sponsor Group, called Texas Holdings (TH). Merger Sub (which owns TXU) was renamed Energy Future Holdings. TH's direct subsidiaries are EFH and Oncor (an energy distribution business formerly held by TXU). EFH's primary direct subsidiary is Texas Competitive Electric Holdings, which holds TXU's public utility operating assets and liabilities. All TXU non-Sponsor Group-related debt incurred to finance the transaction is held by EFH, while any debt incurred by the Sponsor Group is shown on the TH balance sheet. This legal structure allows for the concentration of debt in TH and EFH, separate from the cash-generating assets held by Oncor and Texas Competitive Electric Holdings.
Loan covenants limit EFH's and its subsidiaries' ability to issue new debt or preferred stock; pay dividends on, repurchase, or make distributions of capital stock or make other restricted payments; make investments; sell or transfer assets; consolidate, merge, sell, or dispose of all or substantially all its assets; and repay, repurchase, or modify debt. A breach of any of these covenants could result in default. Table 13.6 illustrates selected covenants in which certain ratios must be maintained either above or below stipulated thresholds. Note that EFH was in violation of certain covenants when you compare actual December 31, 2009 (the last year for which public information is available), ratios with required threshold levels.
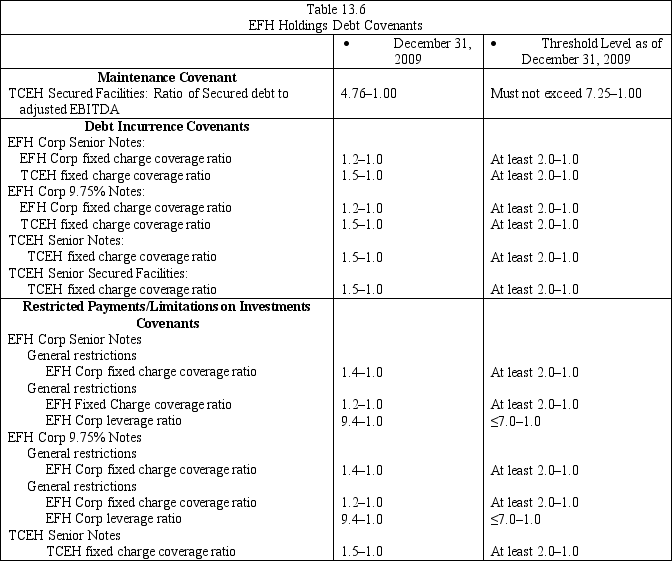 -December 31, 2009
-Threshold Level as of December 31, 2009
Things clearly have not turned out as expected. The firm faces an almost-untenable capital structure. The firm's debt traded at between 20 and 30 cents on the dollar throughout most of 2012. The $8 billion equity invested in the deal has been virtually wiped out on paper. Absent a turnaround in natural gas prices, EFH is left with seeking a way to reduce substantially the burden of the pending 2014 $20 billion loan payment with its lenders through a debt-for-equity swap or more favorable terms on existing debt or by pursuing Chapter 11 bankruptcy. EFH has posted eight consecutive quarterly losses. In December 2012, in an effort to extend debt maturities to buy time for a turnaround and to reduce interest expense, EFH exchanged $1.15 billion of new payment-in-kind notes (interest is paid with more debt) for existing notes with a face value of $1.6 billion. By any measure, this transaction illustrates the dark side of leverage.
-As CEO of EFH, would you recommend to the board of directors as an appropriate strategy for paying the $20 billion in debt that is maturing in 2014?
-December 31, 2009
-Threshold Level as of December 31, 2009
Things clearly have not turned out as expected. The firm faces an almost-untenable capital structure. The firm's debt traded at between 20 and 30 cents on the dollar throughout most of 2012. The $8 billion equity invested in the deal has been virtually wiped out on paper. Absent a turnaround in natural gas prices, EFH is left with seeking a way to reduce substantially the burden of the pending 2014 $20 billion loan payment with its lenders through a debt-for-equity swap or more favorable terms on existing debt or by pursuing Chapter 11 bankruptcy. EFH has posted eight consecutive quarterly losses. In December 2012, in an effort to extend debt maturities to buy time for a turnaround and to reduce interest expense, EFH exchanged $1.15 billion of new payment-in-kind notes (interest is paid with more debt) for existing notes with a face value of $1.6 billion. By any measure, this transaction illustrates the dark side of leverage.
-As CEO of EFH, would you recommend to the board of directors as an appropriate strategy for paying the $20 billion in debt that is maturing in 2014? (Essay)
4.9/5 (74)
(74) Pacific Investors Acquires California Kool in a Leveraged Buyout
Pacific Investors (PI) is a small private equity limited partnership with $3 billion under management. The objective of the fund is to give investors at least a 30-percent annual average return on their investment by judiciously investing these funds in highly leveraged transactions. PI has been able to realize such returns over the last decade because of its focus on investing in industries that have slow but predictable growth in cash flow, modest capital investment requirements, and relatively low levels of research and development spending. In the past, PI made several lucrative investments in the contract packaging industry, which provides packaging for beverage companies that produce various types of noncarbonated and carbonated beverages. Because of its commitments to its investors, PI likes to liquidate its investments within four to six years of the initial investment through a secondary public offering or sale to a strategic investor.
Following its past success in the industry, PI currently is negotiating with California Kool (CK), a privately owned contract beverage packaging company with the technology required to package many types of noncarbonated drinks. CK's 2003 revenue and net income are $190.4 million and $5.9 million, respectively. With a reputation for effective management, CK is a medium-sized contract packaging company that owns its own plant and equipment and has a history of continually increasing cash flow. The company also has significant unused excess capacity, suggesting that production levels can be increased without substantial new capital spending.
The owners of CK are demanding a purchase price of $70 million. This is denoted on the balance sheet (see Table 13-15 at the end of the case) as a negative entry in additional paid-in capital. This price represents a multiple of 11.8 times 2003's net income, almost twice the multiple for comparable publicly traded companies. Despite the "rich" multiple, PI believes that it can finance the transaction through an equity investment of $25 million and $47 million in debt. The equity investment consists of $3 million in common stock, with PI's investors and CK's management each contributing $1.5 million. Debt consists of a $12 million revolving loan to meet immediate working capital requirements, $20 million in senior bank debt secured by CK's fixed assets, and $15 million in a subordinated loan from a pension fund. The total cost of acquiring CK is $72 million, $70 million paid to the owners of CK and $2 million in legal and accounting fees.
As indicated on Table 13-15, the change in total liabilities plus shareholders' equity (i.e., total sources of funds or cash inflows) must equal the change in total assets (i.e., total uses of funds or cash outflows). Therefore, as shown in the adjustments column, total liabilities increase by $47 million in total borrowings and shareholders' equity declines by $45 million (i.e., $25 million in preferred and common equity provided by investors less $70 million paid to CK owners). The excess of sources over uses of $2 million is used to finance legal and accounting fees incurred in closing the transaction. Consequently, total assets increase by $2 million and total liabilities plus shareholders' equity increase by $2 million between the pre- and postclosing balance sheets as shown in the adjustments column.hasi1 Delta;Total assets = ΔTotal liabilities + ΔShareholders' equity: $2 million = $47 million -$45 million = $2 million.
Revenue for CK is projected to grow at 4.5 percent annually through the foreseeable future. Operating expenses and sales, general, and administrative expenses as a percent of sales are expected to decline during the first three years of operation due to aggressive cost cutting and the introduction of new management and engineering processes. Similarly, improved working capital management results in significant declines in working capital as a percent of sales during the first year of operation. Gross fixed assets as percent of sales is held constant at its 2003 level during the forecast period, reflecting reinvestment requirements to support the projected increase in net revenue. Equity cash flow adjusted to include cash generated in excess of normal operating requirements (i.e., denoted by the change in investments available for sale) is expected to reach $8.5 million annually by 2010. Using the cost of capital method, the cost of equity declines in line with the reduction in the firm's beta as the debt is repaid from 26 percent in 2004 to 16.5 percent in 2010. In contrast, the adjusted present value method employs a constant unlevered COE of 17 percent.
The deal would appear to make sense from the standpoint of PI, since the projected average annual internal rates of return (IRRs) for investors exceed PI's minimum desired 30 percent rate of return in all scenarios considered between 2007 and 2009 (see Table 13-13). This is the period during which investors would like to "cash out." The rates of return scenarios are calculated assuming the business can be sold at different multiples of adjusted equity cash flow in the year in which the business is assumed to be sold. Consequently, IRRs are calculated using the cash outflow (initial equity investment in the business) in the first year offset by any positive equity cash flow from operations generated in the first year, equity cash flows for each subsequent year, and the sum of equity cash flow in the year in which the business is sold or taken public plus the estimated sale value (e.g., eight times equity cash flow) in that year. Adjusted equity cash flow includes free cash flow generated from operations and the increase in "investments available for sale." Such investments represent cash generated in excess of normal operating requirements; and as such, this cash is available to LBO investors.
The actual point at which CK would either be taken public, sold to a strategic investor, or sold to another LBO fund depends on stock market conditions, CK's leverage relative to similar firms in the industry, and cash flow performance as compared to the plan. Discounted cash flow analysis also suggests that PI should do the deal, since the total present value of adjusted equity cash flow of $57.2 million using the CC method is more than twice the magnitude of the initial equity investment. At $56 million, the APV method results in a slightly lower estimate of total present value. See Tables 13-14,13-15, and 13-16 for the income, balance-sheet, and cash-flow statements, respectively, associated with this transaction. Exhibits 13-1 and 13-2 illustrate the calculation of present value of the transaction based on the cost of capital and the adjusted present value methods, respectively. Note the actual Excel spreadsheets and formulas used to create these financial tables are available on the CD-ROM accompanying this book in a worksheet, Excel-Based Leveraged Buyout Valuation and Structuring Model.
-What are the advantages and disadvantages of using enterprise cash flow in valuing CK? In what might EBITDA been a superior (inferior) measure of cash flow for valuing CK?
(Essay)
4.9/5 (83)
(83) Financing Challenges in the Home Depot Supply Transaction
Buyout firms Bain Capital, Carlyle Group, and Clayton, Dubilier & Rice (CD&R) bid $10.3 billion in June 2007 to buy Home Depot Inc.'s HD Supply business. HD Supply represented a collection of small suppliers of construction products. Home Depot had announced earlier in the year that it planned to use the proceeds of the sale to pay for a portion of a $22.5 billion stock buyback.
Three banks, Lehman Brothers, JPMorgan Chase, and Merril Lynch agreed to provide the firms with a $4 billion loan. The repayment of the loans was predicated on the ability of the buyout firms to improve significantly HD Supply's current cash flow. Such loans are normally made with the presumption that they can be sold to investors, with the banks collecting fees from both the borrower and investor groups. However, by July, concern about the credit quality of subprime mortgages spread to the broader debt market and raised questions about the potential for default of loans made to finance highly leveraged transactions. The concern was particularly great for so-called "covenant-lite" loans for which the repayment terms were very lenient.
Fearing they would not be able to resell such loans to investors, the three banks involved in financing the HD Supply transaction wanted more financial protection. Additional protection, they reasoned, would make such loans more marketable to investors. They used the upheaval in the credit markets as a pretext for reopening negotiations on their previous financing commitments. Home Depot was willing to lower the selling price thereby reducing the amount of financing required by the buyout firms and was willing to guarantee payment in the event of default by the buyout firms. While Bain, Carlyle, and CD&R were willing to increase their cash investment and pay higher fees to the banks, they were unwilling to alter the original terms of the loans. Eventually the banks agreed to provide financing consisting of a $1 billion "covenant-lite" loan and a $1.3 billion "payment-in-kind" loan. Home Depot agreed to assume the loan payments on the $1 billion loan if the investor firms were to default and to lower the selling price to $8.5 billion for 87.5 percent of HD Supply, with Home Depot retaining the remaining 12.5 percent.
By the end of August, Home Depot had succeeded in raising the cash needed to help pay for its share repurchase, and the banks had reduced their original commitment of $4 billion in loans to $2.3 billion. While they had agreed to put more money into the transaction, the buyout firms had been successful in limiting the number of new restrictive covenants.
-Based on the information given it the case, determine the amount of the price reduction Home Depot accepted for HD Supply and the amount of cash the three buyout firms put into the transaction?
(Essay)
4.7/5 (97)
(97) How was ownership transferred in this deal? Speculate as to why this structure may have been used?
(Essay)
4.8/5 (79)
(79) Pacific Investors Acquires California Kool in a Leveraged Buyout
Pacific Investors (PI) is a small private equity limited partnership with $3 billion under management. The objective of the fund is to give investors at least a 30-percent annual average return on their investment by judiciously investing these funds in highly leveraged transactions. PI has been able to realize such returns over the last decade because of its focus on investing in industries that have slow but predictable growth in cash flow, modest capital investment requirements, and relatively low levels of research and development spending. In the past, PI made several lucrative investments in the contract packaging industry, which provides packaging for beverage companies that produce various types of noncarbonated and carbonated beverages. Because of its commitments to its investors, PI likes to liquidate its investments within four to six years of the initial investment through a secondary public offering or sale to a strategic investor.
Following its past success in the industry, PI currently is negotiating with California Kool (CK), a privately owned contract beverage packaging company with the technology required to package many types of noncarbonated drinks. CK's 2003 revenue and net income are $190.4 million and $5.9 million, respectively. With a reputation for effective management, CK is a medium-sized contract packaging company that owns its own plant and equipment and has a history of continually increasing cash flow. The company also has significant unused excess capacity, suggesting that production levels can be increased without substantial new capital spending.
The owners of CK are demanding a purchase price of $70 million. This is denoted on the balance sheet (see Table 13-15 at the end of the case) as a negative entry in additional paid-in capital. This price represents a multiple of 11.8 times 2003's net income, almost twice the multiple for comparable publicly traded companies. Despite the "rich" multiple, PI believes that it can finance the transaction through an equity investment of $25 million and $47 million in debt. The equity investment consists of $3 million in common stock, with PI's investors and CK's management each contributing $1.5 million. Debt consists of a $12 million revolving loan to meet immediate working capital requirements, $20 million in senior bank debt secured by CK's fixed assets, and $15 million in a subordinated loan from a pension fund. The total cost of acquiring CK is $72 million, $70 million paid to the owners of CK and $2 million in legal and accounting fees.
As indicated on Table 13-15, the change in total liabilities plus shareholders' equity (i.e., total sources of funds or cash inflows) must equal the change in total assets (i.e., total uses of funds or cash outflows). Therefore, as shown in the adjustments column, total liabilities increase by $47 million in total borrowings and shareholders' equity declines by $45 million (i.e., $25 million in preferred and common equity provided by investors less $70 million paid to CK owners). The excess of sources over uses of $2 million is used to finance legal and accounting fees incurred in closing the transaction. Consequently, total assets increase by $2 million and total liabilities plus shareholders' equity increase by $2 million between the pre- and postclosing balance sheets as shown in the adjustments column.hasi1 Delta;Total assets = ΔTotal liabilities + ΔShareholders' equity: $2 million = $47 million -$45 million = $2 million.
Revenue for CK is projected to grow at 4.5 percent annually through the foreseeable future. Operating expenses and sales, general, and administrative expenses as a percent of sales are expected to decline during the first three years of operation due to aggressive cost cutting and the introduction of new management and engineering processes. Similarly, improved working capital management results in significant declines in working capital as a percent of sales during the first year of operation. Gross fixed assets as percent of sales is held constant at its 2003 level during the forecast period, reflecting reinvestment requirements to support the projected increase in net revenue. Equity cash flow adjusted to include cash generated in excess of normal operating requirements (i.e., denoted by the change in investments available for sale) is expected to reach $8.5 million annually by 2010. Using the cost of capital method, the cost of equity declines in line with the reduction in the firm's beta as the debt is repaid from 26 percent in 2004 to 16.5 percent in 2010. In contrast, the adjusted present value method employs a constant unlevered COE of 17 percent.
The deal would appear to make sense from the standpoint of PI, since the projected average annual internal rates of return (IRRs) for investors exceed PI's minimum desired 30 percent rate of return in all scenarios considered between 2007 and 2009 (see Table 13-13). This is the period during which investors would like to "cash out." The rates of return scenarios are calculated assuming the business can be sold at different multiples of adjusted equity cash flow in the year in which the business is assumed to be sold. Consequently, IRRs are calculated using the cash outflow (initial equity investment in the business) in the first year offset by any positive equity cash flow from operations generated in the first year, equity cash flows for each subsequent year, and the sum of equity cash flow in the year in which the business is sold or taken public plus the estimated sale value (e.g., eight times equity cash flow) in that year. Adjusted equity cash flow includes free cash flow generated from operations and the increase in "investments available for sale." Such investments represent cash generated in excess of normal operating requirements; and as such, this cash is available to LBO investors.
The actual point at which CK would either be taken public, sold to a strategic investor, or sold to another LBO fund depends on stock market conditions, CK's leverage relative to similar firms in the industry, and cash flow performance as compared to the plan. Discounted cash flow analysis also suggests that PI should do the deal, since the total present value of adjusted equity cash flow of $57.2 million using the CC method is more than twice the magnitude of the initial equity investment. At $56 million, the APV method results in a slightly lower estimate of total present value. See Tables 13-14,13-15, and 13-16 for the income, balance-sheet, and cash-flow statements, respectively, associated with this transaction. Exhibits 13-1 and 13-2 illustrate the calculation of present value of the transaction based on the cost of capital and the adjusted present value methods, respectively. Note the actual Excel spreadsheets and formulas used to create these financial tables are available on the CD-ROM accompanying this book in a worksheet, Excel-Based Leveraged Buyout Valuation and Structuring Model.
-Compare and contrast the Cost of Capital Method and the Adjusted Present Value Method of valuation.
(Essay)
4.9/5 (82)
(82) RJR NABISCO GOES PRIVATE-
KEY SHAREHOLDER AND PUBLIC POLICY ISSUES
Background
The largest LBO in history is as well known for its theatrics as it is for its substantial improvement in shareholder value. In October 1988, H. Ross Johnson, then CEO of RJR Nabisco, proposed an MBO of the firm at $75 per share. His failure to inform the RJR board before publicly announcing his plans alienated many of the directors. Analysts outside the company placed the breakup value of RJR Nabisco at more than $100 per share-almost twice its then current share price. Johnson's bid immediately was countered by a bid by the well-known LBO firm, Kohlberg, Kravis, and Roberts (KKR), to buy the firm for $90 per share (Wasserstein, 1998). The firm's board immediately was faced with the dilemma of whether to accept the KKR offer or to consider some other form of restructuring of the company. The board appointed a committee of outside directors to assess the bid to minimize the appearance of a potential conflict of interest in having current board members, who were also part of the buyout proposal from management, vote on which bid to select.
The bidding war soon escalated with additional bids coming from Forstmann Little and First Boston, although the latter's bid never really was taken very seriously. Forstmann Little later dropped out of the bidding as the purchase price rose. Although the firm's investment bankers valued both the bids by Johnson and KKR at about the same level, the board ultimately accepted the KKR bid. The winning bid was set at almost $25 billion-the largest transaction on record at that time and the largest LBO in history. Banks provided about three-fourths of the $20 billion that was borrowed to complete the transaction. The remaining debt was supplied by junk bond financing. The RJR shareholders were the real winners, because the final purchase price constituted a more than 100% return from the $56 per share price that existed just before the initial bid by RJR management.
Aggressive pricing actions by such competitors as Phillip Morris threatened to erode RJR Nabisco's ability to service its debt. Complex securities such as "increasing rate notes," whose coupon rates had to be periodically reset to ensure that these notes would trade at face value, ultimately forced the credit rating agencies to downgrade the RJR Nabisco debt. As market interest rates climbed, RJR Nabisco did not appear to have sufficient cash to accommodate the additional interest expense on the increasing return notes. To avoid default, KKR recapitalized the company by investing additional equity capital and divesting more than $5 billion worth of businesses in 1990 to help reduce its crushing debt load. In 1991, RJR went public by issuing more than $1 billion in new common stock, which placed about one-fourth of the firm's common stock in public hands.
When KKR eventually fully liquidated its position in RJR Nabisco in 1995, it did so for a far smaller profit than expected. KKR earned a profit of about $60 million on an equity investment of $3.1 billion. KKR had not done well for the outside investors who had financed more than 90% of the total equity investment in KKR. However, KKR fared much better than investors had in its LBO funds by earning more than $500 million in transaction fees, advisor fees, management fees, and directors' fees. The publicity surrounding the transaction did not cease with the closing of the transaction. Dissident bondholders filed suits alleging that the payment of such a large premium for the company represented a "confiscation" of bondholder wealth by shareholders.
Potential Conflicts of Interest
In any MBO, management is confronted by a potential conflict of interest. Their fiduciary responsibility to the shareholders is to take actions to maximize shareholder value; yet in the RJR Nabisco case, the management bid appeared to be well below what was in the best interests of shareholders. Several proposals have been made to minimize the potential for conflict of interest in the case of an MBO, including that directors, who are part of an MBO effort, not be allowed to participate in voting on bids, that fairness opinions be solicited from independent financial advisors, and that a firm receiving an MBO proposal be required to hold an auction for the firm.
The most contentious discussion immediately following the closing of the RJR Nabisco buyout centered on the alleged transfer of wealth from bond and preferred stockholders to common stockholders when a premium was paid for the shares held by RJR Nabisco common stockholders. It often is argued that at least some part of the premium is offset by a reduction in the value of the firm's outstanding bonds and preferred stock because of the substantial increase in leverage that takes place in LBOs.
Winners and Losers
RJR Nabisco shareholders before the buyout clearly benefited greatly from efforts to take the company private. However, in addition to the potential transfer of wealth from bondholders to stockholders, some critics of LBOs argue that a wealth transfer also takes place in LBO transactions when LBO management is able to negotiate wage and benefit concessions from current employee unions. LBOs are under greater pressure to seek such concessions than other types of buyouts because they need to meet huge debt service requirements.
-Why might the RJR Nabisco board have accepted the KKR bid over the Johnson bid?
(Essay)
4.8/5 (72)
(72) The price reduction amounted to $600 million (i.e., $10.3 -$8.5/(1.00-.125) = $10.3 – 9.7 =$.6). The amount of cash invested in the transaction by the buyout firms totaled $6.2 billion ($8.5 -$2.3).
-Why did banks lower their lending standards in financing LBOs in 2006 and early 2007? How did the lax
standards contribute to their inability to sell the loans to investors? How did the inability to sell the loans once made curtail their future lending?
(Essay)
5.0/5 (101)
(101) Pacific Investors Acquires California Kool in a Leveraged Buyout
Pacific Investors (PI) is a small private equity limited partnership with $3 billion under management. The objective of the fund is to give investors at least a 30-percent annual average return on their investment by judiciously investing these funds in highly leveraged transactions. PI has been able to realize such returns over the last decade because of its focus on investing in industries that have slow but predictable growth in cash flow, modest capital investment requirements, and relatively low levels of research and development spending. In the past, PI made several lucrative investments in the contract packaging industry, which provides packaging for beverage companies that produce various types of noncarbonated and carbonated beverages. Because of its commitments to its investors, PI likes to liquidate its investments within four to six years of the initial investment through a secondary public offering or sale to a strategic investor.
Following its past success in the industry, PI currently is negotiating with California Kool (CK), a privately owned contract beverage packaging company with the technology required to package many types of noncarbonated drinks. CK's 2003 revenue and net income are $190.4 million and $5.9 million, respectively. With a reputation for effective management, CK is a medium-sized contract packaging company that owns its own plant and equipment and has a history of continually increasing cash flow. The company also has significant unused excess capacity, suggesting that production levels can be increased without substantial new capital spending.
The owners of CK are demanding a purchase price of $70 million. This is denoted on the balance sheet (see Table 13-15 at the end of the case) as a negative entry in additional paid-in capital. This price represents a multiple of 11.8 times 2003's net income, almost twice the multiple for comparable publicly traded companies. Despite the "rich" multiple, PI believes that it can finance the transaction through an equity investment of $25 million and $47 million in debt. The equity investment consists of $3 million in common stock, with PI's investors and CK's management each contributing $1.5 million. Debt consists of a $12 million revolving loan to meet immediate working capital requirements, $20 million in senior bank debt secured by CK's fixed assets, and $15 million in a subordinated loan from a pension fund. The total cost of acquiring CK is $72 million, $70 million paid to the owners of CK and $2 million in legal and accounting fees.
As indicated on Table 13-15, the change in total liabilities plus shareholders' equity (i.e., total sources of funds or cash inflows) must equal the change in total assets (i.e., total uses of funds or cash outflows). Therefore, as shown in the adjustments column, total liabilities increase by $47 million in total borrowings and shareholders' equity declines by $45 million (i.e., $25 million in preferred and common equity provided by investors less $70 million paid to CK owners). The excess of sources over uses of $2 million is used to finance legal and accounting fees incurred in closing the transaction. Consequently, total assets increase by $2 million and total liabilities plus shareholders' equity increase by $2 million between the pre- and postclosing balance sheets as shown in the adjustments column.hasi1 Delta;Total assets = ΔTotal liabilities + ΔShareholders' equity: $2 million = $47 million -$45 million = $2 million.
Revenue for CK is projected to grow at 4.5 percent annually through the foreseeable future. Operating expenses and sales, general, and administrative expenses as a percent of sales are expected to decline during the first three years of operation due to aggressive cost cutting and the introduction of new management and engineering processes. Similarly, improved working capital management results in significant declines in working capital as a percent of sales during the first year of operation. Gross fixed assets as percent of sales is held constant at its 2003 level during the forecast period, reflecting reinvestment requirements to support the projected increase in net revenue. Equity cash flow adjusted to include cash generated in excess of normal operating requirements (i.e., denoted by the change in investments available for sale) is expected to reach $8.5 million annually by 2010. Using the cost of capital method, the cost of equity declines in line with the reduction in the firm's beta as the debt is repaid from 26 percent in 2004 to 16.5 percent in 2010. In contrast, the adjusted present value method employs a constant unlevered COE of 17 percent.
The deal would appear to make sense from the standpoint of PI, since the projected average annual internal rates of return (IRRs) for investors exceed PI's minimum desired 30 percent rate of return in all scenarios considered between 2007 and 2009 (see Table 13-13). This is the period during which investors would like to "cash out." The rates of return scenarios are calculated assuming the business can be sold at different multiples of adjusted equity cash flow in the year in which the business is assumed to be sold. Consequently, IRRs are calculated using the cash outflow (initial equity investment in the business) in the first year offset by any positive equity cash flow from operations generated in the first year, equity cash flows for each subsequent year, and the sum of equity cash flow in the year in which the business is sold or taken public plus the estimated sale value (e.g., eight times equity cash flow) in that year. Adjusted equity cash flow includes free cash flow generated from operations and the increase in "investments available for sale." Such investments represent cash generated in excess of normal operating requirements; and as such, this cash is available to LBO investors.
The actual point at which CK would either be taken public, sold to a strategic investor, or sold to another LBO fund depends on stock market conditions, CK's leverage relative to similar firms in the industry, and cash flow performance as compared to the plan. Discounted cash flow analysis also suggests that PI should do the deal, since the total present value of adjusted equity cash flow of $57.2 million using the CC method is more than twice the magnitude of the initial equity investment. At $56 million, the APV method results in a slightly lower estimate of total present value. See Tables 13-14,13-15, and 13-16 for the income, balance-sheet, and cash-flow statements, respectively, associated with this transaction. Exhibits 13-1 and 13-2 illustrate the calculation of present value of the transaction based on the cost of capital and the adjusted present value methods, respectively. Note the actual Excel spreadsheets and formulas used to create these financial tables are available on the CD-ROM accompanying this book in a worksheet, Excel-Based Leveraged Buyout Valuation and Structuring Model.
-Describe how PI financed the purchase price. Speculate as why each source of financing was selected? How did CK pay for feels incurred in closing the transaction?
(Essay)
4.9/5 (73)
(73) Private equity investments are normally focused on the manufacturing industry.
(True/False)
4.8/5 (79)
(79) A common technique used during the 1990s was to wait for favorable periods in the stock market to sell a portion of the LBO's equity to the public. The proceeds of the issue would be used to repay debt, thereby reducing the LBO's financial risk.
(True/False)
4.9/5 (84)
(84) Fraudulent conveyance is best described by which of the following situations:
(Multiple Choice)
4.8/5 (82)
(82) With their cash hoards accumulating at an unprecedented rate, there was little that buyout firms could do but to invest in larger firms. Consequently, the average size of LBO transactions grew significantly during 2005. In a move reminiscent of the blockbuster buyouts of the late 1980s, seven private investment firms acquired 100 percent of the outstanding stock of SunGard Data Systems Inc. (SunGard) in late 2005. SunGard is a financial software firm known for providing application and transaction software services and creating backup data systems in the event of disaster. The company‘s software manages 70 percent of the transactions made on the Nasdaq stock exchange, but its biggest business is creating backup data systems in case a client’s main systems are disabled by a natural disaster, blackout, or terrorist attack. Its large client base for disaster recovery and back-up systems provides a substantial and predictable cash flow.
SunGard’s new owners include Silver lake Partners, Bain Capital LLC, The Blackstone Group L.P., Goldman Sachs Capital Partners, Kohlberg Kravis Roberts & Co., Providence Equity Partners Inc. and Texas Pacific Group. Buyout firms in 2005 tended to band together to spread the risk of a deal this size and to reduce the likelihood of a bidding war. Indeed, with SunGard, there was only one bidder, the investor group consisting of these seven firms.
The software side of SunGard is believed to have significant growth potential, while the disaster-recovery side provides a large stable cash flow. Unlike many LBOs, the deal was announced as being all about growth of the financial services software side of the business. The deal is structured as a merger, since SunGard would be merged into a shell corporation created by the investor group for acquiring SunGard. Going private, allows SunGard to invest heavily in software without being punished by investors, since such investments are expensed and reduce reported earnings per share. Going private also allows the firm to eliminate the burdensome reporting requirements of being a public company.
The buyout represented potentially a significant source of fee income for the investor group. In addition to the 2 percent management fees buyout firms collect from investors in the funds they manage, they receive substantial fee income from each investment they make on behalf of their funds. For example, the buyout firms receive a 1 percent deal completion fee, which is more than $100 million in the SunGard transaction. Buyout firms also receive fees paid for by the target firm that is “going private” for arranging financing. Moreover, there are also fees for conducting due diligence and for monitoring the ongoing performance of the firm taken private. Finally, when the buyout firms exit their investments in the target firm via a sale to a strategic buyer or a secondary IPO, they receive 20 percent (i.e., so-called carry fee) of any profits.
Under the terms of the agreement, SunGard shareholders received $36 per share, a 14 percent premium over the SunGard closing price as of the announcement date of March 28, 2005, and 40 percent more than when the news first leaked about the deal a week earlier. From the SunGard shareholders’ perspective, the deal is valued at $11.4 billion dollars consisting of $10.9 billion for outstanding shares and “in-the-money” options (i.e., options whose exercise price is less than the firm’s market price per share) plus $500 million in debt on the balance sheet.
The seven equity investors provided $3.5 billion in capital with the remainder of the purchase price financed by commitments from a lending consortium consisting of Citigroup, J.P. Morgan Chase & Co., and Deutsche Bank. The purpose of the loans is to finance the merger, repay or refinance SunGard’s existing debt, provide ongoing working capital, and pay fees and expenses incurred in connection with the merger. The total funds necessary to complete the merger and related fees and expenses is approximately $11.3 billion, consisting of approximately $10.9 billion to pay SunGard’s stockholders and about $400.7 million to pay fees and expenses related to the merger and the financing arrangements. Note that the fees that are to be financed comprise almost 4 percent of the purchase price. Ongoing working capital needs and capital expenditures required obtaining commitments from lenders well in excess of $11.3 billion.
The merger financing consists of several tiers of debt and “credit facilities.” Credit facilities are arrangements for extending credit. The senior secured debt and senior subordinated debt are intended to provide “permanent” or long-term financing. Senior debt covenants included restrictions on new borrowing, investments, sales of assets, mergers and consolidations, prepayments of subordinated indebtedness, capital expenditures, liens and dividends and other distributions, as well as a minimum interest coverage ratio and a maximum total leverage ratio.
If the offering of notes is not completed on or prior to the closing, the banks providing the financing have committed to provide up to $3 billion in loans under a senior subordinated bridge credit facility. The bridge loans are intended as a form of temporary financing to satisfy immediate cash requirements until permanent financing can be arranged. A special purpose SunGard subsidiary will purchase receivables from SunGard, with the purchases financed through the sale of the receivables to the lending consortium. The lenders subsequently finance the purchase of the receivables by issuing commercial paper, which is repaid as the receivables are collected. The special purpose subsidiary is not shown on the SunGard balance sheet. Based on the value of receivables at closing, the subsidiary could provide up to $500 million. The obligation of the lending consortium to buy the receivables will expire on the sixth anniversary of the closing of the merger.
The following table provides SunGard’s post-merger proforma capital structure. Note that the proforma capital structure is portrayed as if SunGard uses 100 percent of bank lending commitments. Also, note that individual LBO investors may invest monies from more than one fund they manage. This may be due to the perceived attractiveness of the opportunity or the limited availability of money in any single fund. Of the $9 billion in debt financing, bank loans constitute 56 percent and subordinated or mezzanine debt comprises represents 44 percent.
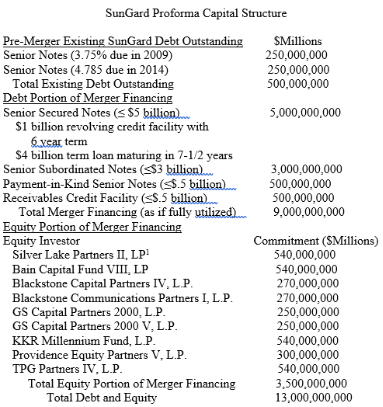 The roman numeral II refers to the fund providing the equity capital managed by the partnership
-Under what circumstances would SunGard refinance the existing $500 million in outstanding senior debt after the merger? Be specific.
The roman numeral II refers to the fund providing the equity capital managed by the partnership
-Under what circumstances would SunGard refinance the existing $500 million in outstanding senior debt after the merger? Be specific. (Essay)
4.8/5 (97)
(97) To avoid being subject to fraudulent conveyance laws, a properly structured LBO should have a balance sheet that clearly indicates solvency at the time of closing.
(True/False)
5.0/5 (82)
(82) Following Cox Enterprises' announcement on August 3, 2004 of its intent to buy the remaining 38% of Cox Communications' shares that they did not currently own, the Cox Communications Board of Directors formed a special committee of independent directors to consider the proposal. Why?
(Essay)
4.9/5 (78)
(78) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)