



 Chat with AI
Exam 13: Financing the Deal

Exam 1: Introduction to Mergers, Acquisitions, and Other Restructuring Activities139 Questions
Exam 2: The Regulatory Environment129 Questions
Exam 3: The Corporate Takeover Market:152 Questions
Exam 4: Planning: Developing Business and Acquisition Plans: Phases 1 and 2 of the Acquisition Process137 Questions
Exam 5: Implementation: Search Through Closing: Phases 310 of the Acquisition Process131 Questions
Exam 6: Postclosing Integration: Mergers, Acquisitions, and Business Alliances138 Questions
Exam 7: Merger and Acquisition Cash Flow Valuation Basics108 Questions
Exam 8: Relative, Asset-Oriented, and Real Option109 Questions
Exam 9: Financial Modeling Basics:97 Questions
Exam 10: Analysis and Valuation127 Questions
Exam 11: Structuring the Deal:138 Questions
Exam 12: Structuring the Deal:125 Questions
Exam 13: Financing the Deal149 Questions
Exam 14: Applying Financial Modeling116 Questions
Exam 15: Business Alliances: Joint Ventures, Partnerships, Strategic Alliances, and Licensing138 Questions
Exam 16: Alternative Exit and Restructuring Strategies152 Questions
Exam 17: Alternative Exit and Restructuring Strategies:118 Questions
Exam 18: Cross-Border Mergers and Acquisitions:120 Questions
Select questions type


Lessons from Pep Boys’ Aborted Attempt to Go Private
LBOs in recent years have involved financial sponsors’ providing a larger portion of the purchase price in cash than in the past.
Financial sponsors focus increasingly on targets in which they have previous or related experience.
Deals that would have been completed in the early 2000s are more likely to be terminated or subject to renegotiation than in the past.
_____________________________________________________________________________________
It ain’t over till it’s over” quipped former New York Yankees’ catcher Yogi Berra, famous for his malapropisms. The oft-quoted comment was once again proven true in Pep Boys’ unsuccessful attempt to go private in 2012. On May 30, 2012, after nearly two years of discussions between Pep Boys and several interested parties, the firm announced that a buyout agreement with the Gores Group (Gores), valued at approximately $1 billion (including assumed debt), had collapsed, a victim of Pep Boys’ declining operating performance. The firm’s shares fell 20% on the news to $8.89 per share, well below its level following the all-cash $15-a-share deal with Gores announced in January 2012. The terms of the transaction also included a termination fee if either party failed to complete the deal by July 27, 2012. The failed transaction illustrates the characteristics and potential pitfalls common to contemporary LBOs.
Pep Boys, a U.S. auto parts and repair business, operates more than 7,000 service bays in over 700 locations in 35 states and Puerto Rico. With its share price lagging the overall stock market in recent years, the firm’s board of directors explored a range of options for boosting the firm’s value and ultimately decided to put the firm up for sale. Gores was attracted initially by what appeared to be a low purchase price, stable cash flow, and the firm’s real estate holdings (many of the firm’s store sites are owned by the firm). Such assets could be used as collateral underlying loans to finance a portion of the purchase price. Furthermore, Gores has experience in retailing, having several retailers among their portfolio of companies, including J. Mendel and Mexx.
The transaction reflected a structure common for deals of this type. Pep Boys had entered into a merger agreement with Auto Acquisitions Group (the Parent), a shell corporation funded by cash provided by Gores as the financial sponsor, and the Parent’s wholly owned subsidiary (Merger Sub). The Parent would contribute cash to Merger Sub, with Merger Sub borrowing the remainder from several lenders. Merger Sub would subsequently buy Pep Boys’ outstanding shares and merge with the firm. Pep Boys would survive as a wholly owned subsidiary of the Parent. The purpose of this reverse triangular merger was to preserve the Pep Boys’ brand name and facilitate the transfer of supplier and customer contracts. The Parent also was to have been organized as a holding company to afford investors some degree of protection from Pep Boys’ liabilities. The purchase price was to have been financed by an equity contribution of $489 million from limited partnerships managed by Gores and the balance by loans provided by Barclays Bank PLC, Credit Suisse AG, and Wells Fargo Bank.
Upon learning that the Pep Boys’ reported earnings for the first quarter of 2012 would be well below expectations, Gores attempted to renegotiate the terms of the deal, arguing that Pep Boys had breached the deal’s agreements. With Pep Boys unwilling to accept a lower valuation, Gores exercised its right to terminate the deal by paying the $50 million breakup fee and agreed to reimburse Pep Boys for other costs it had incurred related to the deal. Pep Boys said the firm will use the proceeds of the breakup fee to refinance a portion of its outstanding debt.
"Grave Dancer" Takes Tribune Corporation Private in an Ill-Fated Transaction
At the closing in late December 2007, well-known real estate investor Sam Zell described the takeover of the Tribune Company as "the transaction from hell." His comments were prescient in that what had appeared to be a cleverly crafted, albeit highly leveraged, deal from a tax standpoint was unable to withstand the credit malaise of 2008. The end came swiftly when the 161-year-old Tribune filed for bankruptcy on December 8, 2008.
On April 2, 2007, the Tribune Corporation announced that the firm's publicly traded shares would be acquired in a multistage transaction valued at $8.2 billion. Tribune owned at that time 9 newspapers, 23 television stations, a 25% stake in Comcast's SportsNet Chicago, and the Chicago Cubs baseball team. Publishing accounts for 75% of the firm's total $5.5 billion annual revenue, with the remainder coming from broadcasting and entertainment. Advertising and circulation revenue had fallen by 9% at the firm's three largest newspapers (Los Angeles Times, Chicago Tribune, and Newsday in New York) between 2004 and 2006. Despite aggressive efforts to cut costs, Tribune's stock had fallen more than 30% since 2005.
The transaction was implemented in a two-stage transaction, in which Sam Zell acquired a controlling 51% interest in the first stage followed by a backend merger in the second stage in which the remaining outstanding Tribune shares were acquired. In the first stage, Tribune initiated a cash tender offer for 126 million shares (51% of total shares) for $34 per share, totaling $4.2 billion. The tender was financed using $250 million of the $315 million provided by Sam Zell in the form of subordinated debt, plus additional borrowing to cover the balance. Stage 2 was triggered when the deal received regulatory approval. During this stage, an employee stock ownership plan (ESOP) bought the rest of the shares at $34 a share (totaling about $4 billion), with Zell providing the remaining $65 million of his pledge. Most of the ESOP's 121 million shares purchased were financed by debt guaranteed by the firm on behalf of the ESOP. At that point, the ESOP held all of the remaining stock outstanding valued at about $4 billion. In exchange for his commitment of funds, Mr. Zell received a 15-year warrant to acquire 40% of the common stock (newly issued) at a price set at $500 million.
Following closing in December 2007, all company contributions to employee pension plans were funneled into the ESOP in the form of Tribune stock. Over time, the ESOP would hold all the stock. Furthermore, Tribune was converted from a C corporation to a Subchapter S corporation, allowing the firm to avoid corporate income taxes. However, it would have to pay taxes on gains resulting from the sale of assets held less than ten years after the conversion from a C to an S corporation (Figure 1).
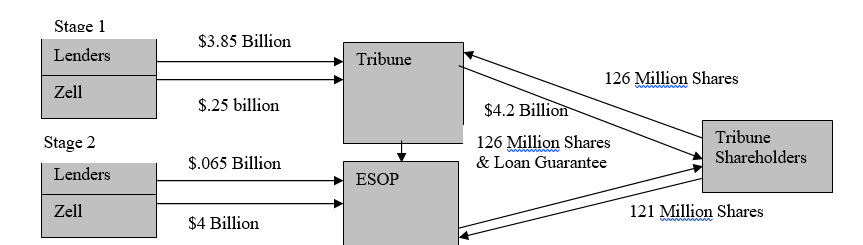 The purchase of Tribune's stock was financed almost entirely with debt, with Zell's equity contribution amounting to less than 4% of the purchase price. The transaction resulted in Tribune being burdened with $13 billion in debt (including the approximate $5 billion currently owed by Tribune). At this level, the firm's debt was ten times EBITDA, more than two and a half times that of the average media company. Annual interest and principal repayments reached $800 million (almost three times their preacquisition level), about 62% of the firm's previous EBITDA cash flow of $1.3 billion. While the ESOP owned the company, it was not be liable for the debt guaranteed by Tribune.
The conversion of Tribune into a Subchapter S corporation eliminated the firm's current annual tax liability of $348 million. Such entities pay no corporate income tax but must pay all profit directly to shareholders, who then pay taxes on these distributions. Since the ESOP was the sole shareholder, Tribune was expected to be largely tax exempt, since ESOPs are not taxed.
In an effort to reduce the firm's debt burden, the Tribune Company announced in early 2008 the formation of a partnership in which Cablevision Systems Corporation would own 97% of Newsday for $650 million, with Tribune owning the remaining 3%. However, Tribune was unable to sell the Chicago Cubs (which had been expected to fetch as much as $1 billion) and the minority interest in SportsNet Chicago to help reduce the debt amid the 2008 credit crisis. The worsening of the recession, accelerated by the decline in newspaper and TV advertising revenue, as well as newspaper circulation, thereby eroded the firm's ability to meet its debt obligations.
By filing for Chapter 11 bankruptcy protection, the Tribune Company sought a reprieve from its creditors while it attempted to restructure its business. Although the extent of the losses to employees, creditors, and other stakeholders is difficult to determine, some things are clear. Any pension funds set aside prior to the closing remain with the employees, but it is likely that equity contributions made to the ESOP on behalf of the employees since the closing would be lost. The employees would become general creditors of Tribune. As a holder of subordinated debt, Mr. Zell had priority over the employees if the firm was liquidated and the proceeds distributed to the creditors.
Those benefitting from the deal included Tribune's public shareholders, including the Chandler family, which owed 12% of Tribune as a result of its prior sale of the Times Mirror to Tribune, and Dennis FitzSimons, the firm's former CEO, who received $17.7 million in severance and $23.8 million for his holdings of Tribune shares. Citigroup and Merrill Lynch received $35.8 million and $37 million, respectively, in advisory fees. Morgan Stanley received $7.5 million for writing a fairness opinion letter. Finally, Valuation Research Corporation received $1 million for providing a solvency opinion indicating that Tribune could satisfy its loan covenants.
What appeared to be one of the most complex deals of 2007, designed to reap huge tax advantages, soon became a victim of the downward-spiraling economy, the credit crunch, and its own leverage. A lawsuit filed in late 2008 on behalf of Tribune employees contended that the transaction was flawed from the outset and intended to benefit Sam Zell and his advisors and Tribune’s board. Even if the employees win, they will simply have to stand in line with other Tribune creditors awaiting the resolution of the bankruptcy court proceedings.
-Is this transaction best characterized as a merger, acquisition, leveraged buyout, or spin-off?
The purchase of Tribune's stock was financed almost entirely with debt, with Zell's equity contribution amounting to less than 4% of the purchase price. The transaction resulted in Tribune being burdened with $13 billion in debt (including the approximate $5 billion currently owed by Tribune). At this level, the firm's debt was ten times EBITDA, more than two and a half times that of the average media company. Annual interest and principal repayments reached $800 million (almost three times their preacquisition level), about 62% of the firm's previous EBITDA cash flow of $1.3 billion. While the ESOP owned the company, it was not be liable for the debt guaranteed by Tribune.
The conversion of Tribune into a Subchapter S corporation eliminated the firm's current annual tax liability of $348 million. Such entities pay no corporate income tax but must pay all profit directly to shareholders, who then pay taxes on these distributions. Since the ESOP was the sole shareholder, Tribune was expected to be largely tax exempt, since ESOPs are not taxed.
In an effort to reduce the firm's debt burden, the Tribune Company announced in early 2008 the formation of a partnership in which Cablevision Systems Corporation would own 97% of Newsday for $650 million, with Tribune owning the remaining 3%. However, Tribune was unable to sell the Chicago Cubs (which had been expected to fetch as much as $1 billion) and the minority interest in SportsNet Chicago to help reduce the debt amid the 2008 credit crisis. The worsening of the recession, accelerated by the decline in newspaper and TV advertising revenue, as well as newspaper circulation, thereby eroded the firm's ability to meet its debt obligations.
By filing for Chapter 11 bankruptcy protection, the Tribune Company sought a reprieve from its creditors while it attempted to restructure its business. Although the extent of the losses to employees, creditors, and other stakeholders is difficult to determine, some things are clear. Any pension funds set aside prior to the closing remain with the employees, but it is likely that equity contributions made to the ESOP on behalf of the employees since the closing would be lost. The employees would become general creditors of Tribune. As a holder of subordinated debt, Mr. Zell had priority over the employees if the firm was liquidated and the proceeds distributed to the creditors.
Those benefitting from the deal included Tribune's public shareholders, including the Chandler family, which owed 12% of Tribune as a result of its prior sale of the Times Mirror to Tribune, and Dennis FitzSimons, the firm's former CEO, who received $17.7 million in severance and $23.8 million for his holdings of Tribune shares. Citigroup and Merrill Lynch received $35.8 million and $37 million, respectively, in advisory fees. Morgan Stanley received $7.5 million for writing a fairness opinion letter. Finally, Valuation Research Corporation received $1 million for providing a solvency opinion indicating that Tribune could satisfy its loan covenants.
What appeared to be one of the most complex deals of 2007, designed to reap huge tax advantages, soon became a victim of the downward-spiraling economy, the credit crunch, and its own leverage. A lawsuit filed in late 2008 on behalf of Tribune employees contended that the transaction was flawed from the outset and intended to benefit Sam Zell and his advisors and Tribune’s board. Even if the employees win, they will simply have to stand in line with other Tribune creditors awaiting the resolution of the bankruptcy court proceedings.
-Is this transaction best characterized as a merger, acquisition, leveraged buyout, or spin-off? (Essay)
4.8/5  (73)
(73) Financial buyers usually hold onto their investments for at least 15-20 years.
(True/False)
4.8/5 (82)
(82) Case Study. Private Equity Firms Acquire Yellow Pages Business
Qwest Communications agreed to sell its yellow pages business, QwestDex, to a consortium led by the Carlyle Group and Welsh, Carson, Anderson and Stowe for $7.1 billion. In a two stage transaction, Qwest sold the eastern half of the yellow pages business for $2.75 billion in late 2002. This portion of the business included directories in Colorado, Iowa, Minnesota, Nebraska, New Mexico, South Dakota, and North Dakota. The remainder of the business, Arizona, Idaho, Montana, Oregon, Utah, Washington, and Wyoming, was sold for $4.35 billion in late 2003. Caryle and Welsh Carson each put in $775 million in equity (about 21 percent of the total purchase price).
Qwest was in a precarious financial position at the time of the negotiation. The telecom was trying to avoid bankruptcy and needed the first stage financing to meet impending debt repayments due in late 2002. Qwest is a local phone company in 14 western states and one of the nation's largest long-distance carriers. It had amassed $26.5 billion in debt following a series of acquisitions during the 1990s.
The Carlyle Group has invested globally, mainly in defense and aerospace businesses, but it has also invested in companies in real estate, health care, bottling, and information technology. Welsh Carson focuses primarily on the communications and health care industries. While the yellow pages business is quite different from their normal areas of investment, both firms were attracted by its steady cash flow. Such cash flow could be used to trim debt over time and generate a solid return. The business' existing management team will continue to run the operation under the new ownership. Financing for the deal will come from J.P. Morgan Chase, Bank of America, Lehman Brothers, Wachovia Securities, and Deutsche Bank. The investment groups agreed to a two stage transaction to facilitate borrowing the large amounts required and to reduce the amount of equity each buyout firm had to invest. By staging the purchase, the lenders could see how well the operations acquired during the first stage could manage their debt load.
The new company will be the exclusive directory publisher for Qwest yellow page needs at the local level and will provide all of Qwest's publishing requirements under a fifty year contract. Under the arrangement, Qwest will continue to provide certain services to its former yellow pages unit, such as billing and information technology, under a variety of commercial services and transitional services agreements (Qwest: 2002).
-Why was the equity contribution of the buyout firms as a percentage of the total capital requirements so much higher than amounts contributed during the 1980s?
(Essay)
4.8/5 (92)
(92) Why do you believe were the major factors persuading the MGM board to accept the Revised Sony bid? In
your judgment, do these factors make sense? Explain your answer.
(Essay)
4.9/5 (84)
(84) Borrowers often prefer term loans because they do not have to be concerned that these loans will have to be renewed.
(True/False)
4.8/5 (84)
(84)
Cerberus Capital Management Acquires Chrysler Corporation
According to the terms of the transaction, Cerberus would own 80.1 percent of Chrysler's auto manufacturing and financial services businesses in exchange for $7.4 billion in cash. Daimler would continue to own 19.9 percent of the new business, Chrysler Holdings LLC. Of the $7.4 billion, Daimler would receive $1.35 billion while the remaining $6.05 billion would be invested in Chrysler (i.e., $5.0 billion is to be invested in the auto manufacturing operation and $1.05 billion in the finance unit). Daimler also agreed to pay to Cerberus $1.6 billion to cover Chrysler's long-term debt and cumulative operating losses during the four months between the signing of the merger agreement and the actual closing. In acquiring Chrysler, Cerberus assumed responsibility for an estimated $18 billion in unfunded retiree pension and medical benefits. Daimler also agreed to loan Chrysler Holdings LLC $405 million.
The transaction is atypical of those involving private equity investors, which usually take public firms private, expecting to later sell them for a profit. The private equity firm pays for the acquisition by borrowing against the firm's assets or cash flow. However, the estimated size of Chrysler's retiree health-care liabilities and the uncertainty of future cash flows make borrowing impractical. Therefore, Cerberus agreed to invest its own funds in the business to keep it running while it restructured the business.
By going private, Cerberus would be able to focus on the long-term without the disruption of meeting quarterly earnings reports. Cerberus was counting on paring retiree health-care liabilities through aggressive negotiations with the United Auto Workers (UAW). Cerberus sought a deal similar to what the UAW accepted from Goodyear Tire and Rubber Company in late 2006. Under this agreement, the management of $1.2 billion in health-care liabilities was transferred to a fund managed by the UAW, with Goodyear contributing $1 billion in cash and Goodyear stock. By transferring responsibility for these liabilities to the UAW, Chrysler believed that it would be able to cut in half the $30 dollar per hour labor cost advantage enjoyed by Toyota. Cerberus also expected to benefit from melding Chrysler's financial unit with Cerberus's 51 percent ownership stake in GMAC, GM's former auto financing business. By consolidating the two businesses, Cerberus hoped to slash cost by eliminating duplicate jobs, combining overlapping operations such as data centers and field offices, and increasing the number of loans generated by combining back-office operations.
However, the 2008 credit market meltdown, severe recession, and subsequent free fall in auto sales threatened the financial viability of Chrysler, despite an infusion of U.S. government capital, and it’s leasing operations as well as GMAC. GMAC applied for commercial banking status to be able to borrow directly from the U.S. Federal Reserve. In late 2008, the U.S. Treasury purchased $6 billion in GMAC preferred stock to provide additional capital to the financially ailing firm. To avoid being classified as a bank holding company under direct government supervision, Cerberus reduced its ownership in 2009 to 14.9 percent of voting stock and 33 percent of total equity by distributing equity stakes to its coinvestors in GMAC. By surrendering its controlling interest in GMAC, it is less likely that Cerberus would be able to realize anticipated cost savings by combining the GMAC and Chrysler Financial operations. In early 2009, Chrysler entered into negotiations with Italian auto maker Fiat to gain access to the firm's technology in exchange for a 20 percent stake in Chrysler.
-Cerberus and Daimler will own 80.1% and 19.9% of Chrysler Holdings LLC, respectively. Why do you think the two parties agreed to this distribution of ownership?
(Essay)
4.8/5 (73)
(73) An investor group acquired all of the publicly traded shares of a firm. Once acquired, such shares would no longer trade publicly. Which of the following terms best describes this situation?
(Multiple Choice)
4.8/5 (68)
(68) Asset based lending is commonly used to finance leveraged buyouts. Which of the following is not true about such financing?
(Multiple Choice)
4.9/5 (72)
(72) Borrowers often seek revolving lines of credit that they can draw upon on a daily basis to run their business.
(True/False)
4.7/5 (70)
(70) LBO investors often use public offerings of the firm's stock or sell the firm to a strategic buyer in order to exit the business.
(True/False)
4.9/5 (86)
(86) Management buyouts without a financial equity contributor are relatively rare.
(True/False)
4.7/5 (90)
(90) Identify the form of payment, form of acquisition, acquisition vehicle, and post-closing organization? Speculate why each may have been used.
(Essay)
4.8/5 (82)
(82) Cerberus Capital Management Acquires Chrysler Corporation
According to the terms of the transaction, Cerberus would own 80.1 percent of Chrysler's auto manufacturing and financial services businesses in exchange for $7.4 billion in cash. Daimler would continue to own 19.9 percent of the new business, Chrysler Holdings LLC. Of the $7.4 billion, Daimler would receive $1.35 billion while the remaining $6.05 billion would be invested in Chrysler (i.e., $5.0 billion is to be invested in the auto manufacturing operation and $1.05 billion in the finance unit). Daimler also agreed to pay to Cerberus $1.6 billion to cover Chrysler's long-term debt and cumulative operating losses during the four months between the signing of the merger agreement and the actual closing. In acquiring Chrysler, Cerberus assumed responsibility for an estimated $18 billion in unfunded retiree pension and medical benefits. Daimler also agreed to loan Chrysler Holdings LLC $405 million.
The transaction is atypical of those involving private equity investors, which usually take public firms private, expecting to later sell them for a profit. The private equity firm pays for the acquisition by borrowing against the firm's assets or cash flow. However, the estimated size of Chrysler's retiree health-care liabilities and the uncertainty of future cash flows make borrowing impractical. Therefore, Cerberus agreed to invest its own funds in the business to keep it running while it restructured the business.
By going private, Cerberus would be able to focus on the long-term without the disruption of meeting quarterly earnings reports. Cerberus was counting on paring retiree health-care liabilities through aggressive negotiations with the United Auto Workers (UAW). Cerberus sought a deal similar to what the UAW accepted from Goodyear Tire and Rubber Company in late 2006. Under this agreement, the management of $1.2 billion in health-care liabilities was transferred to a fund managed by the UAW, with Goodyear contributing $1 billion in cash and Goodyear stock. By transferring responsibility for these liabilities to the UAW, Chrysler believed that it would be able to cut in half the $30 dollar per hour labor cost advantage enjoyed by Toyota. Cerberus also expected to benefit from melding Chrysler's financial unit with Cerberus's 51 percent ownership stake in GMAC, GM's former auto financing business. By consolidating the two businesses, Cerberus hoped to slash cost by eliminating duplicate jobs, combining overlapping operations such as data centers and field offices, and increasing the number of loans generated by combining back-office operations.
However, the 2008 credit market meltdown, severe recession, and subsequent free fall in auto sales threatened the financial viability of Chrysler, despite an infusion of U.S. government capital, and it’s leasing operations as well as GMAC. GMAC applied for commercial banking status to be able to borrow directly from the U.S. Federal Reserve. In late 2008, the U.S. Treasury purchased $6 billion in GMAC preferred stock to provide additional capital to the financially ailing firm. To avoid being classified as a bank holding company under direct government supervision, Cerberus reduced its ownership in 2009 to 14.9 percent of voting stock and 33 percent of total equity by distributing equity stakes to its coinvestors in GMAC. By surrendering its controlling interest in GMAC, it is less likely that Cerberus would be able to realize anticipated cost savings by combining the GMAC and Chrysler Financial operations. In early 2009, Chrysler entered into negotiations with Italian auto maker Fiat to gain access to the firm's technology in exchange for a 20 percent stake in Chrysler.
-What were the motivations for this deal from Cerberus' perspective? From Daimler's perspective?
(Essay)
5.0/5 (70)
(70) Which of the following is generally not true about leveraged buyouts?
(Multiple Choice)
4.9/5 (84)
(84) Lessons from Pep Boys’ Aborted Attempt to Go Private
LBOs in recent years have involved financial sponsors’ providing a larger portion of the purchase price in cash than in the past.
Financial sponsors focus increasingly on targets in which they have previous or related experience.
Deals that would have been completed in the early 2000s are more likely to be terminated or subject to renegotiation than in the past.
_____________________________________________________________________________________
It ain’t over till it’s over” quipped former New York Yankees’ catcher Yogi Berra, famous for his malapropisms. The oft-quoted comment was once again proven true in Pep Boys’ unsuccessful attempt to go private in 2012. On May 30, 2012, after nearly two years of discussions between Pep Boys and several interested parties, the firm announced that a buyout agreement with the Gores Group (Gores), valued at approximately $1 billion (including assumed debt), had collapsed, a victim of Pep Boys’ declining operating performance. The firm’s shares fell 20% on the news to $8.89 per share, well below its level following the all-cash $15-a-share deal with Gores announced in January 2012. The terms of the transaction also included a termination fee if either party failed to complete the deal by July 27, 2012. The failed transaction illustrates the characteristics and potential pitfalls common to contemporary LBOs.
Pep Boys, a U.S. auto parts and repair business, operates more than 7,000 service bays in over 700 locations in 35 states and Puerto Rico. With its share price lagging the overall stock market in recent years, the firm’s board of directors explored a range of options for boosting the firm’s value and ultimately decided to put the firm up for sale. Gores was attracted initially by what appeared to be a low purchase price, stable cash flow, and the firm’s real estate holdings (many of the firm’s store sites are owned by the firm). Such assets could be used as collateral underlying loans to finance a portion of the purchase price. Furthermore, Gores has experience in retailing, having several retailers among their portfolio of companies, including J. Mendel and Mexx.
The transaction reflected a structure common for deals of this type. Pep Boys had entered into a merger agreement with Auto Acquisitions Group (the Parent), a shell corporation funded by cash provided by Gores as the financial sponsor, and the Parent’s wholly owned subsidiary (Merger Sub). The Parent would contribute cash to Merger Sub, with Merger Sub borrowing the remainder from several lenders. Merger Sub would subsequently buy Pep Boys’ outstanding shares and merge with the firm. Pep Boys would survive as a wholly owned subsidiary of the Parent. The purpose of this reverse triangular merger was to preserve the Pep Boys’ brand name and facilitate the transfer of supplier and customer contracts. The Parent also was to have been organized as a holding company to afford investors some degree of protection from Pep Boys’ liabilities. The purchase price was to have been financed by an equity contribution of $489 million from limited partnerships managed by Gores and the balance by loans provided by Barclays Bank PLC, Credit Suisse AG, and Wells Fargo Bank.
Upon learning that the Pep Boys’ reported earnings for the first quarter of 2012 would be well below expectations, Gores attempted to renegotiate the terms of the deal, arguing that Pep Boys had breached the deal’s agreements. With Pep Boys unwilling to accept a lower valuation, Gores exercised its right to terminate the deal by paying the $50 million breakup fee and agreed to reimburse Pep Boys for other costs it had incurred related to the deal. Pep Boys said the firm will use the proceeds of the breakup fee to refinance a portion of its outstanding debt.
"Grave Dancer" Takes Tribune Corporation Private in an Ill-Fated Transaction
At the closing in late December 2007, well-known real estate investor Sam Zell described the takeover of the Tribune Company as "the transaction from hell." His comments were prescient in that what had appeared to be a cleverly crafted, albeit highly leveraged, deal from a tax standpoint was unable to withstand the credit malaise of 2008. The end came swiftly when the 161-year-old Tribune filed for bankruptcy on December 8, 2008.
On April 2, 2007, the Tribune Corporation announced that the firm's publicly traded shares would be acquired in a multistage transaction valued at $8.2 billion. Tribune owned at that time 9 newspapers, 23 television stations, a 25% stake in Comcast's SportsNet Chicago, and the Chicago Cubs baseball team. Publishing accounts for 75% of the firm's total $5.5 billion annual revenue, with the remainder coming from broadcasting and entertainment. Advertising and circulation revenue had fallen by 9% at the firm's three largest newspapers (Los Angeles Times, Chicago Tribune, and Newsday in New York) between 2004 and 2006. Despite aggressive efforts to cut costs, Tribune's stock had fallen more than 30% since 2005.
The transaction was implemented in a two-stage transaction, in which Sam Zell acquired a controlling 51% interest in the first stage followed by a backend merger in the second stage in which the remaining outstanding Tribune shares were acquired. In the first stage, Tribune initiated a cash tender offer for 126 million shares (51% of total shares) for $34 per share, totaling $4.2 billion. The tender was financed using $250 million of the $315 million provided by Sam Zell in the form of subordinated debt, plus additional borrowing to cover the balance. Stage 2 was triggered when the deal received regulatory approval. During this stage, an employee stock ownership plan (ESOP) bought the rest of the shares at $34 a share (totaling about $4 billion), with Zell providing the remaining $65 million of his pledge. Most of the ESOP's 121 million shares purchased were financed by debt guaranteed by the firm on behalf of the ESOP. At that point, the ESOP held all of the remaining stock outstanding valued at about $4 billion. In exchange for his commitment of funds, Mr. Zell received a 15-year warrant to acquire 40% of the common stock (newly issued) at a price set at $500 million.
Following closing in December 2007, all company contributions to employee pension plans were funneled into the ESOP in the form of Tribune stock. Over time, the ESOP would hold all the stock. Furthermore, Tribune was converted from a C corporation to a Subchapter S corporation, allowing the firm to avoid corporate income taxes. However, it would have to pay taxes on gains resulting from the sale of assets held less than ten years after the conversion from a C to an S corporation (Figure 1).
The purchase of Tribune's stock was financed almost entirely with debt, with Zell's equity contribution amounting to less than 4% of the purchase price. The transaction resulted in Tribune being burdened with $13 billion in debt (including the approximate $5 billion currently owed by Tribune). At this level, the firm's debt was ten times EBITDA, more than two and a half times that of the average media company. Annual interest and principal repayments reached $800 million (almost three times their preacquisition level), about 62% of the firm's previous EBITDA cash flow of $1.3 billion. While the ESOP owned the company, it was not be liable for the debt guaranteed by Tribune.
The conversion of Tribune into a Subchapter S corporation eliminated the firm's current annual tax liability of $348 million. Such entities pay no corporate income tax but must pay all profit directly to shareholders, who then pay taxes on these distributions. Since the ESOP was the sole shareholder, Tribune was expected to be largely tax exempt, since ESOPs are not taxed.
In an effort to reduce the firm's debt burden, the Tribune Company announced in early 2008 the formation of a partnership in which Cablevision Systems Corporation would own 97% of Newsday for $650 million, with Tribune owning the remaining 3%. However, Tribune was unable to sell the Chicago Cubs (which had been expected to fetch as much as $1 billion) and the minority interest in SportsNet Chicago to help reduce the debt amid the 2008 credit crisis. The worsening of the recession, accelerated by the decline in newspaper and TV advertising revenue, as well as newspaper circulation, thereby eroded the firm's ability to meet its debt obligations.
By filing for Chapter 11 bankruptcy protection, the Tribune Company sought a reprieve from its creditors while it attempted to restructure its business. Although the extent of the losses to employees, creditors, and other stakeholders is difficult to determine, some things are clear. Any pension funds set aside prior to the closing remain with the employees, but it is likely that equity contributions made to the ESOP on behalf of the employees since the closing would be lost. The employees would become general creditors of Tribune. As a holder of subordinated debt, Mr. Zell had priority over the employees if the firm was liquidated and the proceeds distributed to the creditors.
Those benefitting from the deal included Tribune's public shareholders, including the Chandler family, which owed 12% of Tribune as a result of its prior sale of the Times Mirror to Tribune, and Dennis FitzSimons, the firm's former CEO, who received $17.7 million in severance and $23.8 million for his holdings of Tribune shares. Citigroup and Merrill Lynch received $35.8 million and $37 million, respectively, in advisory fees. Morgan Stanley received $7.5 million for writing a fairness opinion letter. Finally, Valuation Research Corporation received $1 million for providing a solvency opinion indicating that Tribune could satisfy its loan covenants.
What appeared to be one of the most complex deals of 2007, designed to reap huge tax advantages, soon became a victim of the downward-spiraling economy, the credit crunch, and its own leverage. A lawsuit filed in late 2008 on behalf of Tribune employees contended that the transaction was flawed from the outset and intended to benefit Sam Zell and his advisors and Tribune’s board. Even if the employees win, they will simply have to stand in line with other Tribune creditors awaiting the resolution of the bankruptcy court proceedings.
-What is the acquisition vehicle, post-closing organization, form of payment, form of acquisition, and tax strategy described in this case study?
The purchase of Tribune's stock was financed almost entirely with debt, with Zell's equity contribution amounting to less than 4% of the purchase price. The transaction resulted in Tribune being burdened with $13 billion in debt (including the approximate $5 billion currently owed by Tribune). At this level, the firm's debt was ten times EBITDA, more than two and a half times that of the average media company. Annual interest and principal repayments reached $800 million (almost three times their preacquisition level), about 62% of the firm's previous EBITDA cash flow of $1.3 billion. While the ESOP owned the company, it was not be liable for the debt guaranteed by Tribune.
The conversion of Tribune into a Subchapter S corporation eliminated the firm's current annual tax liability of $348 million. Such entities pay no corporate income tax but must pay all profit directly to shareholders, who then pay taxes on these distributions. Since the ESOP was the sole shareholder, Tribune was expected to be largely tax exempt, since ESOPs are not taxed.
In an effort to reduce the firm's debt burden, the Tribune Company announced in early 2008 the formation of a partnership in which Cablevision Systems Corporation would own 97% of Newsday for $650 million, with Tribune owning the remaining 3%. However, Tribune was unable to sell the Chicago Cubs (which had been expected to fetch as much as $1 billion) and the minority interest in SportsNet Chicago to help reduce the debt amid the 2008 credit crisis. The worsening of the recession, accelerated by the decline in newspaper and TV advertising revenue, as well as newspaper circulation, thereby eroded the firm's ability to meet its debt obligations.
By filing for Chapter 11 bankruptcy protection, the Tribune Company sought a reprieve from its creditors while it attempted to restructure its business. Although the extent of the losses to employees, creditors, and other stakeholders is difficult to determine, some things are clear. Any pension funds set aside prior to the closing remain with the employees, but it is likely that equity contributions made to the ESOP on behalf of the employees since the closing would be lost. The employees would become general creditors of Tribune. As a holder of subordinated debt, Mr. Zell had priority over the employees if the firm was liquidated and the proceeds distributed to the creditors.
Those benefitting from the deal included Tribune's public shareholders, including the Chandler family, which owed 12% of Tribune as a result of its prior sale of the Times Mirror to Tribune, and Dennis FitzSimons, the firm's former CEO, who received $17.7 million in severance and $23.8 million for his holdings of Tribune shares. Citigroup and Merrill Lynch received $35.8 million and $37 million, respectively, in advisory fees. Morgan Stanley received $7.5 million for writing a fairness opinion letter. Finally, Valuation Research Corporation received $1 million for providing a solvency opinion indicating that Tribune could satisfy its loan covenants.
What appeared to be one of the most complex deals of 2007, designed to reap huge tax advantages, soon became a victim of the downward-spiraling economy, the credit crunch, and its own leverage. A lawsuit filed in late 2008 on behalf of Tribune employees contended that the transaction was flawed from the outset and intended to benefit Sam Zell and his advisors and Tribune’s board. Even if the employees win, they will simply have to stand in line with other Tribune creditors awaiting the resolution of the bankruptcy court proceedings.
-What is the acquisition vehicle, post-closing organization, form of payment, form of acquisition, and tax strategy described in this case study? (Essay)
4.7/5 (63)
(63) Accounts receivable represent an undesirable form of collateral from the lender's point of view because they are often illiquid.
(True/False)
4.8/5 (74)
(74) In a move reminiscent of the blockbuster buyouts of the late 1980s, seven private investment firms acquired
100 percent of the outstanding stock of SunGard Data Systems Inc. (SunGard) in late 2005. SunGard is a financial software firm known for providing application and transaction software services and creating backup data systems in the event of disaster. The company's software manages 70 percent of the transactions made on the Nasdaq stock exchange, but its biggest business is creating backup data systems in case a client's main systems are disabled by a natural disaster, blackout, or terrorist attack. Its large client base for disaster recovery and back-up systems provides a substantial and predictable cash flow. Furthermore, the firm had substantial amounts of largely unencumbered current assets. The deal left SunGard with a nearly 5 to 1 debt to equity ratio. Why do you believe lenders might have been willing to finance such a highly leveraged transaction?
(Essay)
4.7/5 (85)
(85) There is some evidence that the Sarbanes-Oxley Act of 2002 has also been a factor in some firms going private as a result of the onerous reporting requirements of the bill.
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)