



 Chat with AI
Exam 13: Financing the Deal

Exam 1: Introduction to Mergers, Acquisitions, and Other Restructuring Activities139 Questions
Exam 2: The Regulatory Environment129 Questions
Exam 3: The Corporate Takeover Market:152 Questions
Exam 4: Planning: Developing Business and Acquisition Plans: Phases 1 and 2 of the Acquisition Process137 Questions
Exam 5: Implementation: Search Through Closing: Phases 310 of the Acquisition Process131 Questions
Exam 6: Postclosing Integration: Mergers, Acquisitions, and Business Alliances138 Questions
Exam 7: Merger and Acquisition Cash Flow Valuation Basics108 Questions
Exam 8: Relative, Asset-Oriented, and Real Option109 Questions
Exam 9: Financial Modeling Basics:97 Questions
Exam 10: Analysis and Valuation127 Questions
Exam 11: Structuring the Deal:138 Questions
Exam 12: Structuring the Deal:125 Questions
Exam 13: Financing the Deal149 Questions
Exam 14: Applying Financial Modeling116 Questions
Exam 15: Business Alliances: Joint Ventures, Partnerships, Strategic Alliances, and Licensing138 Questions
Exam 16: Alternative Exit and Restructuring Strategies152 Questions
Exam 17: Alternative Exit and Restructuring Strategies:118 Questions
Exam 18: Cross-Border Mergers and Acquisitions:120 Questions
Select questions type


With their cash hoards accumulating at an unprecedented rate, there was little that buyout firms could do but to invest in larger firms. Consequently, the average size of LBO transactions grew significantly during 2005. In a move reminiscent of the blockbuster buyouts of the late 1980s, seven private investment firms acquired 100 percent of the outstanding stock of SunGard Data Systems Inc. (SunGard) in late 2005. SunGard is a financial software firm known for providing application and transaction software services and creating backup data systems in the event of disaster. The company‘s software manages 70 percent of the transactions made on the Nasdaq stock exchange, but its biggest business is creating backup data systems in case a client’s main systems are disabled by a natural disaster, blackout, or terrorist attack. Its large client base for disaster recovery and back-up systems provides a substantial and predictable cash flow.
SunGard’s new owners include Silver lake Partners, Bain Capital LLC, The Blackstone Group L.P., Goldman Sachs Capital Partners, Kohlberg Kravis Roberts & Co., Providence Equity Partners Inc. and Texas Pacific Group. Buyout firms in 2005 tended to band together to spread the risk of a deal this size and to reduce the likelihood of a bidding war. Indeed, with SunGard, there was only one bidder, the investor group consisting of these seven firms.
The software side of SunGard is believed to have significant growth potential, while the disaster-recovery side provides a large stable cash flow. Unlike many LBOs, the deal was announced as being all about growth of the financial services software side of the business. The deal is structured as a merger, since SunGard would be merged into a shell corporation created by the investor group for acquiring SunGard. Going private, allows SunGard to invest heavily in software without being punished by investors, since such investments are expensed and reduce reported earnings per share. Going private also allows the firm to eliminate the burdensome reporting requirements of being a public company.
The buyout represented potentially a significant source of fee income for the investor group. In addition to the 2 percent management fees buyout firms collect from investors in the funds they manage, they receive substantial fee income from each investment they make on behalf of their funds. For example, the buyout firms receive a 1 percent deal completion fee, which is more than $100 million in the SunGard transaction. Buyout firms also receive fees paid for by the target firm that is “going private” for arranging financing. Moreover, there are also fees for conducting due diligence and for monitoring the ongoing performance of the firm taken private. Finally, when the buyout firms exit their investments in the target firm via a sale to a strategic buyer or a secondary IPO, they receive 20 percent (i.e., so-called carry fee) of any profits.
Under the terms of the agreement, SunGard shareholders received $36 per share, a 14 percent premium over the SunGard closing price as of the announcement date of March 28, 2005, and 40 percent more than when the news first leaked about the deal a week earlier. From the SunGard shareholders’ perspective, the deal is valued at $11.4 billion dollars consisting of $10.9 billion for outstanding shares and “in-the-money” options (i.e., options whose exercise price is less than the firm’s market price per share) plus $500 million in debt on the balance sheet.
The seven equity investors provided $3.5 billion in capital with the remainder of the purchase price financed by commitments from a lending consortium consisting of Citigroup, J.P. Morgan Chase & Co., and Deutsche Bank. The purpose of the loans is to finance the merger, repay or refinance SunGard’s existing debt, provide ongoing working capital, and pay fees and expenses incurred in connection with the merger. The total funds necessary to complete the merger and related fees and expenses is approximately $11.3 billion, consisting of approximately $10.9 billion to pay SunGard’s stockholders and about $400.7 million to pay fees and expenses related to the merger and the financing arrangements. Note that the fees that are to be financed comprise almost 4 percent of the purchase price. Ongoing working capital needs and capital expenditures required obtaining commitments from lenders well in excess of $11.3 billion.
The merger financing consists of several tiers of debt and “credit facilities.” Credit facilities are arrangements for extending credit. The senior secured debt and senior subordinated debt are intended to provide “permanent” or long-term financing. Senior debt covenants included restrictions on new borrowing, investments, sales of assets, mergers and consolidations, prepayments of subordinated indebtedness, capital expenditures, liens and dividends and other distributions, as well as a minimum interest coverage ratio and a maximum total leverage ratio.
If the offering of notes is not completed on or prior to the closing, the banks providing the financing have committed to provide up to $3 billion in loans under a senior subordinated bridge credit facility. The bridge loans are intended as a form of temporary financing to satisfy immediate cash requirements until permanent financing can be arranged. A special purpose SunGard subsidiary will purchase receivables from SunGard, with the purchases financed through the sale of the receivables to the lending consortium. The lenders subsequently finance the purchase of the receivables by issuing commercial paper, which is repaid as the receivables are collected. The special purpose subsidiary is not shown on the SunGard balance sheet. Based on the value of receivables at closing, the subsidiary could provide up to $500 million. The obligation of the lending consortium to buy the receivables will expire on the sixth anniversary of the closing of the merger.
The following table provides SunGard’s post-merger proforma capital structure. Note that the proforma capital structure is portrayed as if SunGard uses 100 percent of bank lending commitments. Also, note that individual LBO investors may invest monies from more than one fund they manage. This may be due to the perceived attractiveness of the opportunity or the limited availability of money in any single fund. Of the $9 billion in debt financing, bank loans constitute 56 percent and subordinated or mezzanine debt comprises represents 44 percent.
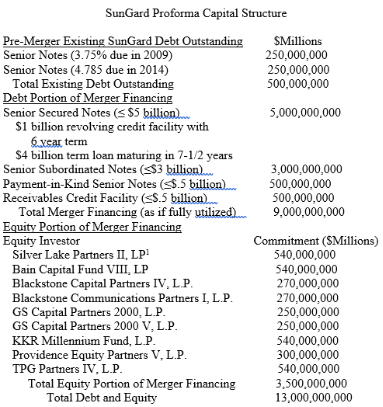 The roman numeral II refers to the fund providing the equity capital managed by the partnership
-Why are payment-in-kind securities (e.g., debt or preferred stock) particularly well suited for financing LBOs? Under what circumstances might they be most attractive to lenders or investors?
The roman numeral II refers to the fund providing the equity capital managed by the partnership
-Why are payment-in-kind securities (e.g., debt or preferred stock) particularly well suited for financing LBOs? Under what circumstances might they be most attractive to lenders or investors? (Essay)
4.7/5  (75)
(75) TXU Goes Private in the Largest Private Equity Transaction in History-The Dark Side of Leverage
Key Points
The 2007/2008 financial crisis left many LBOs excessively leveraged.
As structured, the TXU buyout (now Energy Future Holdings) left no margin for error.
Excessive leverage severely limits the firm's future financial options.
_____________________________________________________________________________
Before the buyout, TXU, a Dallas-based energy giant, was a highly profitable utility. Historically low interest rates and an overly optimistic outlook for natural gas prices set the stage for the largest private equity deal in history. The 2007 buyout of TXU was valued at $48 billion and, at the time, appeared to offer such promise that several of Wall Street's largest lenders --including the likes of Lehman Brothers and Citigroup-invested, along with such storied names in private equity as KKR, TPG, and Goldman Sachs. However, the price of gas plummeted, eroding TXU's cash flow. Since the deal closed in October 2007, investors who bought $40 billion of TXU's debt have experienced losses as high as 70% to 80% of their value. The other $8 billion used to finance the deal came from the private equity investors, banks, and large institutional investors. They, too, have suffered huge losses. Having met its obligations to date, the firm faces a $20 billion debt repayment coming due in 2014.
Wall Street banks were competing in 2007 to make loans to buyout firms on easier terms, with the banks also investing their own funds in the deal. The allure to the banks was the prospect of dividing up as much as $1.1 billion in fees for originating the loans, repackaging such loans into pools called collateralized loan obligations, and reselling them to long-term investors such as pension funds and insurance companies. In doing so, the loans would be removed from the banks' balance sheets, eliminating potential losses that could arise if the deal soured at a later date. Furthermore, the deal appeared to be attractive as an investment opportunity because some banks put up $500 million of their own cash for a stake in TXU.
The financial sponsor group, consisting of Kohlberg Kravis Roberts & Co, Texas Pacific Group, and Goldman Sachs, created a shell corporation, referred to as Merger Sub Parent, and its wholly owned subsidiary Merger Sub. TXU was merged into Merger Sub, with Merger Sub surviving. Each outstanding share of TXU common stock was converted into the right to receive $69.25 in cash. Total cash required for the purchase was provided by the financial sponsor group and lenders (Creditor Group) to Merger Sub. Regulatory authorities required that the debt associated with the transaction be held at the level of the Merger Sub Parent holding company so as not to leverage the utility further.
Subsequent to closing, the new company was reorganized into independent businesses under a new holding company, controlled by the Sponsor Group, called Texas Holdings (TH). Merger Sub (which owns TXU) was renamed Energy Future Holdings. TH's direct subsidiaries are EFH and Oncor (an energy distribution business formerly held by TXU). EFH's primary direct subsidiary is Texas Competitive Electric Holdings, which holds TXU's public utility operating assets and liabilities. All TXU non-Sponsor Group-related debt incurred to finance the transaction is held by EFH, while any debt incurred by the Sponsor Group is shown on the TH balance sheet. This legal structure allows for the concentration of debt in TH and EFH, separate from the cash-generating assets held by Oncor and Texas Competitive Electric Holdings.
Loan covenants limit EFH's and its subsidiaries' ability to issue new debt or preferred stock; pay dividends on, repurchase, or make distributions of capital stock or make other restricted payments; make investments; sell or transfer assets; consolidate, merge, sell, or dispose of all or substantially all its assets; and repay, repurchase, or modify debt. A breach of any of these covenants could result in default. Table 13.6 illustrates selected covenants in which certain ratios must be maintained either above or below stipulated thresholds. Note that EFH was in violation of certain covenants when you compare actual December 31, 2009 (the last year for which public information is available), ratios with required threshold levels.
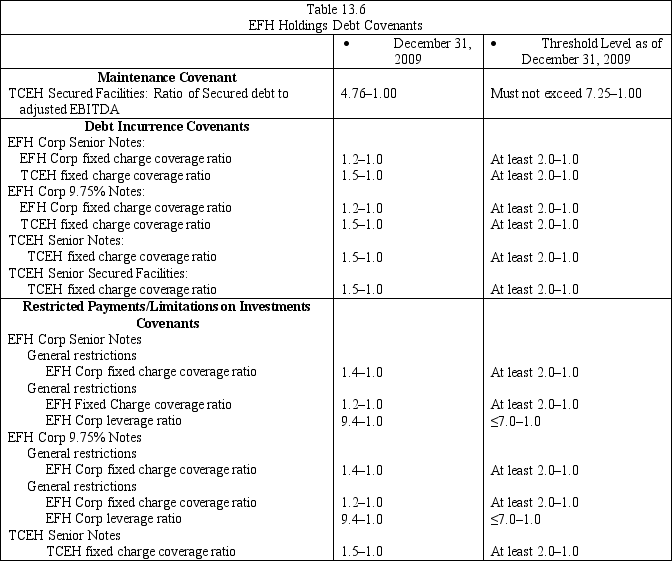 -December 31, 2009
-Threshold Level as of December 31, 2009
Things clearly have not turned out as expected. The firm faces an almost-untenable capital structure. The firm's debt traded at between 20 and 30 cents on the dollar throughout most of 2012. The $8 billion equity invested in the deal has been virtually wiped out on paper. Absent a turnaround in natural gas prices, EFH is left with seeking a way to reduce substantially the burden of the pending 2014 $20 billion loan payment with its lenders through a debt-for-equity swap or more favorable terms on existing debt or by pursuing Chapter 11 bankruptcy. EFH has posted eight consecutive quarterly losses. In December 2012, in an effort to extend debt maturities to buy time for a turnaround and to reduce interest expense, EFH exchanged $1.15 billion of new payment-in-kind notes (interest is paid with more debt) for existing notes with a face value of $1.6 billion. By any measure, this transaction illustrates the dark side of leverage.
-How does the postclosing holding company structure protect the interests of the financial sponsor group and the utility's customers but potentially jeopardize creditor interests in the event of bankruptcy?
-December 31, 2009
-Threshold Level as of December 31, 2009
Things clearly have not turned out as expected. The firm faces an almost-untenable capital structure. The firm's debt traded at between 20 and 30 cents on the dollar throughout most of 2012. The $8 billion equity invested in the deal has been virtually wiped out on paper. Absent a turnaround in natural gas prices, EFH is left with seeking a way to reduce substantially the burden of the pending 2014 $20 billion loan payment with its lenders through a debt-for-equity swap or more favorable terms on existing debt or by pursuing Chapter 11 bankruptcy. EFH has posted eight consecutive quarterly losses. In December 2012, in an effort to extend debt maturities to buy time for a turnaround and to reduce interest expense, EFH exchanged $1.15 billion of new payment-in-kind notes (interest is paid with more debt) for existing notes with a face value of $1.6 billion. By any measure, this transaction illustrates the dark side of leverage.
-How does the postclosing holding company structure protect the interests of the financial sponsor group and the utility's customers but potentially jeopardize creditor interests in the event of bankruptcy? (Essay)
4.9/5 (66)
(66) LBOs often exhibit very high financial returns during the years following their creation. Which of the following best describes why this might occur?
(Multiple Choice)
4.9/5 (90)
(90) Leveraged buyout firms use the unencumbered assets and operating cash flow of the target firm to finance the transaction.
(True/False)
4.8/5 (72)
(72) Investors in LBOs are frequently referred to as financial buyers, because they are primarily focused on relatively short-to-intermediate-term financial returns.
(True/False)
4.9/5 (82)
(82) Loan agreements commonly have cross-default provisions allowing a lender to collect its loan immediately if the borrower is in default on a loan to another lender.
(True/False)
4.9/5 (79)
(79) Preferred stock often is issued in LBO transactions, because it provides investors a fixed income security, which has a claim that is junior to common stock in the event of liquidation.
(True/False)
4.9/5 (86)
(86) LBO firms seldom purchase a firm to use as a platform to undertake other leveraged buyouts in the same industry.
(True/False)
4.9/5 (90)
(90) RJR NABISCO GOES PRIVATE-
KEY SHAREHOLDER AND PUBLIC POLICY ISSUES
Background
The largest LBO in history is as well known for its theatrics as it is for its substantial improvement in shareholder value. In October 1988, H. Ross Johnson, then CEO of RJR Nabisco, proposed an MBO of the firm at $75 per share. His failure to inform the RJR board before publicly announcing his plans alienated many of the directors. Analysts outside the company placed the breakup value of RJR Nabisco at more than $100 per share-almost twice its then current share price. Johnson's bid immediately was countered by a bid by the well-known LBO firm, Kohlberg, Kravis, and Roberts (KKR), to buy the firm for $90 per share (Wasserstein, 1998). The firm's board immediately was faced with the dilemma of whether to accept the KKR offer or to consider some other form of restructuring of the company. The board appointed a committee of outside directors to assess the bid to minimize the appearance of a potential conflict of interest in having current board members, who were also part of the buyout proposal from management, vote on which bid to select.
The bidding war soon escalated with additional bids coming from Forstmann Little and First Boston, although the latter's bid never really was taken very seriously. Forstmann Little later dropped out of the bidding as the purchase price rose. Although the firm's investment bankers valued both the bids by Johnson and KKR at about the same level, the board ultimately accepted the KKR bid. The winning bid was set at almost $25 billion-the largest transaction on record at that time and the largest LBO in history. Banks provided about three-fourths of the $20 billion that was borrowed to complete the transaction. The remaining debt was supplied by junk bond financing. The RJR shareholders were the real winners, because the final purchase price constituted a more than 100% return from the $56 per share price that existed just before the initial bid by RJR management.
Aggressive pricing actions by such competitors as Phillip Morris threatened to erode RJR Nabisco's ability to service its debt. Complex securities such as "increasing rate notes," whose coupon rates had to be periodically reset to ensure that these notes would trade at face value, ultimately forced the credit rating agencies to downgrade the RJR Nabisco debt. As market interest rates climbed, RJR Nabisco did not appear to have sufficient cash to accommodate the additional interest expense on the increasing return notes. To avoid default, KKR recapitalized the company by investing additional equity capital and divesting more than $5 billion worth of businesses in 1990 to help reduce its crushing debt load. In 1991, RJR went public by issuing more than $1 billion in new common stock, which placed about one-fourth of the firm's common stock in public hands.
When KKR eventually fully liquidated its position in RJR Nabisco in 1995, it did so for a far smaller profit than expected. KKR earned a profit of about $60 million on an equity investment of $3.1 billion. KKR had not done well for the outside investors who had financed more than 90% of the total equity investment in KKR. However, KKR fared much better than investors had in its LBO funds by earning more than $500 million in transaction fees, advisor fees, management fees, and directors' fees. The publicity surrounding the transaction did not cease with the closing of the transaction. Dissident bondholders filed suits alleging that the payment of such a large premium for the company represented a "confiscation" of bondholder wealth by shareholders.
Potential Conflicts of Interest
In any MBO, management is confronted by a potential conflict of interest. Their fiduciary responsibility to the shareholders is to take actions to maximize shareholder value; yet in the RJR Nabisco case, the management bid appeared to be well below what was in the best interests of shareholders. Several proposals have been made to minimize the potential for conflict of interest in the case of an MBO, including that directors, who are part of an MBO effort, not be allowed to participate in voting on bids, that fairness opinions be solicited from independent financial advisors, and that a firm receiving an MBO proposal be required to hold an auction for the firm.
The most contentious discussion immediately following the closing of the RJR Nabisco buyout centered on the alleged transfer of wealth from bond and preferred stockholders to common stockholders when a premium was paid for the shares held by RJR Nabisco common stockholders. It often is argued that at least some part of the premium is offset by a reduction in the value of the firm's outstanding bonds and preferred stock because of the substantial increase in leverage that takes place in LBOs.
Winners and Losers
RJR Nabisco shareholders before the buyout clearly benefited greatly from efforts to take the company private. However, in addition to the potential transfer of wealth from bondholders to stockholders, some critics of LBOs argue that a wealth transfer also takes place in LBO transactions when LBO management is able to negotiate wage and benefit concessions from current employee unions. LBOs are under greater pressure to seek such concessions than other types of buyouts because they need to meet huge debt service requirements.
-How might bondholders and preferred stockholders have been hurt in the RJR Nabisco leveraged buyout?
(Essay)
4.8/5 (66)
(66) Cox Enterprises Offers to Take Cox Communications Private
In an effort to take the firm private, Cox Enterprises announced on August 3, 2004 a proposal to buy the remaining 38% of Cox Communications' shares that they did not currently own for $32 per share. Cox Communications is the third largest provider of cable television, telecommunications, and wireless services in the U.S, serving more than 6.2 million customers. Historically, the firm's cash flow has been steady and substantial.
The deal is valued at $7.9 billion and represented a 16% premium to Cox Communication's share price at that time. Cox Communications would become a subsidiary of Cox Enterprises and would continue to operate as an autonomous business. In response to the proposal, the Cox Communications Board of Directors formed a special committee of independent directors to consider the proposal. Citigroup Global Markets and Lehman Brothers Inc. have committed $10 billion to the deal. Cox Enterprises would use $7.9 billion for the tender offer, with the remaining $2.1 billion used for refinancing existing debt and to satisfy working capital requirements.
Cable service firms have faced intensified competitive pressures from satellite service providers DirecTV Group and EchoStar communications. Moreover, telephone companies continue to attack cable's high-speed Internet service by cutting prices on high-speed Internet service over phone lines. Cable firms have responded by offering a broader range of advanced services like video-on-demand and phone service. Since 2000, the cable industry has invested more than $80 billion to upgrade their systems to provide such services, causing profitability to deteriorate and frustrating investors. In response, cable company stock prices have fallen. Cox Enterprises stated that the increasingly competitive cable industry environment makes investment in the cable industry best done through a private company structure.
:
-Why did the board feel that it was appropriate to set up special committee of independent board directors?
(Essay)
4.9/5 (84)
(84) While most LBOs are predicated on improving operating performance through a combination of aggressive
cost cutting and revenue growth, hospital chain HCA laid out an unconventional approach which relied heavily on revenue growth in its effort to take the firm private. On July 24, 2006, management again announced that it would "go private" in a deal valued at $33 billion including the assumption of $11.7 billion in existing debt. Would you consider a hospital chain a good or bad candidate for an LBO? Be specific.
(Essay)
4.9/5 (73)
(73) Case Study. Private Equity Firms Acquire Yellow Pages Business
Qwest Communications agreed to sell its yellow pages business, QwestDex, to a consortium led by the Carlyle Group and Welsh, Carson, Anderson and Stowe for $7.1 billion. In a two stage transaction, Qwest sold the eastern half of the yellow pages business for $2.75 billion in late 2002. This portion of the business included directories in Colorado, Iowa, Minnesota, Nebraska, New Mexico, South Dakota, and North Dakota. The remainder of the business, Arizona, Idaho, Montana, Oregon, Utah, Washington, and Wyoming, was sold for $4.35 billion in late 2003. Caryle and Welsh Carson each put in $775 million in equity (about 21 percent of the total purchase price).
Qwest was in a precarious financial position at the time of the negotiation. The telecom was trying to avoid bankruptcy and needed the first stage financing to meet impending debt repayments due in late 2002. Qwest is a local phone company in 14 western states and one of the nation's largest long-distance carriers. It had amassed $26.5 billion in debt following a series of acquisitions during the 1990s.
The Carlyle Group has invested globally, mainly in defense and aerospace businesses, but it has also invested in companies in real estate, health care, bottling, and information technology. Welsh Carson focuses primarily on the communications and health care industries. While the yellow pages business is quite different from their normal areas of investment, both firms were attracted by its steady cash flow. Such cash flow could be used to trim debt over time and generate a solid return. The business' existing management team will continue to run the operation under the new ownership. Financing for the deal will come from J.P. Morgan Chase, Bank of America, Lehman Brothers, Wachovia Securities, and Deutsche Bank. The investment groups agreed to a two stage transaction to facilitate borrowing the large amounts required and to reduce the amount of equity each buyout firm had to invest. By staging the purchase, the lenders could see how well the operations acquired during the first stage could manage their debt load.
The new company will be the exclusive directory publisher for Qwest yellow page needs at the local level and will provide all of Qwest's publishing requirements under a fifty year contract. Under the arrangement, Qwest will continue to provide certain services to its former yellow pages unit, such as billing and information technology, under a variety of commercial services and transitional services agreements (Qwest: 2002).
-Why does Cox Enterprises believe that the investment needed for growing its cable business is best done through a private company structure?
(Essay)
4.8/5 (81)
(81) The acquirer often is asked for a commitment letter from a lender, which commits the lender to providing financing for the transaction.
(True/False)
4.9/5 (76)
(76) LBO investors must be very careful not to overpay for a target firm because
(Multiple Choice)
4.8/5 (75)
(75) The loan agreement stipulates the terms and conditions under which the lender will loan the firm funds.
(True/False)
4.9/5 (97)
(97) When a public company is subject to a leveraged buyout, it is said to be "going private."
(True/False)
4.8/5 (90)
(90) Most highly leveraged transactions consist of acquisitions of private rather public firms.
(True/False)
4.9/5 (88)
(88) Cerberus Capital Management Acquires Chrysler Corporation
According to the terms of the transaction, Cerberus would own 80.1 percent of Chrysler's auto manufacturing and financial services businesses in exchange for $7.4 billion in cash. Daimler would continue to own 19.9 percent of the new business, Chrysler Holdings LLC. Of the $7.4 billion, Daimler would receive $1.35 billion while the remaining $6.05 billion would be invested in Chrysler (i.e., $5.0 billion is to be invested in the auto manufacturing operation and $1.05 billion in the finance unit). Daimler also agreed to pay to Cerberus $1.6 billion to cover Chrysler's long-term debt and cumulative operating losses during the four months between the signing of the merger agreement and the actual closing. In acquiring Chrysler, Cerberus assumed responsibility for an estimated $18 billion in unfunded retiree pension and medical benefits. Daimler also agreed to loan Chrysler Holdings LLC $405 million.
The transaction is atypical of those involving private equity investors, which usually take public firms private, expecting to later sell them for a profit. The private equity firm pays for the acquisition by borrowing against the firm's assets or cash flow. However, the estimated size of Chrysler's retiree health-care liabilities and the uncertainty of future cash flows make borrowing impractical. Therefore, Cerberus agreed to invest its own funds in the business to keep it running while it restructured the business.
By going private, Cerberus would be able to focus on the long-term without the disruption of meeting quarterly earnings reports. Cerberus was counting on paring retiree health-care liabilities through aggressive negotiations with the United Auto Workers (UAW). Cerberus sought a deal similar to what the UAW accepted from Goodyear Tire and Rubber Company in late 2006. Under this agreement, the management of $1.2 billion in health-care liabilities was transferred to a fund managed by the UAW, with Goodyear contributing $1 billion in cash and Goodyear stock. By transferring responsibility for these liabilities to the UAW, Chrysler believed that it would be able to cut in half the $30 dollar per hour labor cost advantage enjoyed by Toyota. Cerberus also expected to benefit from melding Chrysler's financial unit with Cerberus's 51 percent ownership stake in GMAC, GM's former auto financing business. By consolidating the two businesses, Cerberus hoped to slash cost by eliminating duplicate jobs, combining overlapping operations such as data centers and field offices, and increasing the number of loans generated by combining back-office operations.
However, the 2008 credit market meltdown, severe recession, and subsequent free fall in auto sales threatened the financial viability of Chrysler, despite an infusion of U.S. government capital, and it’s leasing operations as well as GMAC. GMAC applied for commercial banking status to be able to borrow directly from the U.S. Federal Reserve. In late 2008, the U.S. Treasury purchased $6 billion in GMAC preferred stock to provide additional capital to the financially ailing firm. To avoid being classified as a bank holding company under direct government supervision, Cerberus reduced its ownership in 2009 to 14.9 percent of voting stock and 33 percent of total equity by distributing equity stakes to its coinvestors in GMAC. By surrendering its controlling interest in GMAC, it is less likely that Cerberus would be able to realize anticipated cost savings by combining the GMAC and Chrysler Financial operations. In early 2009, Chrysler entered into negotiations with Italian auto maker Fiat to gain access to the firm's technology in exchange for a 20 percent stake in Chrysler.
-What are the risks to this deal's eventual success? Be specific.
(Essay)
4.9/5 (65)
(65) Bridge financing is usually expected to be replaced within two years after the closing date of the LBO transaction.
(True/False)
4.9/5 (79)
(79) Because term loans are negotiated privately between the borrower and the lender, they are much more expensive than the costs associated with floating a public debt or stock issue.
(True/False)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)