



 Chat with AI
Exam 12: Debt Financing

Exam 1: Financial Reporting86 Questions
Exam 2: A Review of the Accounting Cycle94 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements72 Questions
Exam 4: The Income Statement82 Questions
Exam 5: Statement of Cash Flows and Articulation79 Questions
Exam 6: Earnings Management46 Questions
Exam 7: The Revenuereceivablescash Cycle81 Questions
Exam 8: Revenue Recognition74 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing103 Questions
Exam 13: Equity Financing88 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases80 Questions
Exam 16: Income Taxes77 Questions
Exam 17: Employee Compensation-Payroll, Pensions, Other Comp Issues78 Questions
Exam 18: Earnings Per Share78 Questions
Exam 19: Derivatives, Contingencies, Business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections74 Questions
Exam 21: Statement of Cash Flows Revisited61 Questions
Exam 22: Accounting in a Global Market60 Questions
Exam 23: Analysis of Financial Statements57 Questions
Select questions type


Bond discount should be presented in the financial statements of the issuer as a(n)
(Multiple Choice)
5.0/5  (78)
(78) On February 1, 2012, Lantern Corp. issued 12 percent, $2,000,000 face value, ten-year bonds for $2,234,000 plus accrued interest. The bonds are dated November 1, 2011, and interest is payable on May 1 and November 1. Lantern reacquired all of these bonds at 102 on May 1, 2015, and retired them. Unamortized bond premium on that date was $156,000. Ignoring the income tax effect, what was Lantern's gain on the bond retirement?
(Multiple Choice)
4.9/5 (72)
(72) Laker, Inc. had outstanding 10 percent, $1,000,000 face value, convertible bonds maturing on December 31, 2014. Interest is paid December 31 and June 30. After amortization through June 30, 2011, the unamortized balance in the bond premium account was $30,000. On that date, bonds with a face amount of $500,000 were converted into 20,000 shares of $20 par common stock. Recording the conversion by using the carrying value of the bonds, Laker should credit Additional Paid-In Capital for
(Multiple Choice)
4.9/5 (92)
(92) White Sox Corporation issued $200,000 of 10-year bonds on January 1. The bonds pay interest on January 1 and July 1 and have a stated rate of 10 percent. If the market rate of interest at the time the bonds are sold is 8 percent, what will be the issuance price of the bonds?
(Multiple Choice)
4.8/5 (87)
(87) A variable interest in a variable interest entity (VIE) may arise from all of the following except
(Multiple Choice)
4.9/5 (69)
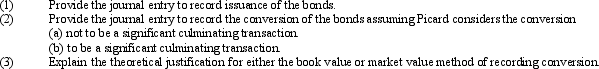
(69) On January 2, 2006, Picard Enterprises issued $2,400,000 of 8 percent, 15-year semiannual coupon bonds to yield 7.5 percent. Each bond is convertible into 40 shares of $15 par common stock, which was trading at $20 per share on the date of the bond issue. The bonds were issued at 106. Without the conversion feature, the bonds would have been issued for 104.5.
On January 3, 2011, all of the bonds were converted into common stock. The market price of the stock was $28 per share on the date of conversion. The issue premium is amortized using the straight-line method.
(Essay)
4.9/5 (74)
(74) On January 1, 2011, Lisbon Corp. issued 2,000 of its 9 percent, $1,000 bonds at 95. Interest is payable semiannually on July 1 and January 1. The bonds mature on January 1, 2021. Lisbon paid bond issue costs of $80,000, which are appropriately recorded as a deferred charge. Lisbon uses the straight-line method of amortizing bond discount and bond issue costs. On Lisbon's December 31, 2011, balance sheet, how much would be shown as the carrying amount of the bonds payable?
(Multiple Choice)
5.0/5 (85)
(85) When bonds are sold between interest dates, any accrued interest is credited to
(Multiple Choice)
5.0/5 (82)
(82) If a $1,000, 9 percent, 10-year bond was issued at 96 plus accrued interest one month after the authorization date, how much cash was received by the issuer?
(Multiple Choice)
4.9/5 (57)
(57) During the year, Hancock Corporation incurred the following costs in connection with the issuance of bonds:
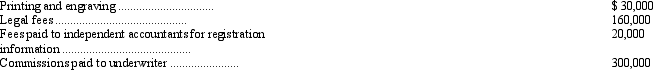 The amount recorded as a deferred charge to be amortized over the term of the bonds is
 (Multiple Choice)
4.8/5 (80)
(80) The net amount required to retire a bond before maturity (assuming no call premium and constant interest rates) is the
(Multiple Choice)
4.8/5 (71)
(71) On July 1, 2005 Cooper Corporation issued for $960,000 one thousand of its 9 percent, $1,000 callable bonds. The bonds are dated July 1, 2005, and mature on July 1, 2015. Interest is payable semiannually on January 1 and July 1. Cooper uses the straight-line method of amortizing bond discount. The bonds can be called by the issuer at 101 at any time after June 30, 2010. On July 1, 2011, Cooper called in all of the bonds and retired them. Ignoring income taxes, how much loss should Cooper report on this early extinguishment of debt for the year ended December 31, 2011?
(Multiple Choice)
4.9/5 (96)
(96) On January 1, 2011, Felipe Hospital issued a $250,000, 10 percent, 5-year bond for $231,601. Interest is payable on June 30 and December 31. Felipe uses the effective-interest method to amortize all premiums and discounts. Assuming an effective interest rate of 12 percent, how much interest expense should be recorded on June 30, 2011?
(Multiple Choice)
4.9/5 (84)
(84) The effective interest rate on bonds is lower than the stated rate when bonds sell
(Multiple Choice)
4.9/5 (66)
(66) On December 31, 2011, Carlton Corporation's current liabilities total $50,000 and long-term liabilities total $150,000. Working capital at December 31, 2011, is equal to $80,000. If Carlton Corporation's debt-to-equity ratio is .32 to 1, total long-term assets must equal
(Multiple Choice)
4.9/5 (77)
(77) On May 1, 2010, J. Cumming acquired $300,000 of Carpenter Enterprises 12 percent bonds due in five years with interest payable semiannually on May 1 and November. The bonds were purchased at $323,165--a price to return 10 percent on the investment. On November 1, 2010, and May 1, 2011, Cumming collected the interest on the bonds. On August 1, 2011, Cumming sold the bonds at 107 plus accrued interest.
Rounding figures to the nearest dollar, provide the entries required to record the:
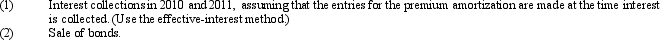
(Essay)
4.7/5 (78)
(78) Accrued interest on bonds that are sold between interest dates
(Multiple Choice)
4.8/5 (67)
(67) On January 1, 2011, Williams Company lent $17,800 cash to Stone Company. The promissory note made by Stone for $20,000 did not bear explicit interest and was due on December 31, 2013. No other rights or privileges were exchanged. The prevailing interest rate for a loan of this type was six percent.
Assume that the present value of $1 for two periods at six percent is .89. Stone should recognize interest expense in 2011 of
(Multiple Choice)
4.9/5 (81)
(81) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)