



 Chat with AI
Exam 6: Earnings Management

Exam 1: Financial Reporting86 Questions
Exam 2: A Review of the Accounting Cycle94 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements72 Questions
Exam 4: The Income Statement82 Questions
Exam 5: Statement of Cash Flows and Articulation79 Questions
Exam 6: Earnings Management46 Questions
Exam 7: The Revenuereceivablescash Cycle81 Questions
Exam 8: Revenue Recognition74 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing103 Questions
Exam 13: Equity Financing88 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases80 Questions
Exam 16: Income Taxes77 Questions
Exam 17: Employee Compensation-Payroll, Pensions, Other Comp Issues78 Questions
Exam 18: Earnings Per Share78 Questions
Exam 19: Derivatives, Contingencies, Business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections74 Questions
Exam 21: Statement of Cash Flows Revisited61 Questions
Exam 22: Accounting in a Global Market60 Questions
Exam 23: Analysis of Financial Statements57 Questions
Select questions type


A Company showed a large restructuring charge on its income statement in 2011 and has experienced a constantly rising earnings trend since that time. This would most nearly represent an example of

Free
(Multiple Choice)
4.7/5  (75)
(75) Correct Answer: Verified
C
Most companies that engage in earnings management typically do not go beyond which of the following activities on the earnings management continuum?
Free
(Multiple Choice)
4.9/5 (87)
(87) Correct Answer:Verified
VerifiedA
Which of the following is typically associated with cookie jar reserves?
Free
(Multiple Choice)
4.9/5 (79)
(79) Correct Answer:Verified
VerifiedB
Which of the following organizations has recommended that entities provide a reconciliation to GAAP net income whenever reporting proforma numbers?
(Multiple Choice)
4.7/5 (72)
(72) Excluding some revenues, expenses, gains, losses from the earnings figure calculated using generally accepted accounting principles is an example of
(Multiple Choice)
4.8/5 (70)
(70) You are auditing a company whose management has intentionally made adjustments to various financial statement items that are not in accordance with generally accepted accounting principles. This behavior has occurred over a number of accounting periods. None of the individual adjustments by itself is material and the aggregate effect on the financial statements taken as a whole is immaterial. Top management of the client are aware of these misstatements and consider them part of their strategic management of earnings.
Explain how you as the independent auditor should respond to this situation.
(Essay)
4.7/5 (78)
(78) Net income is a key number for shareholders, creditors, and analysts alike. Indeed, analysts' projections of net income for a company are viewed as a standard a company must achieve for a period of time. Failure to achieve this standard can have devastating effects on a company's stock price and its management.
The importance of net income in the eyes of analysts and others can tempt managers to take steps to ensure that the appropriate level of net income is achieved. The process of manipulated net income to achieve a desired level of earnings is referred to as earnings management.
Required:
List and explain the economic motivations for earnings management.
(Essay)
4.9/5 (73)
(73) Managers of many companies frequently provide a pro forma earnings amount in conjunction with their annual or quarterly earnings calculated in accordance with GAAP. Managers claim that pro forma earnings numbers more fairly reflect a company's performance.
Required:
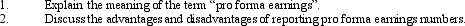
(Essay)
4.8/5 (79)
(79) One of the five techniques of earnings management identified by the Securities and Exchange Commission relates to materiality. Independent auditors have traditionally used arbitrary quantitative benchmarks to define how large an amount must be to be considered material.
During the course of auditing the financial statements of a company, an auditor finds some misstatements in the client's financial statements. When combined, the misstatements, result in a 4% overstatement of net income and a $.02 (4%) overstatement of earnings per share. The auditor's materiality threshold is 5%, that is, an item in the financial statements must be misstated by more than 5% to be considered a material deviation from generally accepted accounting principles. On the basis of the established materiality threshold, the auditor concludes that the deviation from GAAP is immaterial and the accounting is permissible.
Define the term "materiality" and explain whether the auditor is justified in the conclusion that the accounting proposed by the client is permissible.
(Essay)
4.9/5 (69)
(69) Several catastrophic accounting failures have occurred over the last few years. Although the details of each failure is different, each case stems from attempts to manage earnings and thus all of these failures have common elements.
One of the elements identified in these earnings management meltdowns is the auditor's calculated risk.
Explain what is meant by the term "the auditor's calculated risk".
(Essay)
4.9/5 (97)
(97) The following summarized information is available for Central Plains Company at December 31 of the current year:
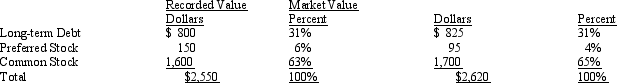 The debt of Central Plains has a before-tax cost rate of 11.5%, preferred stock has a cost of 12.1%, and common equity has a cost of 14.2%. The tax rate for Central Plains is 34%.
Calculate the weighted average cost of capital for Central Plains at December 31 of the current year.
The debt of Central Plains has a before-tax cost rate of 11.5%, preferred stock has a cost of 12.1%, and common equity has a cost of 14.2%. The tax rate for Central Plains is 34%.
Calculate the weighted average cost of capital for Central Plains at December 31 of the current year. (Essay)
4.9/5 (78)
(78) Which of the following items of the earnings management continuum is in the correct order?
(Multiple Choice)
4.8/5 (86)
(86) Which of the following is true regarding the weighted-average cost of capital?
(Multiple Choice)
4.9/5 (86)
(86) The Securities and Exchange Commission (SEC) has the right granted to it by Congress to issue accounting standards. The Commission has exercised this right on a relatively infrequent basis. The SEC is not a passive observer to the financial accounting standard setting process, however.
Explain the general mission of the SEC and how the SEC fulfills its mission as regards financial reporting specifically.
(Essay)
4.8/5 (77)
(77) The practice of carefully timing the recognition of revenues and expenses to even out the amount of reported earnings from one year to the next is called
(Multiple Choice)
4.8/5 (92)
(92) Research has shown that numerous companies manage their earnings. A variety of earnings management techniques are available ranging from income smoothing to outright fraud.
Define income smoothing and explain how it is implemented.
(Essay)
4.9/5 (70)
(70) Recent accounting scandals suggest the need for care on the part of an independent auditor in accepting new clients. The independent auditor needs to know both the business of and the personnel employed by a prospective client. All other control procedures are fruitless if a CPA chooses to serve an undesirable client. The damage suffered as a result of associating with an undesirable client can be irreparable.
Discuss some key issues an independent auditor should consider in the client acceptance decision.
(Essay)
4.8/5 (88)
(88) Recent accounting scandals have raised concerns over the quality and transparency of financial accounting and reporting in the United States. Critics of what is termed the "rules-based" system currently used in the U.S. cite the increasingly detailed and complex nature of rule-driven accounting pronouncements. These critics suggest that the United States should adopt a principles-based system similar to that of the International Accounting Standards Board.
Explain what is meant by a principles-based system and the advantages and disadvantages of such a system.
(Essay)
4.8/5 (67)
(67) Which of the following services offered by investment firms have some states declared to be incompatible with generating forecasts of company earnings?

(Multiple Choice)
4.7/5 (79)
(79) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)