



 Chat with AI
Exam 12: Debt Financing

Exam 1: Financial Reporting86 Questions
Exam 2: A Review of the Accounting Cycle94 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements72 Questions
Exam 4: The Income Statement82 Questions
Exam 5: Statement of Cash Flows and Articulation79 Questions
Exam 6: Earnings Management46 Questions
Exam 7: The Revenuereceivablescash Cycle81 Questions
Exam 8: Revenue Recognition74 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing103 Questions
Exam 13: Equity Financing88 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases80 Questions
Exam 16: Income Taxes77 Questions
Exam 17: Employee Compensation-Payroll, Pensions, Other Comp Issues78 Questions
Exam 18: Earnings Per Share78 Questions
Exam 19: Derivatives, Contingencies, Business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections74 Questions
Exam 21: Statement of Cash Flows Revisited61 Questions
Exam 22: Accounting in a Global Market60 Questions
Exam 23: Analysis of Financial Statements57 Questions
Select questions type


Miller Enterprises had the following long-term debt:
 The total of the serial bonds amounted to
 (Multiple Choice)
4.8/5  (75)
(75) On December 31, 2011, Roberts Corporation's current liabilities total $60,000 and long-term liabilities total $160,000. Working capital at December 31, 2011, is equal to $90,000. If Roberts Corporation's debt-to-equity ratio is .40 to 1, total long-term assets must equal
(Multiple Choice)
4.9/5 (82)
(82) Kiyabu County issued a $500,000, 10 percent, 10-year bond on January 1, 2011, for 113.6 when the effective interest rate was 8 percent. Interest is payable on June 30 and December 31. Kiyabu uses the effective-interest method to amortize all premiums and discounts.
How much interest expense should Kiyabu record on December 31, 2011?
(Multiple Choice)
4.8/5 (75)
(75) Kiyabu County issued a $500,000, 10 percent, 10-year bond on January 1, 2011, for 113.6 when the effective interest rate was 8 percent. Interest is payable on June 30 and December 31. Kiyabu uses the effective-interest method to amortize all premiums and discounts.
How much premium or discount should be amortized on June 30, 2011?
(Multiple Choice)
4.8/5 (80)
(80) On July 1, 2011, Riviera Manufacturing Co. issued a five-year note payable with a face amount of $250,000 and an interest rate of 10 percent. The terms of the note require Riviera to make five annual payments of $50,000 plus accrued interest, with the first payment due June 30, 2012. With respect to the note, the current liabilities section of Riviera's December 31, 2011, balance sheet should include
(Multiple Choice)
4.9/5 (82)
(82) The Financial Accounting Standards Board issued Statement of Financial Accounting Standard No. 133, "Accounting for Derivatives and Hedging Activities," as part of its project on financial instruments and its effort to deal with off-balance-sheet financing.
Explain what is meant by the term "off-balance-sheet financing" and give two reasons why "off-balance-sheet financing" is attractive to the management of an enterprise.
(Essay)
4.8/5 (81)
(81) The market price of a bond issued at a discount is the present value of its principal amount at the market (effective) rate of interest
(Multiple Choice)
4.8/5 (65)
(65) Included in Kaiser Corporation's liability account balances at December 31, 2011, were the following:
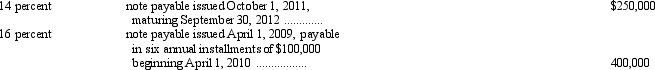 Kaiser's December 31, 2011, financial statements were issued on March 31, 2012. On January 15, 2012, the entire $400,000 balance of the 16 percent note was refinanced by issuance of a long-term obligation payable in a lump sum. In addition, on March 10, 2012, Kaiser consummated a noncancelable agreement with the lender to refinance the 14 percent, $250,000 note on a long-term basis, on readily determinable terms that have not yet been implemented. Both parties are financially capable of honoring the agreement, and there have been no violations of the agreement's provisions. On the December 31, 2011, balance sheet, the amount of the notes payable that Kaiser should classify as noncurrent obligations is
 (Multiple Choice)
5.0/5 (80)
(80) Assuming the straight-line method of amortization is used, the average yearly interest expense on a $250,000, 11 percent, 20-year bond issued at 94 would be
(Multiple Choice)
4.8/5 (89)
(89) RCM Corporation, a calendar-year firm, is authorized to issue $200,000 of 10 percent, 20-year bonds dated January 1, 2011, with interest payable on January 1 and July 1 of each year. If the bonds were issued to yield 12 percent, the entry to account for the discount amortization and accrual of interest on December 31, 2011, would include a
(Multiple Choice)
4.8/5 (71)
(71) When interest expense is calculated using the effective-interest amortization method, interest expense (assuming that interest is paid annually) always equals the
(Multiple Choice)
4.9/5 (78)
(78) When bonds are redeemed by the issuer prior to their maturity date, any gain or loss on the redemption, if material, is
(Multiple Choice)
4.9/5 (78)
(78) The effective interest rate on bonds is higher than the stated rate when bonds sell
(Multiple Choice)
4.8/5 (72)
(72) The annual interest expense on a $50,000, 15-year, 10 percent bond issued for $45,650 plus accrued interest 6 months after authorization, assuming straight-line amortization, would be
(Multiple Choice)
4.7/5 (77)
(77) The globalization of business has caused many changes in how enterprises are managed. One such change is illustrated by U.S. enterprises obtaining loans denominated in foreign currencies.
Identify reasons why such borrowings may occur.
(Essay)
4.8/5 (62)
(62) The total interest expense on a $200,000, 10 percent, 10-year bond issued at 95 would be
(Multiple Choice)
4.7/5 (76)
(76) RCM Corporation, a calendar-year firm, is authorized to issue $200,000 of 10 percent, 20-year bonds dated January 1, 2011, with interest payable on January 1 and July 1 of each year.
If the bonds were issued at 97 on April 1, 2011, plus accrued interest, the amount of cash received by RCM Corporation would be
(Multiple Choice)
4.9/5 (86)
(86) If a $1,000, 9 percent, 10-year bond was issued at 103 plus accrued interest one month after the authorization date, how much cash did the issuer receive?
(Multiple Choice)
4.8/5 (78)
(78) Which of the following does not meet the FASB's definition of a liability?
(Multiple Choice)
4.9/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)