



 Chat with AI
Exam 16: Income Taxes

Exam 1: Financial Reporting86 Questions
Exam 2: A Review of the Accounting Cycle94 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements72 Questions
Exam 4: The Income Statement82 Questions
Exam 5: Statement of Cash Flows and Articulation79 Questions
Exam 6: Earnings Management46 Questions
Exam 7: The Revenuereceivablescash Cycle81 Questions
Exam 8: Revenue Recognition74 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing103 Questions
Exam 13: Equity Financing88 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases80 Questions
Exam 16: Income Taxes77 Questions
Exam 17: Employee Compensation-Payroll, Pensions, Other Comp Issues78 Questions
Exam 18: Earnings Per Share78 Questions
Exam 19: Derivatives, Contingencies, Business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections74 Questions
Exam 21: Statement of Cash Flows Revisited61 Questions
Exam 22: Accounting in a Global Market60 Questions
Exam 23: Analysis of Financial Statements57 Questions
Select questions type


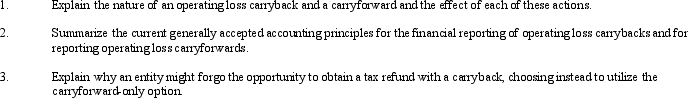
The Internal Revenue Code allows a corporation to carry back or carry forward an operating loss occurring in a given year.
Required:
(Essay)
4.8/5  (70)
(70) Which of the following temporary differences ordinarily results in a deferred tax liability?
(Multiple Choice)
4.8/5 (80)
(80) An example of a "deductible temporary difference" occurs when
(Multiple Choice)
4.7/5 (81)
(81) If all temporary differences entering into the determination of pretax accounting income are considered in the computation of deferred taxes and income tax expense, then the
(Multiple Choice)
4.8/5 (75)
(75) During a year, Great Northern Company reported income tax expense of $200,000. The amount of taxes currently payable remained unchanged from the beginning to the end of the year. The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes, increased from $40,000 at the beginning of the year to $44,000 at the end of the year. How much cash was paid for income taxes during for the year?
(Multiple Choice)
4.8/5 (77)
(77) Frey Corporation's income statement for the year ended December 31, 2011, shows pretax income of $1,000,000. The following items are treated differently on the tax return and in the accounting records:
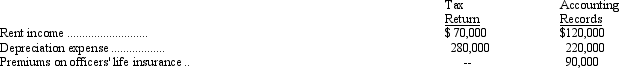 Assume that Frey's tax rate for 2011 is 30 percent. What is the amount of income tax payable for 2011?
 (Multiple Choice)
4.9/5 (80)
(80) Which factor would most likely cause a firm to choose the carryforward option for an NOL?
(Multiple Choice)
4.9/5 (85)
(85) Schaeffer Products, Inc., reported an excess of warranty expense over warranty deductions of $72,000 for the year ended December 31, 2011. This temporary difference will reverse in equal amounts over the years 2012 to 2014. The enacted tax rates are as follows:
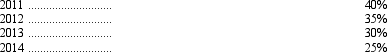 The reporting for this temporary difference at December 31, 2011, would be a
 (Multiple Choice)
5.0/5 (81)
(81) On December 31, 2010, Alton, Inc., reported a current deferred tax liability of $140,000 and a noncurrent deferred tax asset of $40,000. At the end of 2011, Alton reported a current deferred tax liability of $100,000, and a noncurrent deferred tax liability of $44,000. The deferred tax expense for 2011 is
(Multiple Choice)
4.8/5 (76)
(76) In 2011, The Worf Company, reported pretax financial income of $500,000. Included in that pretax financial income was $90,000 of nontaxable life insurance proceeds received as a result of the death of an officer; $120,000 of warranty expenses accrued but unpaid as of December 31, 2011; and $20,000 of life insurance premiums for a policy for an officer. Assuming that no income taxes were previously paid during the year and assuming an income tax rate of 40 percent, the amount of income taxes payable on December 31, 2011, would be
(Multiple Choice)
4.8/5 (94)
(94) A company would most likely choose the carryforward option for a net operating loss if the company expected
(Multiple Choice)
4.9/5 (70)
(70) For the current year, Northern Pacific Company reported income tax expense of $45,000. Income taxes payable at the end of the prior year were $20,000 and at the end of the current year were $27,000. The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes increased from $18,000 at the beginning of the current year to $23,000 at the end of the current year. How much cash was paid for income taxes during the year?
(Multiple Choice)
4.8/5 (79)
(79) A major conceptual issue associated with interperiod tax allocation is the issue of discounting the deferred tax amount on the balance sheet to reflect its present value. Current generally accepted accounting principles do not allow the discounting of deferred taxes. Some in the profession have suggested, however, that the FASB should reconsider its position on discounting in light of the Board's current project on present value-based measurements in accounting.
Provide arguments for and against the discounting of deferred income taxes.
(Essay)
4.9/5 (76)
(76) The application of SFAS No. 109 results in the recording on the financial statements of an enterprise of deferred tax assets and liabilities. The initial identification of these deferred tax assets and liabilities raises the issue as to how these amounts should be shown on the balance sheet in terms of current and noncurrent classifications. One approach advocated by some in the profession is to classify all deferred taxes as noncurrent.
Required:
Explain the advantages and disadvantages of this approach and indicate if this approach is acceptable under SFAS No. 109.
(Essay)
4.9/5 (90)
(90) Many non-accountants are confused when they hear that company has a tax refund of $2,000, but reported an income tax expense of $5,000. These individuals believe such a situation results from companies keeping two sets of books. They further believe that keeping two sets of books is illegal and should be prohibited.
Required:
1. Do companies keep two sets of books and, if they do, is this illegal?
2. How can a company have a tax refund when it also reports an income tax expense?
(Essay)
4.8/5 (82)
(82) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)