



 Chat with AI
Exam 16: Income Taxes

Exam 1: Financial Reporting86 Questions
Exam 2: A Review of the Accounting Cycle94 Questions
Exam 3: The Balance Sheet and Notes to the Financial Statements72 Questions
Exam 4: The Income Statement82 Questions
Exam 5: Statement of Cash Flows and Articulation79 Questions
Exam 6: Earnings Management46 Questions
Exam 7: The Revenuereceivablescash Cycle81 Questions
Exam 8: Revenue Recognition74 Questions
Exam 9: Inventory and Cost of Goods Sold121 Questions
Exam 10: Investments in Noncurrent Operating Assets-Acquisition88 Questions
Exam 11: Investments in Noncurrent Operating Assets-Utilization and Retirement84 Questions
Exam 12: Debt Financing103 Questions
Exam 13: Equity Financing88 Questions
Exam 14: Investments in Debt and Equity Securities81 Questions
Exam 15: Leases80 Questions
Exam 16: Income Taxes77 Questions
Exam 17: Employee Compensation-Payroll, Pensions, Other Comp Issues78 Questions
Exam 18: Earnings Per Share78 Questions
Exam 19: Derivatives, Contingencies, Business Segments, and Interim Reports79 Questions
Exam 20: Accounting Changes and Error Corrections74 Questions
Exam 21: Statement of Cash Flows Revisited61 Questions
Exam 22: Accounting in a Global Market60 Questions
Exam 23: Analysis of Financial Statements57 Questions
Select questions type


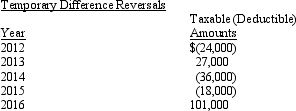
Halverson Company reported taxable income of $60,000 for 2011, its first year of operations. This amount reflects temporary differences between financial and taxable income that are scheduled to reverse in subsequent years as shown below. As of December 31, 2011, the enacted tax rate for 2011 and future years was 40 percent.
(Essay)
4.9/5  (86)
(86) Begal Corporation paid $20,000 in January of 2011 for premiums on a two- year life insurance policy which names the company as the beneficiary. Additionally, Begal Corporation's financial statements for the year ended December 31, 2011, revealed the company paid $105,000 in taxes during the year and also accrued estimated litigation losses of $200,000. Assuming the lawsuit was resolved in February of 2012 (at which time a $200,000 loss was recognized for tax purposes) and that Begal's tax rate is 30 percent for both 2011 and 2012, what amount should Begal report as asset for net deferred income taxes on its 2011 balance sheet?
(Multiple Choice)
4.8/5 (76)
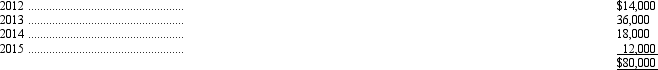
(76) Radford Appliances computed a pretax financial loss of $60,000 for the first year of its operations ended December 31, 2011. Analysis of the tax and book basis of its liabilities disclosed $80,000 in accrued warranty expenses on the books that had not been deductible from taxable income in 2011, but would be deductible in future years when the warranty expenses were paid.
The future warranty payments are expected to occur in the following pattern:
 The enacted tax rates for this year and the next four years are as follows:
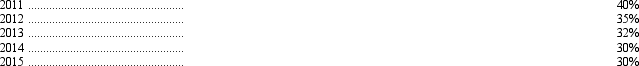 Use the provisions of FASB Statement No. 109.
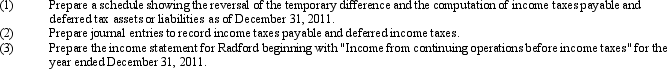
The enacted tax rates for this year and the next four years are as follows:
Use the provisions of FASB Statement No. 109.
(Essay)
4.8/5 (82)
(82) Inventive Corporation's income statement for the year ended December 31, 2011, shows pretax income of $300,000. The following items are treated differently on the tax return and in the accounting records:
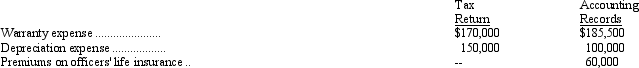 Assume that Inventive's tax rate for 2011 is 40 percent. What is the current portion of Inventive's total income tax expense for 2011?
 (Multiple Choice)
4.8/5 (75)
(75) Warren Corporation began operations in 2008 and had operating losses of $400,000 in 2009 and $300,000 in 2010. For the year ended December 31, 2011, Warren had a pretax financial income of $600,000. For 2009 and 2010, assume an enacted tax rate of 30 percent, and for 2011 a 35 percent tax rate. There were no temporary differences in any of the years. In Warren's 2011 income statement, how much should be reported as income tax expense?
(Multiple Choice)
4.8/5 (92)
(92) In computing the change in deferred tax accounts, which of the following tax rates is used?
(Multiple Choice)
4.9/5 (80)
(80) The data shown below represent the complete taxable income history for Union Corporation. The tax rate was 30% throughout the entire period 2005 through 2012:
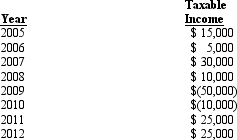 If the company always chooses the carryback, carryforward option, what is the tax liability for 2011?
 (Multiple Choice)
4.9/5 (88)
(88) SFAS No. 109 rejected the approach of its predecessor SFAS No. 96 regarding the classification of deferred tax assets and liabilities on the balance sheet. SFAS No. 96 required that the deferred tax consequences of temporary differences that will result in taxable or deductible amounts during the following year or operating cycle (if longer than one year) be classified as current. SFAS No. 109 requires that deferred tax assets and liabilities be classified based on the asset or liability to which the temporary difference relates or, if no clear relationship between the temporary difference and an asset or liability can be established, based on the date on which the deferred tax item will be realized or settled.
Required:
Explain why the FASB rejected the approach in SFAS No. 96 and the basis for the method required in SFAS No. 109.
(Essay)
4.9/5 (96)
(96) International accounting standards currently are moving toward the
(Multiple Choice)
4.7/5 (96)
(96) Which of the following does not help explain why income tax expense is different from the product of pretax income times the current tax rate?
(Multiple Choice)
5.0/5 (84)
(84) Eden Company had pretax accounting income of $24,000 during 2011. Eden's only temporary difference for 2008 relates to a sale made in 2009 and recognized for accounting purposes at that time. However, Eden uses the installment sales method of revenue recognition for tax purposes. During 2011 Eden collected a receivable from the 2009 sale which resulted in $6,000 of income under the installment sales method. Eden's taxable income for 2011 would be
(Multiple Choice)
4.8/5 (80)
(80) Alpha Company reported net incomes in 2010 and 2011 before sustaining a significant operating loss in 2012. All of the 2012 loss can be carried back against the income of 2010 and 2011 for purposes of determining the company's 2009 income tax liability. How should the carryback be presented in the company's 2012 financial statements?
(Multiple Choice)
4.8/5 (79)
(79) The asset-liability method of interperiod tax allocation currently required by U.S. GAAP is an example of the
(Multiple Choice)
4.9/5 (73)
(73) Which of the following is the most likely item to result in a deferred tax asset?
(Multiple Choice)
4.8/5 (92)
(92) The Gayle Corporation reported a $66,000 operating loss in 2011. In the preceding three years, Gayle reported the following income before taxes and paid the indicated income taxes:
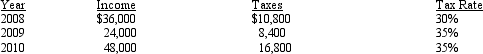 The amount of tax benefit to be reported in 2011 arising from the tax carryback provisions of the current tax code would be
 (Multiple Choice)
5.0/5 (74)
(74) The books of the Tracker Company for the year ended December 31, 2011, showed pretax income of $360,000. In computing the taxable income for federal income tax purposes, the following timing differences were taken into account:
 What should Tracker record as its current federal income tax liability at December 31, 2011, assuming a corporate income tax rate of 30 percent?
 (Multiple Choice)
5.0/5 (81)
(81) Which of the following creates a temporary difference between financial and taxable income?
(Multiple Choice)
4.9/5 (83)
(83) When enacted tax rates change, the asset and liability method of interperiod tax allocation recognizes the rate change as
(Multiple Choice)
4.7/5 (83)
(83) During 2011, Alpha Company had pretax accounting income of $420. Alpha's only temporary difference for 2011 was the collection of a receivable that resulted in $120 of income under the installment sales method of revenue recognition that Alpha uses for tax purposes. The sale was originally made in 2009 and recognized for accounting purposes at that time. Alpha's taxable income for 2011 would be
(Multiple Choice)
4.8/5 (82)
(82) For the current year, Santa Fe Company reported income tax expense of $195,000. Income taxes payable at the end of the prior year were $125,000 and at the end of the current year were $130,000. The deferred tax liability classified as noncurrent that resulted from the use of MACRS for tax purposes and straight-line depreciation for financial reporting purposes increased from $120,000 at the beginning of the current year to $123,000 at the end of the current year. How much cash was paid for income taxes during the year?
(Multiple Choice)
4.8/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)