



 Chat with AI
Exam 11: Perfect Competition

Exam 1: Getting Started347 Questions
Exam 2: The Usand Global Economies211 Questions
Exam 3: The Economic Problem282 Questions
Exam 4: Demand and Supply334 Questions
Exam 5: Elasticities of Demand and Supply342 Questions
Exam 6: Efficiency and Fairness of Markets361 Questions
Exam 7: Government Actions in Markets335 Questions
Exam 8: Global Markets in Action281 Questions
Exam 9: Externalities: Pollution, education, and Health Care297 Questions
Exam 10: Production and Cost274 Questions
Exam 11: Perfect Competition285 Questions
Exam 12: Monopoly384 Questions
Exam 13: Monopolistic Competition and Oligopoly313 Questions
Exam 14: Gdp: a Measure of Total Production and Income263 Questions
Exam 15: Jobs and Unemployment293 Questions
Exam 16: The Cpi and the Cost of Living273 Questions
Exam 17: Potential Gdp and Economic Growth330 Questions
Exam 18: Money and the Monetary System370 Questions
Exam 19: Aggregate Supply and Aggregate Demand313 Questions
Exam 20: Fiscal Policy and Monetary Policy222 Questions
Select questions type


A requirement of perfect competition is that
I.many firms sell an identical product to many buyers.
Ii.there are no restrictions on entry into (or exit from)the market,and established firms have no advantage over new firms.
Iii.sellers and buyers are well informed about prices.
(Multiple Choice)
4.9/5  (84)
(84) The firm in the figure above is ________ that is equal to ________.
(Multiple Choice)
4.9/5 (82)
(82) For a perfectly competitive firm,profit maximization occurs when output is such that
(Multiple Choice)
4.8/5 (85)
(85) 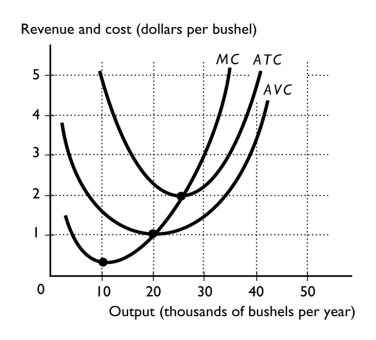 -The above diagram shows the cost curves for a perfectly competitive wheat farmer.At what price(s)does the wheat farmer earn an economic profit? Earn a normal profit? Incur an economic loss? How many bushels of wheat does the farmer produce if the price is $3 per bushel? If the price is $0.50 per bushel?
 (Essay)
4.9/5 (77)
(77) How does a decrease in the demand for wheat ultimately lead to normal profits for wheat growers in the long run?
(Essay)
4.9/5 (91)
(91) A firm maximizes its profit by producing the amount of output such that
(Multiple Choice)
4.9/5 (77)
(77) What is the shape of the demand curve faced by the perfectly competitive firm,and why?
(Essay)
4.9/5 (68)
(68) A market is initially in a long-run equilibrium and there is a permanent increase in demand.After the new long-run equilibrium is reached,there
(Multiple Choice)
4.9/5 (77)
(77) For the perfectly competitive broccoli producers in California,the market demand curve for broccoli is
(Multiple Choice)
4.9/5 (93)
(93)  -The above table has the total revenue and total cost schedule for Omar,a perfectly competitive grower of rutabagas.When Omar produces 2 bushels of rutabagas,his total profit equals
 (Multiple Choice)
4.8/5 (66)
(66) As a perfectly competitive firm produces more and more of a good,its economic profit
(Multiple Choice)
4.8/5 (70)
(70) If the market price is $50 for a unit of a good produced in a perfectly competitive market and the firm's minimum average variable cost is $52,then to maximize its profit (or minimize its loss)the firm should
(Multiple Choice)
4.8/5 (91)
(91) If the technology associated with producing fiber-optic cable continues to advance,over time the cost of producing fiber-optic cable will
(Multiple Choice)
4.7/5 (66)
(66) Entry by competitive firms decreases the market price,while exit by competitive firms increases the market price.Explain why firms enter or exit an industry and why these price changes occur.
(Essay)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)