



 Chat with AI
Exam 11: Perfect Competition

Exam 1: Getting Started347 Questions
Exam 2: The Usand Global Economies211 Questions
Exam 3: The Economic Problem282 Questions
Exam 4: Demand and Supply334 Questions
Exam 5: Elasticities of Demand and Supply342 Questions
Exam 6: Efficiency and Fairness of Markets361 Questions
Exam 7: Government Actions in Markets335 Questions
Exam 8: Global Markets in Action281 Questions
Exam 9: Externalities: Pollution, education, and Health Care297 Questions
Exam 10: Production and Cost274 Questions
Exam 11: Perfect Competition285 Questions
Exam 12: Monopoly384 Questions
Exam 13: Monopolistic Competition and Oligopoly313 Questions
Exam 14: Gdp: a Measure of Total Production and Income263 Questions
Exam 15: Jobs and Unemployment293 Questions
Exam 16: The Cpi and the Cost of Living273 Questions
Exam 17: Potential Gdp and Economic Growth330 Questions
Exam 18: Money and the Monetary System370 Questions
Exam 19: Aggregate Supply and Aggregate Demand313 Questions
Exam 20: Fiscal Policy and Monetary Policy222 Questions
Select questions type


The firm in the figure above has a total cost equal to ________.
(Multiple Choice)
4.7/5  (76)
(76) If a perfectly competitive firm manufacturing chairs produces 100 more chairs,what happens to the market price of a chair?
(Essay)
4.8/5 (75)
(75) If there are 1,000 identical rice farmers who are each willing to supply 200 bushels of rice at $2 per bushel,what price and quantity combination is a point on the market supply curve for rice?
(Multiple Choice)
4.8/5 (87)
(87) The market supply in the short run for the perfectly competitive industry is
(Multiple Choice)
4.8/5 (73)
(73) 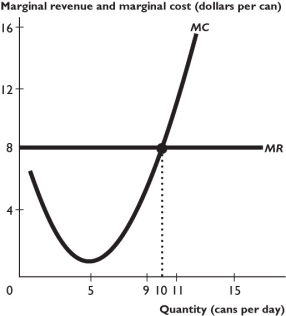 The figure above shows a firm's marginal revenue and marginal cost curves.
-Based on the figure above,the price of a can is $8;if the price increased to $12,then the firm would
The figure above shows a firm's marginal revenue and marginal cost curves.
-Based on the figure above,the price of a can is $8;if the price increased to $12,then the firm would (Multiple Choice)
4.8/5 (86)
(86) Suppose the price of a can was $5.10.In this case,to maximize its profit,the firm illustrated in the figure above would
(Multiple Choice)
4.8/5 (76)
(76) Technological change allows perfectly competitive firms to ________ and leads to ________.
(Multiple Choice)
4.9/5 (75)
(75) 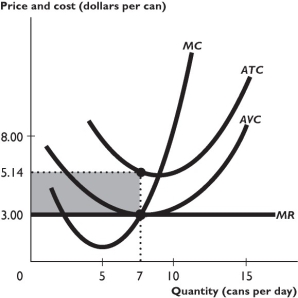 The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above,if the firm produces 7 cans per day,the firm ________ maximizing its profit and is ________.
The above figure shows some a firm's cost curves and its marginal revenue curve.
-Based on the figure above,if the firm produces 7 cans per day,the firm ________ maximizing its profit and is ________. (Multiple Choice)
4.8/5 (93)
(93) 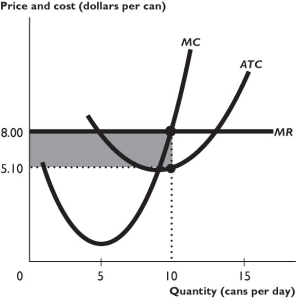 The figure above shows some of a firm's cost curves and its marginal revenue curve.
-Based on the figure above,if the firm produces 10 cans per day,the firm ________ maximizing its profit and is ________.
The figure above shows some of a firm's cost curves and its marginal revenue curve.
-Based on the figure above,if the firm produces 10 cans per day,the firm ________ maximizing its profit and is ________. (Multiple Choice)
4.8/5 (59)
(59) If perfectly competitive firms are making an economic profit,then
(Multiple Choice)
4.9/5 (73)
(73) Does a perfectly competitive producer have any incentive to lower its price so it is below the current market price? Explain your answer
(Essay)
4.8/5 (63)
(63) 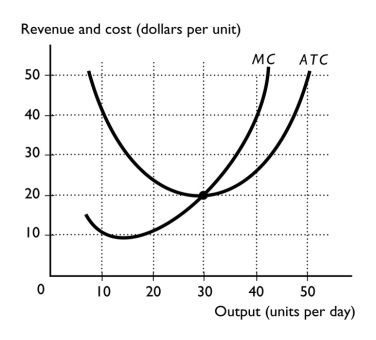 -The figure above shows a perfectly competitive firm.If the market price is $40 per unit,then the firm produces ________ units and makes an economic profit that is ________.
 (Multiple Choice)
4.9/5 (78)
(78) A perfectly competitive firm is producing 50 units of output and selling at the market price of $23.The firm's average total cost is $20.What is the firm's total cost?
(Multiple Choice)
4.8/5 (96)
(96) The marginal revenue curve for a perfectly competitive firm is
(Multiple Choice)
4.8/5 (80)
(80) 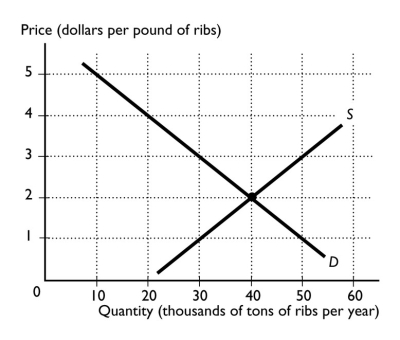
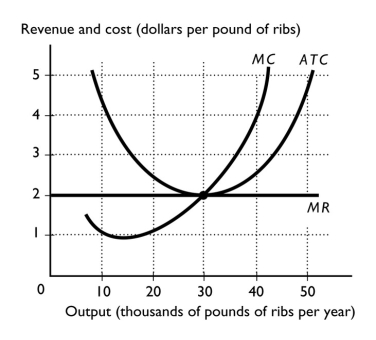 -American restaurants receive their supply of baby back-ribs from American farms and from farms in Denmark.In the figures above,the left diagram shows the perfectly competitive market for baby back ribs in the United States.The right figure shows the situation at Premium Standard Farm in Kansas,one of the many U.S.farms supplying these ribs.
Now assume that the United States imposes a ban on European meat in response to the foot-and-mouth disease that has infected livestock in Europe.(Which the United States did a few years ago. )In particular,suppose that the U.S.ban decreases the supply by 40 tons a year.Using the figure on the left,show the impact of this ban on the baby back rib market.Using the figure on the right,show the impact on Premium Standard Farm in Kansas.
-American restaurants receive their supply of baby back-ribs from American farms and from farms in Denmark.In the figures above,the left diagram shows the perfectly competitive market for baby back ribs in the United States.The right figure shows the situation at Premium Standard Farm in Kansas,one of the many U.S.farms supplying these ribs.
Now assume that the United States imposes a ban on European meat in response to the foot-and-mouth disease that has infected livestock in Europe.(Which the United States did a few years ago. )In particular,suppose that the U.S.ban decreases the supply by 40 tons a year.Using the figure on the left,show the impact of this ban on the baby back rib market.Using the figure on the right,show the impact on Premium Standard Farm in Kansas. (Essay)
4.8/5 (80)
(80) Describe how economic losses are eliminated in a perfectly competitive industry.
(Essay)
4.8/5 (77)
(77) If a perfectly competitive firm raised the price of its product,
(Multiple Choice)
4.9/5 (80)
(80) Firms exit a competitive market when they incur an economic loss.In the long run,this exit means that the economic losses of the surviving firms
(Multiple Choice)
4.9/5 (86)
(86) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)