



 Chat with AI
Exam 12: Systematic Risk and the Equity Risk Premium

Exam 1: Corporate Finance and the Financial Manager86 Questions
Exam 2: Introduction to Financial Statement Analysis106 Questions
Exam 3: Time Value of Money: an Introduction112 Questions
Exam 4: Time Value of Money: Valuing Cash Flow Streams62 Questions
Exam 5: Interest Rates109 Questions
Exam 6: Bonds109 Questions
Exam 7: Stock Valuation63 Questions
Exam 8: Investment Decision Rules124 Questions
Exam 9: Fundamentals of Capital Budgeting111 Questions
Exam 10: Stock Valuation: a Second Look48 Questions
Exam 11: Risk and Return in Capital Markets110 Questions
Exam 12: Systematic Risk and the Equity Risk Premium103 Questions
Exam 13: The Cost of Capital110 Questions
Exam 14: Raising Equity Capital110 Questions
Exam 15: Debt Financing99 Questions
Exam 16: Capital Structure109 Questions
Exam 17: Payout Policy110 Questions
Exam 18: Financial Modeling and Pro Forma Analysis95 Questions
Exam 19: Working Capital Management110 Questions
Exam 20: Short-Term Financial Planning108 Questions
Exam 21: Option Applications and Corporate Finance102 Questions
Exam 22: Mergers and Acquisitions47 Questions
Exam 23: International Corporate Finance108 Questions
Exam 24: Leasing46 Questions
Exam 25: Insurance and Risk Management38 Questions
Exam 26: Corporate Governance45 Questions
Select questions type


Since total risk is greater than systematic risk, should standard deviation be always greater than beta?
(Essay)
4.9/5  (80)
(80) Consider the following expected returns, volatilities, and correlations:
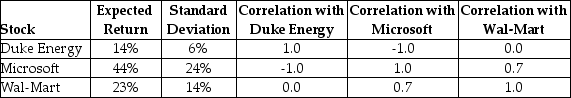 The volatility of a portfolio that is equally invested in Duke Energy and Microsoft is closest to ________.
 (Multiple Choice)
4.8/5 (89)
(89) A portfolio has three stocks - 300 shares of Yahoo (YHOO), 300Shares of General Motors (GM), and 80 shares of Standard and Poor's Index Fund (SPY). If the price of YHOO is $20, the price of GM is $30, and the price of SPY is $150, calculate the portfolio weight of YHOO and GM.
(Multiple Choice)
4.8/5 (83)
(83) Your retirement portfolio comprises 200 shares of the S&P 500 fund (SPY) and 100 shares of iShares Barclays Aggregate Bond Fund (AGG). The price of SPY is $134 and that of AGG is $110. If you expect the return on SPY to be 10% in the next year and the return on AGG to be 8%, what is the expected return for your retirement portfolio?
(Multiple Choice)
4.8/5 (79)
(79) The systematic risk (beta) of a portfolio will ________ by holding more stocks, even if they each had the same systematic risk.
(Multiple Choice)
4.9/5 (75)
(75) Consider the following returns:
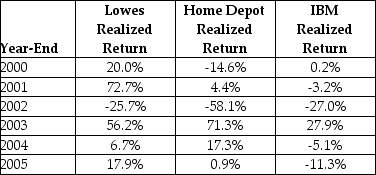 The volatility on Lowes' returns is closest to ________.
 (Multiple Choice)
4.8/5 (72)
(72) If you build a large enough portfolio, you can diversify away all ________ risk, but you will be left with ________ risk.
(Multiple Choice)
4.9/5 (81)
(81) The S&P 500 index traditionally is a(n) ________ portfolio of the 500 largest U.S. stocks.
(Multiple Choice)
4.9/5 (84)
(84) A portfolio has 30% of its value in IBM shares and the rest in Microsoft (MSFT). The volatility of IBM and MSFT are 35% and 30%, respectively, and the correlation between IBM and MSFT is 0.5. What is the standard deviation of the portfolio?
(Multiple Choice)
4.9/5 (69)
(69) How does the S&P 500 index rank in terms of number and market capitalization of U.S. public firms?
(Essay)
4.8/5 (77)
(77) Suppose you invest $20,000 by purchasing 200 shares of Abbott Labs (ABT) at $50 per share, 200 shares of Lowes (LOW) at $30 per share, and 100 shares of Ball Corporation (BLL) at $40 per share. Suppose over the next year Ball has a return of 12.5%, Lowes has a return of 21%, and Abbott Labs has a return of -10%. The return on your portfolio over the year is ________.
(Multiple Choice)
4.9/5 (83)
(83) Your estimate of the market risk premium is 7%. The risk-free rate of return is 4%, and General Motors has a beta of 1.4. According to the Capital Asset Pricing Model (CAPM), what is its expected return?
(Multiple Choice)
4.9/5 (77)
(77) Suppose you invest $22,500 by purchasing 200 shares of Abbott Labs (ABT) at $55 per share, 200 shares of Lowes (LOW) at $35 per share, and 100 shares of Ball Corporation (BLL) at $45 per share. The weight of Abbott Labs in your portfolio is ________.
(Multiple Choice)
4.9/5 (86)
(86) While we are using historic return to estimate a stock's beta, why can't we use historic data to forecast the expected return for the stock?
(Essay)
4.9/5 (77)
(77) Diversification reduces the risk of a portfolio because ________, and some of the risks are averaged out of the portfolio.
(Multiple Choice)
4.9/5 (71)
(71) The price of Microsoft is $25 per share and that of Apple is $50 per share. The price of Microsoft increases to $36 per share after one year and to $41 after two years. Also, shares of Apple increase to $56 after one year and to $66 after two years. If your portfolio comprises 100 shares of each security, what is your portfolio return over year 1 and year 2? Assume no dividends are paid.
(Multiple Choice)
4.9/5 (90)
(90) For each 1% change in the market portfolio's excess return, the investment's excess return is expected to change by ________ due to risks that it has in common with the market.
(Multiple Choice)
4.9/5 (87)
(87) What is the lowest risk possible by selecting two stocks that are perfectly negatively correlated?
(Essay)
4.9/5 (71)
(71) Consider the following expected returns, volatilities, and correlations:
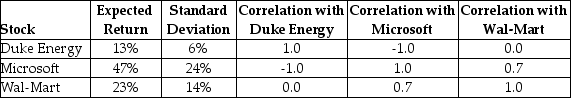 The expected return of a portfolio that is equally invested in Duke Energy and Microsoft is closest to ________.
 (Multiple Choice)
4.8/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)