



 Chat with AI
Exam 6: The CPA Profession

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The CPA Profession67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Professional Ethics114 Questions
Exam 5: Legal Liability113 Questions
Exam 6: The CPA Profession114 Questions
Exam 7: Audit Evidence94 Questions
Exam 8: Audit Planning and Analytical Procedures95 Questions
Exam 9: Materiality and Risk102 Questions
Exam 10: Section 404 Audits of Internal Control and Control Risk116 Questions
Exam 11: Fraud Auditing83 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions108 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions117 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable96 Questions
Exam 17: Audit Sampling for Tests of Details and Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls and Substantive Tests of Transactions, and Accounts Payable114 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle115 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash Balances92 Questions
Exam 24: Completing the Audit116 Questions
Exam 25: Other Assurance Services100 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


Briefly explain each management assertion related to classes of transactions and events for the period under audit.
(Essay)
4.8/5  (71)
(71) General transaction-related audit objectives vary from audit to audit, depending on the nature and characteristics of the client's business and industry.
(True/False)
4.9/5 (78)
(78) An auditor should recognize that the application of auditing procedures may produce evidence indicating the possibility of errors or fraud and therefore should:
(Multiple Choice)
4.8/5 (78)
(78) Responsibility for the fair presentation of financial statements rests equally with management and the auditor.
(True/False)
4.8/5 (78)
(78) In describing the cycle approach to segmenting an audit, which of the following statements is not true?
(Multiple Choice)
4.8/5 (88)
(88) Which of the following statements about the existence and completeness assertions is not true?
(Multiple Choice)
4.8/5 (83)
(83) Below are five audit procedures, all of which are tests of transactions associated with the audit of the acquisition and payment cycle. Also below are the six general transaction-related audit objectives and the five management assertions. For each audit procedure, indicate (1) its audit objective, and (2) the management assertion being tested.
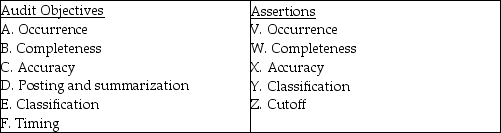 1. Foot the purchases journal and trace the totals to the related general ledger accounts.
(1) ________.
(2) ________.
2. Recompute the cash discounts taken by the client.
(1) ________.
(2) ________.
3. Compare dates on cancelled checks with the bank cancellation date.
(1) ________.
(2) ________.
4. Trace from a sample of cancelled checks to the cash disbursements journal.
(1) ________.
(2) ________.
5. Examine supporting documentation for a sample of transactions for authorized payee and amount and to determine services or goods were received.
(1) ________.
(2) ________.
1. Foot the purchases journal and trace the totals to the related general ledger accounts.
(1) ________.
(2) ________.
2. Recompute the cash discounts taken by the client.
(1) ________.
(2) ________.
3. Compare dates on cancelled checks with the bank cancellation date.
(1) ________.
(2) ________.
4. Trace from a sample of cancelled checks to the cash disbursements journal.
(1) ________.
(2) ________.
5. Examine supporting documentation for a sample of transactions for authorized payee and amount and to determine services or goods were received.
(1) ________.
(2) ________. (Essay)
4.9/5 (79)
(79) The auditor is determining that the recorded sales are for the amount of goods shipped are correctly billed and recorded. She is gathering evidence about which transaction related audit objective?
(Multiple Choice)
4.9/5 (91)
(91) Which of the following statements best describes the auditor's responsibility regarding the detection of fraud?
(Multiple Choice)
4.7/5 (84)
(84) An auditor must inform a client's audit committee of an illegal act discovered during an audit in writing.
(True/False)
4.8/5 (73)
(73) Which of the following is the auditor least likely to do when aware of an illegal act?
(Multiple Choice)
4.7/5 (92)
(92) Match seven of the terms (a-k) with the definitions provided below (1-7):
a. Tests of details of balances
b. Tests of controls
c. Substantive tests of transactions
d. Analytical procedures
e. Transaction-related audit objectives
f. Management assertions
g. Balance-related audit objectives
h. Fraud
i. Illegal act
j. Error
k. Management fraud
________ 1. An intentional misstatement of the financial statements.
________ 2. A set of six audit objectives the auditor must meet, including timing, posting and summarization, and accuracy.
________ 3. Implied or expressed representations made by the client about classes of transactions, account balances and disclosures in the financial statements.
________ 4. Audit procedures testing for monetary misstatements to determine whether the balance-related audit objectives have been satisfied for each significant account balance.
________ 5. A set of nine audit objectives the auditor must meet, including completeness, detail tie-in, and rights and obligations.
________ 6. Audit procedures designed to test the effectiveness of control policies and procedures.
________ 7. Use of comparisons and relationships to assess whether account balances or other data appears reasonable.
(Short Answer)
4.9/5 (98)
(98) The transaction-related audit objective that deals with whether recorded transactions have actually occurred is the completeness objective.
(True/False)
4.7/5 (80)
(80) The auditor's best defense when material misstatements are not uncovered is to have conducted the audit:
(Multiple Choice)
4.8/5 (78)
(78) If the auditor believes that the financial statements are not fairly stated or is unable to reach a conclusion because of insufficient evidence, the auditor:
(Multiple Choice)
4.8/5 (77)
(77) Which of the following management assertions is not associated with transaction-related audit objectives?
(Multiple Choice)
4.8/5 (84)
(84) Fraudulent financial reporting is most likely to be committed by whom?
(Multiple Choice)
4.9/5 (90)
(90) "The auditor should not assume that management is dishonest, but the possibility of dishonesty must be considered." This is an example of:
(Multiple Choice)
4.8/5 (93)
(93) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)