



 Chat with AI
Exam 6: The CPA Profession

Exam 1: The Demand for Audit and Other Assurance Services47 Questions
Exam 2: The CPA Profession67 Questions
Exam 3: Audit Reports139 Questions
Exam 4: Professional Ethics114 Questions
Exam 5: Legal Liability113 Questions
Exam 6: The CPA Profession114 Questions
Exam 7: Audit Evidence94 Questions
Exam 8: Audit Planning and Analytical Procedures95 Questions
Exam 9: Materiality and Risk102 Questions
Exam 10: Section 404 Audits of Internal Control and Control Risk116 Questions
Exam 11: Fraud Auditing83 Questions
Exam 12: The Impact of Information Technology on the Audit Process106 Questions
Exam 13: Overall Audit Plan and Audit Program94 Questions
Exam 14: Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions108 Questions
Exam 15: Audit Sampling for Tests of Controls and Substantive Tests of Transactions117 Questions
Exam 16: Completing the Tests in the Sales and Collection Cycle: Accounts Receivable96 Questions
Exam 17: Audit Sampling for Tests of Details and Balances114 Questions
Exam 18: Audit of the Acquisition and Payment Cycle: Tests of Controls and Substantive Tests of Transactions, and Accounts Payable114 Questions
Exam 19: Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts101 Questions
Exam 20: Audit of the Payroll and Personnel Cycle113 Questions
Exam 21: Audit of the Inventory and Warehousing Cycle115 Questions
Exam 22: Audit of the Capital Acquisition and Repayment Cycle91 Questions
Exam 23: Audit of Cash Balances92 Questions
Exam 24: Completing the Audit116 Questions
Exam 25: Other Assurance Services100 Questions
Exam 26: Internal and Governmental Financial Auditing and Operational Auditing73 Questions
Select questions type


An audit generally provides no assurance that indirect-effect illegal acts will be detected.
(True/False)
4.9/5  (84)
(84) The effect of a violation of the completeness transaction-related audit objective for cash disbursements transactions would be an overstatement of cash disbursements.
(True/False)
4.8/5 (85)
(85) Other than inquiring of management about policies they have established to prevent illegal acts and whether management knows of any laws or regulations that the company has violated, the auditor should not search for indirect-effect illegal acts unless there is reason to believe they may exist.
(True/False)
4.7/5 (80)
(80) In order to provide reasonable assurance the audit must be performed with an attitude of professional skepticism. Which of the following is most correct regarding the "attitude" of professional skepticism?
(Multiple Choice)
4.8/5 (74)
(74) When an auditor believes that an illegal act may have occurred, the first step he or she should take is to gather additional evidence to determine the extent of the illegality.
(True/False)
4.9/5 (70)
(70) Which of the following statements is true of a public company's financial statements?
(Multiple Choice)
4.9/5 (82)
(82) Audits are expected to provide a higher degree of assurance for the detection of material frauds than is provided for an equally material error.
(True/False)
5.0/5 (95)
(95) Auditing standards require that an audit be designed to provide reasonable assurance of detecting:
(Multiple Choice)
4.8/5 (69)
(69) When an auditor has reduced assessed control risk based on tests of controls, he or she may then reduce the extent to which the accuracy of the financial statement information directly related to those controls must be supported through the accumulation of evidence using substantive tests.
(True/False)
4.9/5 (69)
(69) The most important general ledger account included in and affecting several cycles is the:
(Multiple Choice)
4.8/5 (86)
(86) Which of the following would most likely be deemed a direct-effect illegal act?
(Multiple Choice)
4.8/5 (80)
(80) Why does the auditor divide the financial statements into smaller segments?
(Multiple Choice)
4.9/5 (79)
(79) Which of the following journals would be included most often in the various audit cycles?
(Multiple Choice)
4.8/5 (79)
(79) Below are five audit procedures, all of which are tests of transactions associated with the audit of the sales and collection cycle. Also below are the six general transaction-related audit objectives and the five management assertions. For each audit procedure, indicate (1) its audit objective, and (2) the management assertion being tested.
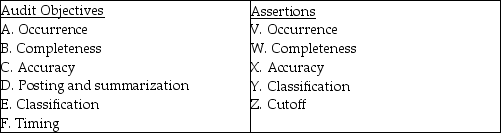 1. Vouch recorded sales from the sales journal to the file of bills of lading.
(1) ________.
(2) ________.
2. Compare dates on the bill of lading, sales invoices, and sales journal to test for delays in recording sales transactions.
(1) ________.
(2) ________.
3. Account for the sequence of prenumbered bills of lading and sales invoices.
(1) ________.
(2) ________.
4. Trace from a sample of prelistings of cash receipts to the cash receipts journal, testing for names, amounts, and dates.
(1) ________.
(2) ________.
5. Examine customer order forms for credit approval by the credit manager.
(1) ________.
(2) ________.
1. Vouch recorded sales from the sales journal to the file of bills of lading.
(1) ________.
(2) ________.
2. Compare dates on the bill of lading, sales invoices, and sales journal to test for delays in recording sales transactions.
(1) ________.
(2) ________.
3. Account for the sequence of prenumbered bills of lading and sales invoices.
(1) ________.
(2) ________.
4. Trace from a sample of prelistings of cash receipts to the cash receipts journal, testing for names, amounts, and dates.
(1) ________.
(2) ________.
5. Examine customer order forms for credit approval by the credit manager.
(1) ________.
(2) ________. (Essay)
4.7/5 (79)
(79) Auditing standards indicate that reasonable assurance is a moderate, but not absolute, level of assurance that the financial statements are free of material misstatement.
B) True
(True/False)
4.8/5 (98)
(98) The transaction-related audit objective of timing is related to the assertion of cutoff.
(True/False)
4.8/5 (68)
(68) In certifying their annual financial statements, the CEO and CFO of a public company certify that the financial statements comply with the requirements of:
(Multiple Choice)
4.9/5 (92)
(92) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)