



 Chat with AI
Exam 2: Shareholders Equity: Share Capital and Reserves

Exam 1: The Conceptual Framework of the Iasb30 Questions
Exam 2: Shareholders Equity: Share Capital and Reserves28 Questions
Exam 3: Fair Value Measurement30 Questions
Exam 4: Revenue30 Questions
Exam 5: Provisions, Contingent Liabilities and Contingent Assets30 Questions
Exam 6: Income Taxes28 Questions
Exam 7: Financial Instruments30 Questions
Exam 8: Share-Based Payments28 Questions
Exam 9: Inventories29 Questions
Exam 10: Employee Benefits29 Questions
Exam 11: Property, Plant and Equipment28 Questions
Exam 12: Leases27 Questions
Exam 13: Intangible Assets28 Questions
Exam 14: Business Combinations30 Questions
Exam 15: Impairment of Assets28 Questions
Exam 16: Accounting for Mineral Resources26 Questions
Exam 17: Agriculture26 Questions
Exam 18: Financial Statement Presentation29 Questions
Exam 19: Statement of Cash Flows28 Questions
Exam 20: Earnings Per Share20 Questions
Exam 21: Operating Segments30 Questions
Exam 22: Operating Segments29 Questions
Exam 23: Consolidation: Controlled Entities29 Questions
Exam 24: Consolidation: Wholly Owned Subsidiaries26 Questions
Exam 25: Consolidation: Intragroup Transactions27 Questions
Exam 26: Consolidation: Non-Controlling Interest25 Questions
Exam 27: Consolidation: Other Issues29 Questions
Exam 28: Translation of the Financial Statements of Foreign Entities28 Questions
Exam 29: Associates and Joint Ventures26 Questions
Exam 30: Joint Arrangements26 Questions
Select questions type


The balance in the retained earnings account is affected by the transfer to that account of:
(Multiple Choice)
4.8/5  (86)
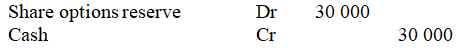
(86) Valdez Limited issued 10 000 share options to subscribe for ordinary shares. The exercise price on the options was $3 per share. If all options were exercised on due date the following journal entry would be recorded:
A) B)
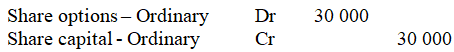 C)
 D)
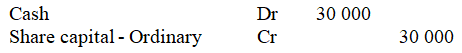
B)
C)
D) (Essay)
4.8/5 (89)
(89) Which of the following is not a reason that companies may undertake a share buy-back?
(Multiple Choice)
4.8/5 (72)
(72) Gains or losses that arise as a result of translating foreign currency denominated operations into the reporting currency are recognised in income:
(Multiple Choice)
4.8/5 (79)
(79) Gains and losses on available-for-sale financial assets are recognised directly in equity until the financial asset is derecognised. At this time the cumulative gain or loss previously recognised is:
(Multiple Choice)
4.9/5 (76)
(76) The bonus issue of shares has the following impact on the equity of a company;
(Multiple Choice)
4.8/5 (71)
(71) IAS 1 Presentation of Financial Statements requires the following items to appear on the face of the Statement of Changes in Equity
(Multiple Choice)
4.9/5 (91)
(91) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)