



 Chat with AI
Exam 9: Inventories

Exam 1: The Conceptual Framework of the Iasb30 Questions
Exam 2: Shareholders Equity: Share Capital and Reserves28 Questions
Exam 3: Fair Value Measurement30 Questions
Exam 4: Revenue30 Questions
Exam 5: Provisions, Contingent Liabilities and Contingent Assets30 Questions
Exam 6: Income Taxes28 Questions
Exam 7: Financial Instruments30 Questions
Exam 8: Share-Based Payments28 Questions
Exam 9: Inventories29 Questions
Exam 10: Employee Benefits29 Questions
Exam 11: Property, Plant and Equipment28 Questions
Exam 12: Leases27 Questions
Exam 13: Intangible Assets28 Questions
Exam 14: Business Combinations30 Questions
Exam 15: Impairment of Assets28 Questions
Exam 16: Accounting for Mineral Resources26 Questions
Exam 17: Agriculture26 Questions
Exam 18: Financial Statement Presentation29 Questions
Exam 19: Statement of Cash Flows28 Questions
Exam 20: Earnings Per Share20 Questions
Exam 21: Operating Segments30 Questions
Exam 22: Operating Segments29 Questions
Exam 23: Consolidation: Controlled Entities29 Questions
Exam 24: Consolidation: Wholly Owned Subsidiaries26 Questions
Exam 25: Consolidation: Intragroup Transactions27 Questions
Exam 26: Consolidation: Non-Controlling Interest25 Questions
Exam 27: Consolidation: Other Issues29 Questions
Exam 28: Translation of the Financial Statements of Foreign Entities28 Questions
Exam 29: Associates and Joint Ventures26 Questions
Exam 30: Joint Arrangements26 Questions
Select questions type


IAS 2 allows which of the following to be capitalised into the cost of inventory?

Free
(Multiple Choice)
4.9/5  (77)
(77) Correct Answer: Verified
C
When an inventory costing formula is changed, the change is required to be applied:
Free
(Multiple Choice)
4.8/5 (68)
(68) Correct Answer:Verified
VerifiedB
Duo Ltd uses a periodic inventory system and rounds the average unit cost to the nearest dollar. The following data relates to Duo Ltd for the year ended 30 June 2013:
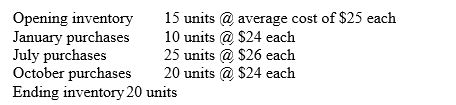 The cost of ending inventory using the weighted average cost method (rounded to the nearest dollar) is:
Free
(Multiple Choice)
4.9/5 (78)
(78) Correct Answer:Verified
VerifiedC
The terms '2/7' appearing on an invoice for the sale/purchase of inventory means that the buyer:
(Multiple Choice)
4.9/5 (80)
(80) The measurement rule for inventories, mandated by IAS 2 Inventories, is:
(Multiple Choice)
4.9/5 (74)
(74) Net realisable value of inventories may fall below cost for a number of reasons including:
I Product obsolescence.
II Physical deterioration of inventories.
III An increase in the expected replacement costs of the inventory,
IV An increase in the estimated costs of completion.
(Multiple Choice)
4.9/5 (89)
(89) Commodity broker traders are able to measure their inventories at:
(Multiple Choice)
4.8/5 (92)
(92) Under the periodic inventory approach an appropriate journal entry to measure closing inventory is:
(Multiple Choice)
4.8/5 (72)
(72) Where the net realisable value of inventory falls below cost, IAS 2 Inventories, requires that:
(Multiple Choice)
4.8/5 (84)
(84) Under the periodic inventory approach the cost of goods sold during a period is determined as follows:
(Multiple Choice)
4.8/5 (87)
(87) The weighted average inventory costing method is particularly suitable to inventory where:
(Multiple Choice)
4.9/5 (69)
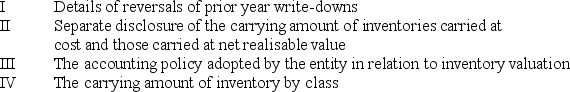
(69) 
Ming Limited had the following items of inventory at reporting date:
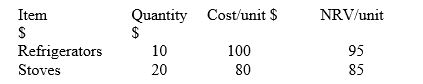 The adjustment necessary at reporting date is:
 (Multiple Choice)
4.7/5 (80)
(80) If the selling price of inventory that has been written down to net realisable value in a prior period, subsequently recovers, the:
(Multiple Choice)
4.7/5 (82)
(82) Under IAS 2 Inventories, items of inventory that are used by business enterprise as components in a self-constructed property asset are required to be:
(Multiple Choice)
4.9/5 (79)
(79) Which of the following is not recognised as an expense in accordance with IAS 2?
(Multiple Choice)
4.8/5 (73)
(73) 'Net realisable value' of inventory is defined as the net amount that an enterprise expects to realise from the sale of the inventory:
(Multiple Choice)
4.9/5 (88)
(88) When an entity's operating cycle is not clearly identifiable it is assumed to be:
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)