



 Chat with AI
Exam 27: Consolidation: Other Issues

Exam 1: The Conceptual Framework of the Iasb30 Questions
Exam 2: Shareholders Equity: Share Capital and Reserves28 Questions
Exam 3: Fair Value Measurement30 Questions
Exam 4: Revenue30 Questions
Exam 5: Provisions, Contingent Liabilities and Contingent Assets30 Questions
Exam 6: Income Taxes28 Questions
Exam 7: Financial Instruments30 Questions
Exam 8: Share-Based Payments28 Questions
Exam 9: Inventories29 Questions
Exam 10: Employee Benefits29 Questions
Exam 11: Property, Plant and Equipment28 Questions
Exam 12: Leases27 Questions
Exam 13: Intangible Assets28 Questions
Exam 14: Business Combinations30 Questions
Exam 15: Impairment of Assets28 Questions
Exam 16: Accounting for Mineral Resources26 Questions
Exam 17: Agriculture26 Questions
Exam 18: Financial Statement Presentation29 Questions
Exam 19: Statement of Cash Flows28 Questions
Exam 20: Earnings Per Share20 Questions
Exam 21: Operating Segments30 Questions
Exam 22: Operating Segments29 Questions
Exam 23: Consolidation: Controlled Entities29 Questions
Exam 24: Consolidation: Wholly Owned Subsidiaries26 Questions
Exam 25: Consolidation: Intragroup Transactions27 Questions
Exam 26: Consolidation: Non-Controlling Interest25 Questions
Exam 27: Consolidation: Other Issues29 Questions
Exam 28: Translation of the Financial Statements of Foreign Entities28 Questions
Exam 29: Associates and Joint Ventures26 Questions
Exam 30: Joint Arrangements26 Questions
Select questions type


The following information relates to questions 22 to 24
Jacaranda Limited acquired a 75% ownership interest in Frangipani Limited on 30 June 2014. On the same day, Frangipani Limited acquired a 60% ownership interest in Gardener Limited. The following interentity transactions have taken place between the entities in the group during the years ended 30 June 2014 and 30 June 2015:
On 1 July 2013 Gardener sold an item of plant to Jacaranda for a profit of $25 000. The remaining useful life of the plant at the date of transfer was 2 years.
On 1 September 2013, Gardener paid a dividend of $100 000 from profits earned prior to 30 June 2013.
Jacaranda lent $500 000 to Gardener on 1 January 2014. Interest charged on the loan for the year ended 30 June 2014 was $20 000 and for the year ended 30 June 2015 was $40 000.
On 31 May 2014 Frangipani sold inventory to Gardener for $15 000. Profit earned on the sale was $1500. Gardener sold the inventory to external parties on 1 August 2014.
Details of profits earned by entities within the group for the years ended 30 June 2014 and 30 June 2015 are:
 The tax rate is 30%.
-The NCI share of profit in the Frangipani group for the year ended 30 June 2014 is:
The tax rate is 30%.
-The NCI share of profit in the Frangipani group for the year ended 30 June 2014 is:
Free
(Multiple Choice)
4.8/5  (68)
(68) Correct Answer: Verified
C
When preparing consolidation adjustment entries to effect a consolidation of a multiple subsidiary structure intragroup transactions:
Free
(Multiple Choice)
4.8/5 (84)
(84) Correct Answer:Verified
VerifiedD
The indirect non-controlling interest, in a group that has a multiple subsidiary structure, is entitled to:
Free
(Multiple Choice)
5.0/5 (82)
(82) Correct Answer:Verified
VerifiedA
In a multiple subsidiary structure the direct non-controlling interest is entitled to a proportionate share of:
(Multiple Choice)
4.8/5 (84)
(84) Tribulation Limited has an ownership interest of 80% in a subsidiary Trouble Limited. Trouble owns 60% of Strife Limited. Since acquisition date the retained earnings of Strife Limited have increased from $80 000 to $130 000. The direct non-controlling interest in the retained earnings of Strife is:
(Multiple Choice)
4.9/5 (77)
(77) X Limited has a 70% ownership interest in Y Limited. Y Limited has a 60% ownership interest in Z Limited. X Limited has an indirect ownership interest in Z Limited of:
(Multiple Choice)
4.9/5 (68)
(68) The following information relates to questions 26 and 27
On 1 July 2012 Yamba Ltd acquired a 60% interest in Zombi Ltd for $42,000. At that date the net assets of Zombi comprised $30,000 share capital and $23,000 retained earnings. All assets were recorded at their fair values, with the exception of an item of land, whose carrying amount was $10,000 less than its fair value.
On 1 July 2013 Xtreme Ltd acquired a 50% interest in Yamba Ltd for $65,000.
At that date the net assets of Yamba Ltd comprised $50,000 share capital and $60,000 retained earnings. All assets were recorded at their fair values, with the exception of Yamba Ltd's investment in Zombi Ltd, which had a fair value of $54,000.
During the twelve months to 30 June 2013 the retained earnings of Zombi Ltd had increased to $30,000. In addition the fair value of the land had increased by a further $10,000.
The Xtreme Group accounts for goodwill under the partial method.
-The consolidation elimination entry to eliminate Xtreme Ltd's investment in Yamba Ltd at 30 June 2013 will require a credit against the "Investment in Yamba" account of $65,000 and a debit against the Business Combination Valuation Reserve of:
(Multiple Choice)
4.7/5 (66)
(66) The following information relates to questions 17 to 21
Waratah Ltd acquired a 60% ownership interest in Bottle Brush Ltd on 30 June 2013. On the same day, Bottle Brush Ltd acquired a 70% ownership interest in Honeydew Ltd.
The following interentity transactions have taken place between the entities in the group during the years ended 30 June 2014 and 30 June 2015:
On 1 July 2013 Bottle Brush sold an item of plant to Honeydew for a profit of $20 000. The remaining useful life of the plant at the date of transfer was 4 years.
On 1 September 2013, Honeydew paid a dividend of $70 000 from profits earned since 30 June 2013.
Waratah lent $50 000 to Bottle Brush on 1 January 2014. Interest charged on the loan for the year ended 30 June 2014 was $2000 and for the year ended 30 June 2015 was $4000.
On 31 May 2014 Honeydew sold inventory to Waratah for $15,000. Profit earned on the sale was $5000. Waratah sold the inventory to external parties on 1 August 2014.
Details of profits earned by entities within the group for the years ended 30 June 2014 and 30 June 2015 are:
 The tax rate is 30%.
-The NCI share of profit in Honeydew for the year ended 30 June 2015 is:
The tax rate is 30%.
-The NCI share of profit in Honeydew for the year ended 30 June 2015 is: (Multiple Choice)
4.9/5 (74)
(74) The following information relates to questions 17 to 21
Waratah Ltd acquired a 60% ownership interest in Bottle Brush Ltd on 30 June 2013. On the same day, Bottle Brush Ltd acquired a 70% ownership interest in Honeydew Ltd.
The following interentity transactions have taken place between the entities in the group during the years ended 30 June 2014 and 30 June 2015:
On 1 July 2013 Bottle Brush sold an item of plant to Honeydew for a profit of $20 000. The remaining useful life of the plant at the date of transfer was 4 years.
On 1 September 2013, Honeydew paid a dividend of $70 000 from profits earned since 30 June 2013.
Waratah lent $50 000 to Bottle Brush on 1 January 2014. Interest charged on the loan for the year ended 30 June 2014 was $2000 and for the year ended 30 June 2015 was $4000.
On 31 May 2014 Honeydew sold inventory to Waratah for $15,000. Profit earned on the sale was $5000. Waratah sold the inventory to external parties on 1 August 2014.
Details of profits earned by entities within the group for the years ended 30 June 2014 and 30 June 2015 are:
The tax rate is 30%.
-The NCI share of profit in Honeydew for the year ended 30 June 2014 is:
The tax rate is 30%.
-The NCI share of profit in Honeydew for the year ended 30 June 2014 is: (Multiple Choice)
4.8/5 (81)
(81) Use the information below to answer questions 4 and 5
Consider the following group structure.
 -The INCI in B Ltd is the same group of shareholders as the:
 (Multiple Choice)
4.8/5 (75)
(75) The following information relates to questions 17 to 21
Waratah Ltd acquired a 60% ownership interest in Bottle Brush Ltd on 30 June 2013. On the same day, Bottle Brush Ltd acquired a 70% ownership interest in Honeydew Ltd.
The following interentity transactions have taken place between the entities in the group during the years ended 30 June 2014 and 30 June 2015:
On 1 July 2013 Bottle Brush sold an item of plant to Honeydew for a profit of $20 000. The remaining useful life of the plant at the date of transfer was 4 years.
On 1 September 2013, Honeydew paid a dividend of $70 000 from profits earned since 30 June 2013.
Waratah lent $50 000 to Bottle Brush on 1 January 2014. Interest charged on the loan for the year ended 30 June 2014 was $2000 and for the year ended 30 June 2015 was $4000.
On 31 May 2014 Honeydew sold inventory to Waratah for $15,000. Profit earned on the sale was $5000. Waratah sold the inventory to external parties on 1 August 2014.
Details of profits earned by entities within the group for the years ended 30 June 2014 and 30 June 2015 are:
The tax rate is 30%.
-The NCI share of profit in Bottle Brush for the year ended 30 June 2014 is:
The tax rate is 30%.
-The NCI share of profit in Bottle Brush for the year ended 30 June 2014 is: (Multiple Choice)
4.9/5 (85)
(85) The pre-acquisition entry for the Hayward group in order to consolidate a 60% interest in a subsidiary contained the following debits. Retained earnings $3000, Share capital $6000, General Reserve $1200, BCVR $600. The interest in equity attributable to the direct non-controlling interest is:
(Multiple Choice)
4.7/5 (83)
(83) The following information relates to questions 22 to 24
Jacaranda Limited acquired a 75% ownership interest in Frangipani Limited on 30 June 2014. On the same day, Frangipani Limited acquired a 60% ownership interest in Gardener Limited. The following interentity transactions have taken place between the entities in the group during the years ended 30 June 2014 and 30 June 2015:
On 1 July 2013 Gardener sold an item of plant to Jacaranda for a profit of $25 000. The remaining useful life of the plant at the date of transfer was 2 years.
On 1 September 2013, Gardener paid a dividend of $100 000 from profits earned prior to 30 June 2013.
Jacaranda lent $500 000 to Gardener on 1 January 2014. Interest charged on the loan for the year ended 30 June 2014 was $20 000 and for the year ended 30 June 2015 was $40 000.
On 31 May 2014 Frangipani sold inventory to Gardener for $15 000. Profit earned on the sale was $1500. Gardener sold the inventory to external parties on 1 August 2014.
Details of profits earned by entities within the group for the years ended 30 June 2014 and 30 June 2015 are:
The tax rate is 30%.
-The NCI share of profit in Gardener for the year ended 30 June 2015 is:
The tax rate is 30%.
-The NCI share of profit in Gardener for the year ended 30 June 2015 is: (Multiple Choice)
4.9/5 (80)
(80) Klang Limited has a direct ownership interest of 90% in Liao Limited. Liao Limited has a direct ownership interest of 70% in Meng Limited. The indirect non-controlling interest in Meng Limited is:
(Multiple Choice)
4.9/5 (71)
(71) Use the information below to answer questions 4 and 5
Consider the following group structure.
-The direct non-controlling interest (DNCI) and indirect non-controlling interest (INCI) are: 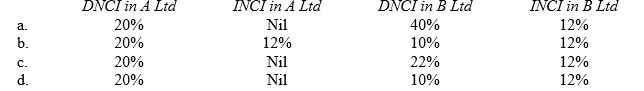
-The direct non-controlling interest (DNCI) and indirect non-controlling interest (INCI) are: (Short Answer)
4.8/5 (86)
(86) Which of the following cannot result in a loss of control by a parent over a subsidiary?
(Multiple Choice)
4.9/5 (73)
(73) An ownership structure in which Orange Limited acquires shares in Pear Limited before Pear Limited acquires shares in Quince Limited is known as:
(Multiple Choice)
4.9/5 (88)
(88) A Limited has a 60% ownership interest in B Limited. B Limited has a 70% ownership interest in C Limited. As a result of these ownership interests, there is an indirect ownership interest in C Limited of:
(Multiple Choice)
4.8/5 (88)
(88) Where a parent acquires additional shares in a subsidiary subsequent to obtaining control the change is accounted for:
(Multiple Choice)
4.9/5 (84)
(84) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)