



 Chat with AI
Exam 10: Employee Benefits

Exam 1: The Conceptual Framework of the Iasb30 Questions
Exam 2: Shareholders Equity: Share Capital and Reserves28 Questions
Exam 3: Fair Value Measurement30 Questions
Exam 4: Revenue30 Questions
Exam 5: Provisions, Contingent Liabilities and Contingent Assets30 Questions
Exam 6: Income Taxes28 Questions
Exam 7: Financial Instruments30 Questions
Exam 8: Share-Based Payments28 Questions
Exam 9: Inventories29 Questions
Exam 10: Employee Benefits29 Questions
Exam 11: Property, Plant and Equipment28 Questions
Exam 12: Leases27 Questions
Exam 13: Intangible Assets28 Questions
Exam 14: Business Combinations30 Questions
Exam 15: Impairment of Assets28 Questions
Exam 16: Accounting for Mineral Resources26 Questions
Exam 17: Agriculture26 Questions
Exam 18: Financial Statement Presentation29 Questions
Exam 19: Statement of Cash Flows28 Questions
Exam 20: Earnings Per Share20 Questions
Exam 21: Operating Segments30 Questions
Exam 22: Operating Segments29 Questions
Exam 23: Consolidation: Controlled Entities29 Questions
Exam 24: Consolidation: Wholly Owned Subsidiaries26 Questions
Exam 25: Consolidation: Intragroup Transactions27 Questions
Exam 26: Consolidation: Non-Controlling Interest25 Questions
Exam 27: Consolidation: Other Issues29 Questions
Exam 28: Translation of the Financial Statements of Foreign Entities28 Questions
Exam 29: Associates and Joint Ventures26 Questions
Exam 30: Joint Arrangements26 Questions
Select questions type


Pirate Ltd employs 5 staff. Each staff member is entitled to 20 days annual leave per annum. Leave loading of 17.5% is paid when the leave is taken. At 1 July 2013 the balance in the provision for annual leave account was $20 303.
Details of each employees leave entitlement at 30 June 2014 are as follows:
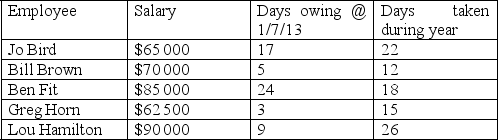 There are 260 work days in a year. On 1 July each year all employees receive a 5% wage rise. There are no other wage rises given during the year.
Annual leave payments made during the year were debited against the provision account. The total debit against the annual leave account during the year in relation to leave taken was:
There are 260 work days in a year. On 1 July each year all employees receive a 5% wage rise. There are no other wage rises given during the year.
Annual leave payments made during the year were debited against the provision account. The total debit against the annual leave account during the year in relation to leave taken was: (Multiple Choice)
4.8/5  (84)
(84) The key steps involved in accounting by the employer for a defined benefit post-employment fund in accordance with IAS 19 include:
(Multiple Choice)
4.7/5 (78)
(78) Which of the following types of employee benefits are required to be measured at the present value of expected future cash flows?
(Multiple Choice)
4.9/5 (76)
(76) Employee benefits can arise from which of the following?
I workplace agreements between an entity and its employees
II enterprise bargaining agreements between an entity and the relevant employee union
III government legislation
IV specific industry arrangements
(Multiple Choice)
4.8/5 (84)
(84) The nominal value of an accumulated benefit for long service leave is calculated as (Years of employment/Years required for LSL) x (weeks of paid leave/52) x ………..?
(Multiple Choice)
4.8/5 (77)
(77) Benefits paid to members of a defined benefit post-employment fund are based on:
I the level of employer contributions made to the fund
II remuneration levels while employed
III number of years service
IV investment returns generated by the fund
(Multiple Choice)
4.8/5 (70)
(70) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)