



 Chat with AI
Exam 13: Relevant Costs for Decision Making

Exam 1: Managerial Accounting and the Business Environment25 Questions
Exam 2: Managerial Accounting and Cost Concepts148 Questions
Exam 3: Systems Design: Job-Order Costing163 Questions
Exam 4: Systems Design: Process Costing106 Questions
Exam 5: Cost Behavior Analysis and Use119 Questions
Exam 6: Cost-Volume-Profit Relationship213 Questions
Exam 7: Variable Costing: a Tool for Management136 Questions
Exam 8: Activity Based Costing: a Tool to Aid Decision-Making77 Questions
Exam 9: Profit Planning144 Questions
Exam 10: Flexible Budgets and Performance Analysis294 Questions
Exam 11: Standard Costs and Operating Performance Measures163 Questions
Exam 12: Segment Reporting, Decentralization, and the Balanced Scorecard99 Questions
Exam 13: Relevant Costs for Decision Making131 Questions
Exam 14: Capital Budgeting Decisions138 Questions
Exam 15: How Well Am I Doing Statement of Cash Flows103 Questions
Exam 16: How Well Am I Doing Financial Statement Analysis207 Questions
Exam 17: Pricing Products and Services61 Questions
Exam 18: Profitability Analysis72 Questions
Exam 19: Further Classification of Labor Costs18 Questions
Exam 20: Cost of Quality24 Questions
Exam 21: the Predetermined Overhead Rate and Capacity25 Questions
Exam 22: Fifo Method72 Questions
Exam 23: Service Department Allocations51 Questions
Exam 24: Least-Squares Regression Computations14 Questions
Exam 25: Abc Action Analysis14 Questions
Exam 26: Using a Modified Form of Activity-Based Costing to17 Questions
Exam 27: Predetermined Overhead Rates and Overhead Analysis88 Questions
Exam 28: Journal Entries to Record Variances46 Questions
Exam 29: Transfer Pricing20 Questions
Exam 30: Service Department Charges34 Questions
Exam 31: The Concept of Present Value14 Questions
Exam 32: Income Taxes in Capital Budgeting Decisions33 Questions
Exam 33: The Direct Method of Determining the Net Cash Provided by42 Questions
Select questions type


Outram Corporation is presently making part I14 that is used in one of its products. A total of 8,000 units of this part are produced and used every year. The company's Accounting Department reports the following costs of producing the part at this level of activity:  An outside supplier has offered to make and sell the part to the company for $14.80 each. If this offer is accepted, the supervisor's salary and all of the variable costs can be avoided. The special equipment used to make the part was purchased many years ago and has no salvage value or other use. The allocated general overhead represents fixed costs of the entire company, none of which would be avoided if the part were purchased instead of produced internally. If management decides to buy part I14 from the outside supplier rather than to continue making the part, what would be the annual impact on the company's overall net operating income?
 (Multiple Choice)
4.9/5  (82)
(82) Nowak Corporation is a specialty component manufacturer with idle capacity. Management would like to use its extra capacity to generate additional profits. A potential customer has offered to buy 1,600 units of component FHB. Each unit of FHB requires 8 units of material N95 and 1 unit of material K78. Data concerning these two materials follow:  Material N95 is in use in many of the company's products and is routinely replenished. Material K78 is no longer used by the company in any of its normal products and existing stocks would not be replenished once they are used up.
What would be the relevant cost of the materials, in total, for purposes of determining a minimum acceptable price for the order for product FHB?
Material N95 is in use in many of the company's products and is routinely replenished. Material K78 is no longer used by the company in any of its normal products and existing stocks would not be replenished once they are used up.
What would be the relevant cost of the materials, in total, for purposes of determining a minimum acceptable price for the order for product FHB? (Multiple Choice)
4.8/5 (87)
(87) The opportunity cost of making a component part in a factory with excess capacity for which there is no alternative use is:
(Multiple Choice)
4.8/5 (74)
(74) For which of the following decisions are sunk costs relevant?
(Multiple Choice)
4.9/5 (82)
(82) United Industries manufactures a number of products at its highly automated factory. The products are very popular, with demand far exceeding the factory's capacity. To maximize profit, management should rank products based on their:
(Multiple Choice)
4.8/5 (84)
(84) Brubacher Company makes four products in a single facility. These products have the following unit product costs:  The grinding machines are potentially the constraint in the production facility. A total of 20,500 minutes are available per month on these machines.
Direct labor is a variable cost in this company.
-Which product makes the LEAST profitable use of the grinding machines?
The grinding machines are potentially the constraint in the production facility. A total of 20,500 minutes are available per month on these machines.
Direct labor is a variable cost in this company.
-Which product makes the LEAST profitable use of the grinding machines? (Multiple Choice)
4.8/5 (71)
(71) Hayase Corporation processes sugar beets that it purchases from farmers. Sugar beets are processed in batches. A batch of sugar beets costs $35 to buy from farmers and $14 to crush in the company's plant. Two intermediate products, beet fiber and beet juice, emerge from the crushing process. The beet fiber can be sold as is for $27 or processed further for $11 to make the end product industrial fiber that is sold for $40. The beet juice can be sold as is for $36 or processed further for $21 to make the end product refined sugar that is sold for $46.
-How much profit (loss) does the company make by processing one batch of sugar beets into the end products industrial fiber and refined sugar?
(Multiple Choice)
4.8/5 (72)
(72) The constraint at Crumedy Inc. is an expensive milling machine. The three products listed below use this constrained resource. 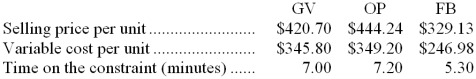 Required:
a. Rank the products in order of their current profitability from the most profitable to the least profitable. In other words, rank the products in the order in which they should be emphasized. Show your work!
b. Assume that sufficient constraint time is available to satisfy demand for all but the least profitable product. Up to how much should the company be willing to pay to acquire more of the constrained resource?
Required:
a. Rank the products in order of their current profitability from the most profitable to the least profitable. In other words, rank the products in the order in which they should be emphasized. Show your work!
b. Assume that sufficient constraint time is available to satisfy demand for all but the least profitable product. Up to how much should the company be willing to pay to acquire more of the constrained resource? (Essay)
4.9/5 (67)
(67) All other things equal, it is profitable to continue processing a joint product after the split-off point so long as the incremental revenue from further processing exceeds the incremental costs of further processing.
(True/False)
4.8/5 (86)
(86) Lounsberry Inc. regularly uses material O55P and currently has in stock 360 liters of the material for which it paid $2,484 several weeks ago. If this were to be sold as is on the open market as surplus material, it would fetch $6.35 per liter. New stocks of the material can be purchased on the open market for $6.90 per liter, but it must be purchased in lots of 1,000 liters. You have been asked to determine the relevant cost of 800 liters of the material to be used in a job for a customer. The relevant cost of the 800 liters of material O55P is:
(Multiple Choice)
4.9/5 (63)
(63) Rowena Corporation manufactures laser printers. Rowena currently manufactures the 32,000 imaging drums that it uses in its printers. The annual costs to manufacture these 32,000 drums are as follows:  Hardware Solutions, Inc. has offered to provide Rowena with all of its imaging drum needs for $72 per drum. If Rowena accepts this offer, 70% of the fixed manufacturing cost above could be totally eliminated. Also, Rowena will be able to use the freed up space to generate $240,000 of income each year in the production of alternative products.
-Assume that demand for Rowena printers goes up from 32,000 annually to 40,000 annually. Also assume that Rowena has the idle capacity to produce the extra 8,000 drums needed for the printers. Under these conditions, would Rowena be better off to make the drums or buy the drums and by how much? (Assume that there is no change in cost structure.)
Hardware Solutions, Inc. has offered to provide Rowena with all of its imaging drum needs for $72 per drum. If Rowena accepts this offer, 70% of the fixed manufacturing cost above could be totally eliminated. Also, Rowena will be able to use the freed up space to generate $240,000 of income each year in the production of alternative products.
-Assume that demand for Rowena printers goes up from 32,000 annually to 40,000 annually. Also assume that Rowena has the idle capacity to produce the extra 8,000 drums needed for the printers. Under these conditions, would Rowena be better off to make the drums or buy the drums and by how much? (Assume that there is no change in cost structure.) (Multiple Choice)
4.7/5 (85)
(85) Two products, TD and IB, emerge from a joint process. Product TD has been allocated $31,200 of the total joint costs of $48,000. A total of 5,000 units of product TD are produced from the joint process. Product TD can be sold at the split-off point for $24 per unit, or it can be processed further for an additional total cost of $15,000 and then sold for $26 per unit. If product TD is processed further and sold, what would be the effect on the overall profit of the company compared with sale in its unprocessed form directly after the split-off point?
(Multiple Choice)
4.9/5 (76)
(76) Oran Refiners, Inc., processes sugar cane that it purchases from farmers. Sugar cane is processed in batches. A batch of sugar cane costs $76 to buy from farmers and $18 to crush in the company's plant. Two intermediate products, cane fiber and cane juice, emerge from the crushing process. The cane fiber can be sold as is for $21 or processed further for $12 to make the end product industrial fiber that is sold for $43. The cane juice can be sold as is for $47 or processed further for $21 to make the end product molasses that is sold for $88.
-Which of the intermediate products should be processed further?
(Multiple Choice)
4.9/5 (70)
(70) Govoni Corporation is a specialty component manufacturer with idle capacity. Management would like to use its extra capacity to generate additional profits. A potential customer has offered to buy 9,500 units of component AIG. Each unit of AIG requires 6 units of material M51 and 4 units of material M93. Data concerning these two materials follow:  Material M51 is in use in many of the company's products and is routinely replenished. Material M93 is no longer used by the company in any of its normal products and existing stocks would not be replenished once they are used up.
What would be the relevant cost of the materials, in total, for purposes of determining a minimum acceptable price for the order for product AIG?
Material M51 is in use in many of the company's products and is routinely replenished. Material M93 is no longer used by the company in any of its normal products and existing stocks would not be replenished once they are used up.
What would be the relevant cost of the materials, in total, for purposes of determining a minimum acceptable price for the order for product AIG? (Multiple Choice)
4.9/5 (73)
(73) Isaac Corporation processes sugar beets in batches that it purchases from farmers for $47 a batch. A batch of sugar beets costs $14 to crush in the company's plant. Two intermediate products, beet fiber and beet juice, emerge from the crushing process. The beet fiber can be sold as is for $22 or processed further for $13 to make the end product industrial fiber that is sold for $42. The beet juice can be sold as is for $45 or processed further for $27 to make the end product refined sugar that is sold for $67. Which of the intermediate products should be processed further?
(Multiple Choice)
4.7/5 (79)
(79) Part J88 is used in one of Quinney Corporation's products. The company makes 3,000 units of this part each year. The company's Accounting Department reports the following costs of producing the part at this level of activity:  An outside supplier has offered to produce this part and sell it to the company for $32.10 each. If this offer is accepted, the supervisor's salary and all of the variable costs, including direct labor, can be avoided. The special equipment used to make the part was purchased many years ago and has no salvage value or other use. The allocated general overhead represents fixed costs of the entire company. If the outside supplier's offer were accepted, only $3,000 of these allocated general overhead costs would be avoided.
If management decides to buy part J88 from the outside supplier rather than to continue making the part, what would be the annual impact on the company's overall net operating income?
An outside supplier has offered to produce this part and sell it to the company for $32.10 each. If this offer is accepted, the supervisor's salary and all of the variable costs, including direct labor, can be avoided. The special equipment used to make the part was purchased many years ago and has no salvage value or other use. The allocated general overhead represents fixed costs of the entire company. If the outside supplier's offer were accepted, only $3,000 of these allocated general overhead costs would be avoided.
If management decides to buy part J88 from the outside supplier rather than to continue making the part, what would be the annual impact on the company's overall net operating income? (Multiple Choice)
4.9/5 (86)
(86) The management of Thews Corporation is considering dropping product E28I. Data from the company's accounting system appear below: 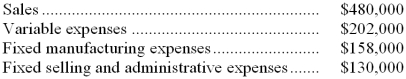 All fixed expenses of the company are fully allocated to products in the company's accounting system. Further investigation has revealed that $86,000 of the fixed manufacturing expenses and $67,000 of the fixed selling and administrative expenses are avoidable if product E28I is discontinued.
Required:
a. What is the net operating income earned by product E28I according to the company's accounting system? Show your work!
b. What would be the effect on the company's overall net operating income of dropping product E28I? Should the product be dropped? Show your work!
All fixed expenses of the company are fully allocated to products in the company's accounting system. Further investigation has revealed that $86,000 of the fixed manufacturing expenses and $67,000 of the fixed selling and administrative expenses are avoidable if product E28I is discontinued.
Required:
a. What is the net operating income earned by product E28I according to the company's accounting system? Show your work!
b. What would be the effect on the company's overall net operating income of dropping product E28I? Should the product be dropped? Show your work! (Essay)
4.8/5 (71)
(71) Libbee Corporation is presently making part I50 that is used in one of its products. A total of 8,000 units of this part are produced and used every year. The company's Accounting Department reports the following costs of producing the part at this level of activity:  An outside supplier has offered to produce and sell the part to the company for $24.50 each. If this offer is accepted, the supervisor's salary and all of the variable costs, including direct labor, can be avoided. The special equipment used to make the part was purchased many years ago and has no salvage value or other use. The allocated general overhead represents fixed costs of the entire company, none of which would be avoided if the part were purchased instead of produced internally.
-In addition to the facts given above, assume that the space used to produce part I50 could be used to make more of one of the company's other products, generating an additional segment margin of $24,000 per year for that product. What would be the impact on the company's overall net operating income of buying part I50 from the outside supplier and using the freed space to make more of the other product?
An outside supplier has offered to produce and sell the part to the company for $24.50 each. If this offer is accepted, the supervisor's salary and all of the variable costs, including direct labor, can be avoided. The special equipment used to make the part was purchased many years ago and has no salvage value or other use. The allocated general overhead represents fixed costs of the entire company, none of which would be avoided if the part were purchased instead of produced internally.
-In addition to the facts given above, assume that the space used to produce part I50 could be used to make more of one of the company's other products, generating an additional segment margin of $24,000 per year for that product. What would be the impact on the company's overall net operating income of buying part I50 from the outside supplier and using the freed space to make more of the other product? (Multiple Choice)
4.8/5 (74)
(74) Which product would be selected in a decision that involves the utilization of a constrained resource?
(Multiple Choice)
4.9/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)