



 Chat with AI
Exam 6: Merchandise Inventory and Cost of Sales

Exam 1: Accounting in Business245 Questions
Exam 2: Analyzing and Reporting Transactions131 Questions
Exam 3: Adjusting Accounts for Financial Statements187 Questions
Exam 4: Completing the Accounting Cycle and Classifying Accounts141 Questions
Exam 5: Accounting for Merchandising Activities127 Questions
Exam 6: Merchandise Inventory and Cost of Sales150 Questions
Exam 7: Accounting Information Systems100 Questions
Exam 8: Internal Control and Cash139 Questions
Exam 9: Receivables145 Questions
Select questions type


Because an inventory error causes an offsetting error in the next period:
(Multiple Choice)
4.8/5  (82)
(82) When businesses apply the lower of cost and net realizable value rule on an item by item basis,they will report the lowest inventory value possible.
(True/False)
4.8/5 (91)
(91) In applying LCNRV,net realizable value is defined as the sales price less costs incurred to make the sale.
(True/False)
4.8/5 (76)
(76) Isaiah's Gear had the following ending inventory costs: 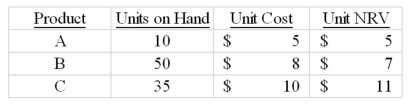 Calculate the lower of cost and net realizable value (LCNRV)on an item by item basis.
 (Essay)
4.8/5 (81)
(81) A major goal in accounting for inventory is __________________ relevant costs with revenues.
(Short Answer)
4.7/5 (63)
(63) The assignment of costs to cost of goods sold and inventory using (moving)weighted average usually gives different results depending on whether a perpetual or periodic system is used.
(True/False)
4.9/5 (83)
(83) The FIFO method assumes that costs for the most recently purchased items are recovered first.
(True/False)
4.7/5 (87)
(87) The three methods of inventory valuation that are most often used in Canada are specific identification,FIFO,and (moving)weighted average.
(True/False)
4.8/5 (76)
(76) Patel Packing had the following information for its inventory: Beginning inventory: cost $107,000; retail $130,000
Net purchases: cost $58,000; retail $120,000
Sales at retail: $145,000
What is the estimated cost of the ending inventory?
(Multiple Choice)
4.8/5 (70)
(70) The principle of faithful representation requires that information be complete,neutral and free from error so that assets and income are not overstated and liabilities and expenses are not understated.
(True/False)
4.9/5 (75)
(75) The total dollar value of inventory on hand is determined by: (1)estimating the units on hand,(2)multiplying the count by cost per unit,and (3)adding the costs for all products.
(True/False)
4.7/5 (79)
(79) The retail inventory method estimates the cost of ending inventory by applying the gross profit ratio to net sales.
(True/False)
4.9/5 (90)
(90) Apply the retail method to the following information and calculate the cost of the ending inventory: 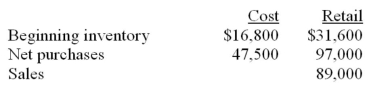
(Essay)
4.9/5 (83)
(83) The necessary financial statement disclosure is accomplished if the amount presented is properly calculated.
(True/False)
4.9/5 (79)
(79) Most businesses apply the lower of cost and net realizable value rule to groups of similar or related items.
(True/False)
4.9/5 (80)
(80) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)