



 Chat with AI
Exam 10: Credit Analysis

Exam 1: Overview of Financial Statement Analysis79 Questions
Exam 2: Financial Reporting and Analysis74 Questions
Exam 3: Analyzing Financing Activities82 Questions
Exam 4: Analyzing Investing Activities67 Questions
Exam 5: Analyzing Investing Activities: Intercorporate Investments101 Questions
Exam 6: Analyzing Operating Activities83 Questions
Exam 7: Cash Flow Analysis80 Questions
Exam 8: Return on Invested Capital and Profitability Analysis76 Questions
Exam 9: Prospective Analysis65 Questions
Exam 10: Credit Analysis104 Questions
Exam 11: Equity Analysis and Valuation73 Questions
Select questions type


The greater the variability of sales the higher the earnings coverage ratios should ideally be, all other things equal.

Free
(True/False)
5.0/5  (78)
(78) Correct Answer: Verified
True
When examining the debt/equity ratio of a company, consideration should be given to pension liabilities. Specifically, it should be determined if the projected benefit obligation significantly exceeds the plan assets, and if it does compare this to any liability recorded on balance sheet.
Free
(True/False)
4.9/5 (64)
(64) Correct Answer:Verified
VerifiedTrue
Company B has operating leases with a present value of $2,000 when future minimum lease payments are discounted at 9% as of 12/31/04. Times interest earned ratio, after necessary adjustments, for Company B is:
Free
(Multiple Choice)
4.9/5 (95)
(95) Correct Answer:Verified
VerifiedC
Which of the following industries would you expect to have the highest inventory turnover?
(Multiple Choice)
4.7/5 (74)
(74) When calculating earnings coverage ratios it is common to remove the effects of extraordinary gains and losses and other one-time gains and losses from the numerator.
(True/False)
5.0/5 (75)
(75) If a company's current ratio increases from 1.1 to 1.3 from one year to the next, it can be concluded that:
(Multiple Choice)
4.8/5 (94)
(94) Which of the following is least likely to increase the overall risk of a company?
(Multiple Choice)
4.8/5 (70)
(70) Which of the following is not included in the computation of Altman's Z-score?
(Multiple Choice)
4.8/5 (76)
(76) Which of the following industries would you expect to have the longest operating cycle?
(Multiple Choice)
4.8/5 (91)
(91) Typical debt covenants would
I. Limit the issuance of additional debt senior to the obligation
II. Specify minimum levels of selected financial ratios
III. Specify minimum levels of earnings coverage
IV. Prohibit excessive dividends or stock repurchases
(Multiple Choice)
4.8/5 (79)
(79) When calculating the times interest earned adjustments should normally be made for existence of operating leases. A portion of rental payments should be reclassified as interest.
(True/False)
4.7/5 (80)
(80) Refer to the financial statements for Wal*Mart, below Wal"Mart
(in millions)
Consolidated Statements of Operations
Fiscal Year Ended
31-Jan X2 31-Jan X3 31-Jan X4 31-Jan X5 31-Jan X6 31-Jan X7 31-Jan X8 Net sales $ 43,887 $ 55,484 $ 67,345 $ 82,494 $ 93,627 $ 104,859 Rentals from licensed dept 28 36 47 Other income-net 374 465 593 918 1,122 1,287 Total revenues 44,289 55,985 67,985 83,412 94,749 106,146 118,884 Cost of sales 34,786 44,174 53,444 65,586 74,564 83,663 Operating, Selling, General& Administrative Expenses 6,684 8,321 10,333 12,858 14,951 16,788 Total operating expenses 41,470 52,495 63,777 78,444 89,515 100,451 Operating income 2,819 3,490 4,208 4,968 5,234 5,695 6,378 Interest costs Debt 113 143 331 520 692 629 Capital leases 153 180 186 186 196 216 266 323 517 706 888 845 930 Income before taxes 2,553 3,167 3,691 4,262 4,346 4,850 5,449 Income tax expense Current 906 1,137 1,325 1,572 1,530 1,974 Deferred 39 35 33 9 76 (180) 945 1,172 1,358 1,581 1,606 1,794 2,016 Net income $ 1,608 $ 1,995 $ 2,333 $ 2,681 $ 2,740 $ 3,056 $ 3,433 EPS $ 0.70 $ 0.87 $ 1.02 $ 1.17 $ 1.19 $ 1.33 Dividends per share (for the whole year) $ 0.09 $ 0.11 $ 0.13 $ 0.17 $ 0.20 $ 0.21
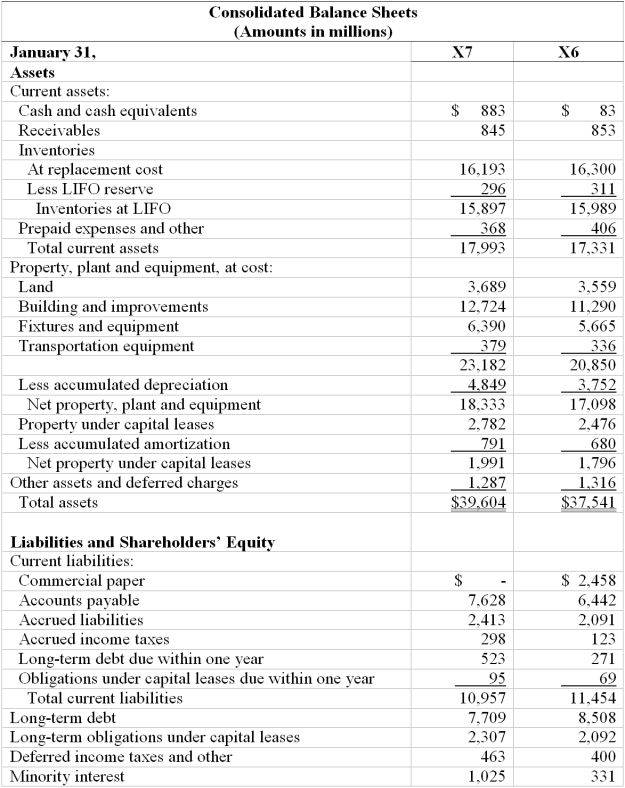 Shareholders' Equity Preferred stock ( 0 par value: 100 share authorized, none issued) Common stock ( \ .10 par value; 5,500 shares authorized. 2,285 and 2,293 issued and outstanding in 1997 and 1996, respectively) 228 229 Capital in excess of par value 547 545 Retained earnings 16,768 14,394 Foreign currency translation adjustment (400) (412) Total shareholders' equity 14,756 Total liabilities and shareholders' equity \ 39,604 \ 37,541
a. Calculate for X7 the ratios listed below. X6 numbers are provided for comparative purposes. Inventory turnover 4.96 Days inventory outstanding 73.56 Accounts receivable turnover 120.58 Days receivable outstanding 3.03 Payables turnover 12.39 Days payables outstanding 29.46 Length of operating cycle 76.58 Length of cash cycle 47.12 Current ratio 1.51 Quick ratio 0.12
b. Working capital management is an important consideration for many companies. Which component of Wal*Mart's working capital do you think it spends most time managing? That is, which component is likely to be the most important? Why? What has happened to this component from X6 to X7?
Wal"Mart (in millions) | Consolidated Statements of Operations Fiscal Year Ended | ||||||
| 31-Jan X2 | 31-Jan X3 | 31-Jan X4 | 31-Jan X5 | 31-Jan X6 | 31-Jan X7 | 31-Jan X8 | |
| Net sales | $ 43,887 | $ 55,484 | $ 67,345 | $ 82,494 | $ 93,627 | $ 104,859 | |
| Rentals from licensed dept | 28 | 36 | 47 | ||||
| Other income-net | 374 | 465 | 593 | 918 | 1,122 | 1,287 | |
| Total revenues | 44,289 | 55,985 | 67,985 | 83,412 | 94,749 | 106,146 | 118,884 |
| Cost of sales | 34,786 | 44,174 | 53,444 | 65,586 | 74,564 | 83,663 | |
| Operating, Selling, General& Administrative Expenses | 6,684 | 8,321 | 10,333 | 12,858 | 14,951 | 16,788 | |
| Total operating expenses | 41,470 | 52,495 | 63,777 | 78,444 | 89,515 | 100,451 | |
| Operating income | 2,819 | 3,490 | 4,208 | 4,968 | 5,234 | 5,695 | 6,378 |
| Interest costs | |||||||
| Debt | 113 | 143 | 331 | 520 | 692 | 629 | |
| Capital leases | 153 | 180 | 186 | 186 | 196 | 216 | |
| 266 | 323 | 517 | 706 | 888 | 845 | 930 | |
| Income before taxes | 2,553 | 3,167 | 3,691 | 4,262 | 4,346 | 4,850 | 5,449 |
| Income tax expense | |||||||
| Current | 906 | 1,137 | 1,325 | 1,572 | 1,530 | 1,974 | |
| Deferred | 39 | 35 | 33 | 9 | 76 | (180) | |
| 945 | 1,172 | 1,358 | 1,581 | 1,606 | 1,794 | 2,016 | |
| Net income | $ 1,608 | $ 1,995 | $ 2,333 | $ 2,681 | $ 2,740 | $ 3,056 | $ 3,433 |
| EPS | $ 0.70 | $ 0.87 | $ 1.02 | $ 1.17 | $ 1.19 | $ 1.33 | |
| Dividends per share (for the whole year) | $ 0.09 | $ 0.11 | $ 0.13 | $ 0.17 | $ 0.20 | $ 0.21 | |
Shareholders' Equity Preferred stock ( 0 par value: 100 share authorized, none issued) Common stock ( \ .10 par value; 5,500 shares authorized. 2,285 and 2,293 issued and outstanding in 1997 and 1996, respectively) 228 229 Capital in excess of par value 547 545 Retained earnings 16,768 14,394 Foreign currency translation adjustment (400) (412) Total shareholders' equity 14,756 Total liabilities and shareholders' equity \ 39,604 \ 37,541
a. Calculate for X7 the ratios listed below. X6 numbers are provided for comparative purposes. Inventory turnover 4.96 Days inventory outstanding 73.56 Accounts receivable turnover 120.58 Days receivable outstanding 3.03 Payables turnover 12.39 Days payables outstanding 29.46 Length of operating cycle 76.58 Length of cash cycle 47.12 Current ratio 1.51 Quick ratio 0.12
b. Working capital management is an important consideration for many companies. Which component of Wal*Mart's working capital do you think it spends most time managing? That is, which component is likely to be the most important? Why? What has happened to this component from X6 to X7? (Essay)
4.8/5 (77)
(77) If a company increased its dividend payments what would happen to the following ratios, all other things being equal? Total Debt/Equity Times Interest Earned Financial Leverage Ratio A) Same Same Same B) Increase Same Decrease C) Same Decrease Decrease D) Increase Same Increase
(Multiple Choice)
5.0/5 (72)
(72) Liquidity is viewed as the company's ability to meet its short term and long term obligations.
(True/False)
4.8/5 (83)
(83) Minority shareholders' interest on the balance sheet represents a liability to the company and should always be included in debt when calculating the debt/equity ratio.
(True/False)
4.7/5 (75)
(75) If a company wishes to increase its current ratio, it could:
(Multiple Choice)
5.0/5 (77)
(77) If a company's current ratio increases from 1.2 to 1.4 from one year to the next, and its quick ratio decreases from 0.2 to 0.15 over the same time period, this indicates:
(Multiple Choice)
4.8/5 (83)
(83) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)