



 Chat with AI
Exam 14: Long-Term Liabilities: Bonds and Notes

Exam 1: Introduction to Accounting and Business190 Questions
Exam 2: Analyzing Transactions224 Questions
Exam 3: The Adjusting Process179 Questions
Exam 4: Completing the Accounting Cycle194 Questions
Exam 5: Accounting Systems160 Questions
Exam 6: Accounting for Merchandising Businesses215 Questions
Exam 7: Inventories165 Questions
Exam 8: Sarbanes-Oxley, Internal Control, and Cash176 Questions
Exam 9: Receivables140 Questions
Exam 10: Fixed Assets and Intangible Assets170 Questions
Exam 11: Current Liabilities and Payroll169 Questions
Exam 12: Accounting for Partnerships and Limited Liability Companies190 Questions
Exam 13: Corporations: Organization, Stock Transactions, and Dividends165 Questions
Exam 14: Long-Term Liabilities: Bonds and Notes185 Questions
Exam 15: Investments and Fair Value Accounting133 Questions
Exam 16: Statement of Cash Flows160 Questions
Exam 17: Financial Statement Analysis185 Questions
Exam 18: Managerial Accounting Concepts and Principles173 Questions
Exam 19: Job Order Costing173 Questions
Exam 20: Process Cost Systems177 Questions
Exam 21: Cost Behavior and Cost-Volume-Profit Analysis215 Questions
Exam 22: Budgeting188 Questions
Exam 23: Performance Evaluation Using Variances From Standard Costs161 Questions
Exam 24: Performance Evaluation for Decentralized Operations200 Questions
Exam 25: Differential Analysis and Product Pricing162 Questions
Exam 26: Capital Investment Analysis179 Questions
Select questions type


The effective-interest method of amortizing a bond discount or premium is the preferred method.
(True/False)
4.8/5  (79)
(79) On January 1, 2011, Zero Company obtained a $52,000, four-year, 6.5% installment note from Regional Bank. The note requires annual payments of $15,179, beginning on December 31, 2011. The December 31, 2013 carrying amount in the amortization table for this installment note will be equal to:
(Multiple Choice)
4.9/5 (85)
(85) The face value of a term bond is payable at a single specific date in the future.
(True/False)
4.9/5 (83)
(83) Two companies are financed as follows:
 Income tax is estimated at 40% of income.
Determine for each company the earnings per share of common stock, assuming that the income before bond interest and income taxes is $2,280,000 each.
Income tax is estimated at 40% of income.
Determine for each company the earnings per share of common stock, assuming that the income before bond interest and income taxes is $2,280,000 each. (Essay)
4.7/5 (72)
(72) On August 1, Clayton Co. issued $1,300,000 of 20-year, 9% bonds, dated August 1, for $1,225,000. Interest is payable semiannually on February 1 and August 1. Present the entries to record the following transactions for the current year:
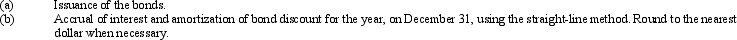
(Essay)
4.8/5 (80)
(80) If bonds are sold for a discount, the carrying value of the bonds is equal to the face value less the unamortized discount.
(True/False)
4.8/5 (73)
(73) There is a loss on redemption of bonds when bonds are redeemed above carrying value.
(True/False)
4.8/5 (82)
(82) When the bonds are sold for more than their face value, the carrying value of the bonds is equal to
(Multiple Choice)
4.8/5 (78)
(78) The present value of $5,000 to be received in 4 years at a market rate of interest of 6% compounded annually is $3,636.30.
(True/False)
4.9/5 (65)
(65) When a portion of a bond issue is redeemed, a related proportion of the unamortized premium or discount must be written off.
(True/False)
4.9/5 (81)
(81) If the market rate of interest is 8% and a corporation's bonds bear interest at 7%, the bonds will sell at a premium.
(True/False)
4.9/5 (83)
(83) On January 1, 2014, the Horton Corporation issued 10% bonds with a face value of $200,000. The bonds are sold for $192,000. The bonds pay interest semiannually on June 30 and December 31 and the maturity date is December 31, 2018. Horton records straight-line amortization of the bond discount. The bond interest expense for the year ended December 31, 2014, is
(Multiple Choice)
4.7/5 (86)
(86) Bonds Payable has a balance of $1,000,000 and Discount on Bonds Payable has a balance of $10,000. If the issuing corporation redeems the bonds at 97.5, what is the amount of gain or loss on redemption?
(Multiple Choice)
4.8/5 (87)
(87) The Victor Corporation issues 1,000, 10-year, 8%, $1,000 bonds dated January 1, 2011, at 96. The journal entry to record the issuance will show a
(Multiple Choice)
4.8/5 (75)
(75) The Designer Company issued 10-year bonds on January 1, 2011. The 6% bonds have a face value of $800,000 and pay interest every January 1 and July 1. The bonds were sold for $690,960 based on the market interest rate of 8%. Designer uses the effective-interest method to amortize bond discounts and premiums. On July 1, 2011, Designer should record interest expense (round to the nearest dollar) of
(Multiple Choice)
4.8/5 (76)
(76) Jenson Co., is considering the following alternative plans for financing their company:
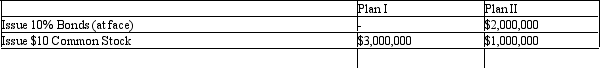 Income tax is estimated at 40% of income.
Determine the earnings per share of common stock under the two alternative financing plans, assuming income before bond interest and income tax is $1,000,000.
Income tax is estimated at 40% of income.
Determine the earnings per share of common stock under the two alternative financing plans, assuming income before bond interest and income tax is $1,000,000. (Essay)
4.8/5 (79)
(79) Calculate the total amount of interest expense over the life of the bonds for the following independent situations.
a) $100,000 face value, 10%, 10-year bonds issued at 101.
b) $240,000 face value, 5%, 5-year bonds issued at 100.
c) $300,000 face value, 9%, 6-year bonds issued at 98.
(Essay)
4.8/5 (69)
(69) The balance in Premium on Bonds Payable should be reported as a deduction from Bonds Payable on the balance sheet.
(True/False)
4.9/5 (72)
(72) Both callable and non-callable bonds can be purchased by the issuing corporation in the open market.
(True/False)
4.8/5 (69)
(69) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)