



 Chat with AI
Exam 13: Marketable Securities and Derivatives

Exam 1: Introduction to Business Activities and Overview of Financial Statements and the Reporting Process139 Questions
Exam 2: The Basics of Record Keeping and Financial Statement Preparation: Balance Sheet115 Questions
Exam 3: The Basics of Record Keeping and Financial Statement Preparation: Income Statement129 Questions
Exam 4: Balance Sheet: Presenting and Analyzing Resources and Financing120 Questions
Exam 5: Income Statement: Reporting Results of Operating Activities109 Questions
Exam 6: Statement of Cash Flows140 Questions
Exam 7: Introduction to Financial Statement Analysis166 Questions
Exam 8: Revenue Recognition, Receivables, and Advances From Customers138 Questions
Exam 9: Working Capital167 Questions
Exam 10: Long-Lived Tangible and Intangible Assets182 Questions
Exam 11: Notes, Bonds, and Leases139 Questions
Exam 12: Liabilities: Off-Balance Sheet Financing, Retirement Benefits, and Income Taxes117 Questions
Exam 13: Marketable Securities and Derivatives144 Questions
Exam 14: Intercorporate Investments in Common Stock103 Questions
Exam 15: Shareholders Equity: Capital Contributions and Distributions199 Questions
Exam 16: Statement of Cash Flows: Another Look146 Questions
Exam 17: Synthesis and Extensions246 Questions
Select questions type


Martin Company acquired $500,000 face value of the outstanding bonds of Tory Company on January 1, 2012.The bonds pay interest semiannually on June 30 and December 31 at an annual rate of 7% and mature on December 31, 2014.The bonds were priced on the market on January 1, 2012, to yield 6% compounded semiannually.Martin Company classifies these bonds as held to maturity.
a.Compute the amount that Martin Company paid for these bonds, excluding commissions and taxes.
b.Prepare an amortization table for these bonds.
c.Give the journal entries that Martin Company would make to account for these bonds during 2012.
d.Give the journal entries that Martin Company would make to account for these bonds on December 31, 2014.
(Essay)
4.8/5  (84)
(84) Gains and losses on derivatives not designated as hedges of a specific risk, gains and losses on fair value hedges, and the ineffective portion of cash flow hedges affect net income simultaneously with changes in fair value.
(True/False)
4.9/5 (69)
(69) ValleyView Company ValleyView Company acquires common stock of Kansas Enterprises for $400,000 on November 1, 2013, and designates this investment as available-for-sale.The fair value of these shares is $435,000 on December 31, 2013.ValleyView sells these shares on August 15, 2014, for $480,000.
(Refer to ValleyView.) The total income from the purchase and sale of these securities is _____ reported _____
(Multiple Choice)
4.9/5 (85)
(85) A derivative may have zero initial cost, but potentially large positive or negative fair values later.
(True/False)
4.8/5 (82)
(82) Marco Insurance Marco Insurance acquired shares of Penny Systems' common stock on December 28, 2013, for $400,000 and classified them as trading securities.The fair value of these securities on December 31, 2013, was $402,000.Marco Insurance sold these shares on January 3, 2014, for $405,000.
(Refer to the Marco Insurance) The journal entries to record acquisition of trading securities on December 28, 2013.
(Multiple Choice)
5.0/5 (86)
(86) Lightner Company decides that an available-for-sale security is impaired as of December 31, 2013 and has an unrealized loss of $5,000.The journal entry to record an impairment loss on securities available-for-sale would be:
(Multiple Choice)
4.8/5 (90)
(90) U.S.GAAP requires firms to disclose which of the following information with respect to derivatives?
(Multiple Choice)
4.8/5 (84)
(84) According to U.S.GAAP,firms holding debt and equity securities for short-term profit potential
(Multiple Choice)
4.8/5 (76)
(76) The provisions of U.S.GAAP require firms to classify marketable securities into the following categories except
(Multiple Choice)
4.8/5 (74)
(74) In Year 1, the firm purchased a portfolio of marketable securities for $1,000, which it holds as current assets.At the end of Year 1, the portfolio had a market value of $800.During Year 2, the firm sold some of the securities for $120 which had originally cost $100, but which had a market value of $90 at the end of Year 1.At the end of Year 2, the remaining securities had a market value of $1,150.
Required:
a. Assume the firm treats its holdings as available-for-sale.
1. Record the entry made at the end of Year 1.
2. Record the entries made during Year 2 and at the end of Year 2.
b. Assume the firm treats its holdings as trading securities.
1. Record the entry made at the end of Year 1.
2. Record the entries made during Year 2 and at the end of Year 2.
(Essay)
4.9/5 (71)
(71) Using the amortization procedure, the holder of the debt securities (the investor) records interest revenue each period at an amount equal to the _____ at the start of the period multiplied by the _____ applicable to that debt on the day the firm acquired the debt.The bonds are classified as held to maturity.
(Multiple Choice)
5.0/5 (85)
(85) U.S.GAAP requires firms holding minority, passive investments in debt and equity securities as securities available-for-sale that the firm intends to sell within one year to report them as
(Multiple Choice)
4.8/5 (65)
(65) Describe the fair value option applied to marketable securities and derivatives.
(Essay)
4.8/5 (76)
(76) Kerry Corporation acquires the publicly traded debt of Jett Corporation on December 31, Year 1 as a temporary investment of excess cash.The securities mature in 4 years.How will the securities be recorded on Kerry's December 31, Year 1 financial statement?
(Multiple Choice)
4.9/5 (75)
(75) U.S.GAAP and IFRS require firms to disclose the fair value of financial instruments in a note to the financial statements.What should such a note include?
(Essay)
4.9/5 (74)
(74) Measurement of trading securities at _____ reflects income when it occurs in the form of a change in _____, not when the investor realizes a gain or loss _____.
(Multiple Choice)
4.9/5 (83)
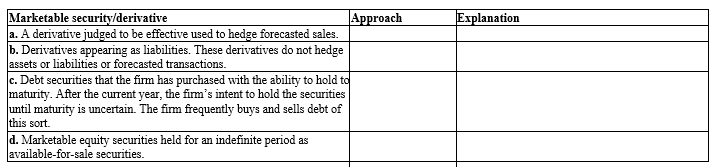
(83) Complete the following chart for items a through d, describing the accounting treatment
using the number by one of the following four approaches listed as follows.
(Assume that the firm does not elect the fair value option):
APPROACHES
(1) Measured at fair value with changes recognized in net income.
(2) Measured at amortized cost.
(3) Measured at fair value with changes recognized initially in other comprehensive income.
(4) Measurement depends on whether firm uses hedge accounting.
In the third column of the chart, present your explanation regarding this approach.
(Essay)
4.8/5 (89)
(89) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)