



 Chat with AI
Exam 13: Marketable Securities and Derivatives

Exam 1: Introduction to Business Activities and Overview of Financial Statements and the Reporting Process139 Questions
Exam 2: The Basics of Record Keeping and Financial Statement Preparation: Balance Sheet115 Questions
Exam 3: The Basics of Record Keeping and Financial Statement Preparation: Income Statement129 Questions
Exam 4: Balance Sheet: Presenting and Analyzing Resources and Financing120 Questions
Exam 5: Income Statement: Reporting Results of Operating Activities109 Questions
Exam 6: Statement of Cash Flows140 Questions
Exam 7: Introduction to Financial Statement Analysis166 Questions
Exam 8: Revenue Recognition, Receivables, and Advances From Customers138 Questions
Exam 9: Working Capital167 Questions
Exam 10: Long-Lived Tangible and Intangible Assets182 Questions
Exam 11: Notes, Bonds, and Leases139 Questions
Exam 12: Liabilities: Off-Balance Sheet Financing, Retirement Benefits, and Income Taxes117 Questions
Exam 13: Marketable Securities and Derivatives144 Questions
Exam 14: Intercorporate Investments in Common Stock103 Questions
Exam 15: Shareholders Equity: Capital Contributions and Distributions199 Questions
Exam 16: Statement of Cash Flows: Another Look146 Questions
Exam 17: Synthesis and Extensions246 Questions
Select questions type


In Year 1, the firm purchased a portfolio of marketable securities for $1,000, which it holds as current assets.At the end of Year 1, the portfolio had a market value of $700.During Year 2, the firm sold some of the securities for $160 which had originally cost $100, but which had a market value of $80 at the end of Year 1.At the end of Year 2, the remaining securities had a market value of $850.
Required:
a. Assume the firm treats its holdings as available-for-sale.
1. Record the entry made at the end of Year 1.
2. Record the entries made during Year 2 and at the end of Year 2.
b. Assume the firm treats its holdings as trading securities.
1. Record the entry made at the end of Year 1.
2. Record the entries made during Year 2 and at the end of Year 2.
(Essay)
5.0/5  (76)
(76) Cummings Industries places a firm order for the equipment on June 30, 2013.It simultaneously signs a forward currency contract for £20,000.The forward rate on June 30, 2013, for settlement on June 30, 2014, is $1.64 per £1.Cummings designates the forward contract as a fair value hedge of the firm commitment.
REQUIRED:
a. U.S. GAAP and IFRS guidance does not require Cummings to record either the purchase commitment or the forward contract on the balance sheet as a liability or an asset on June 30, 2013. What is the logic for this accounting?
b. On December 31, 2013, the forward exchange rate for settlement on June 30, 2014, is $1.73 per £1. Give the journal entries to record the change in the fair value of the purchase commitment and the change in the fair value of the forward contract for 2013. Assume an 8% interest rate for discounting cash flows to their present values on December 31, 2013.
c. Give the journal entries on June 30, 2014, to record the change in the present value of the purchase commitment and the forward contract for the passage of time.
d. On June 30, 2014, the spot exchange rate is $1.75 per £1. Give the journal entries to record the change in the fair value of the purchase commitment and the change in the fair value of the forward contract due to changes in the exchange rate during the first six months of 2014.
e. Give the journal entry on June 30, 2014, to purchase £20,000 with U.S. dollars and acquire the equipment.
f. Give the journal entry on June 30, 2014, to settle the forward contract.
g. How would the entries in parts (b) through (f) differ if Cummings had chosen to designate the forward currency contract as a cash flow hedge of a forecasted transaction instead of a fair value hedge of a firm commitment?
h. What type of scenario would justify Cummings treating the forward currency contract as a fair value hedge? What type of scenario that would justify the firm treating the contract as a cash flow hedge?.
(Essay)
4.8/5 (79)
(79) Which of the following is a characteristic of a derivative?
(Multiple Choice)
4.8/5 (72)
(72) Which of the following is not true regarding investments in securities available-for-sale?
(Multiple Choice)
4.7/5 (80)
(80) Both U.S.GAAP and IFRS require that firms record derivatives at their fair values on the balance sheet date.
(True/False)
4.9/5 (79)
(79) To be classified as a current asset, marketable securities must be readily convertible into cash and
(Multiple Choice)
5.0/5 (86)
(86) Which of the following would most likely be classified as Marketable Securities in the Current Assets section of the balance sheet?
(Multiple Choice)
4.8/5 (79)
(79) U.S.GAAP and IFRS require firms to account for debt securities held-to-maturity that are deemed to be impaired.The investor recognizes (debits) _____ and reduces (credits) _____.
(Multiple Choice)
5.0/5 (87)
(87) Which of the following is a characteristic of a derivative?
(Multiple Choice)
4.9/5 (83)
(83) U.S.GAAP classifies securities that are neither debt securities held to maturity or trading securities as
(Multiple Choice)
4.8/5 (77)
(77) Firms initially record trading securities at fair value, excluding transactions costs (which firms expense as they incur them).
(True/False)
4.9/5 (81)
(81) The 2013 annual report of Travel Industries reports the following data about its marketable securities held available-for-sale.
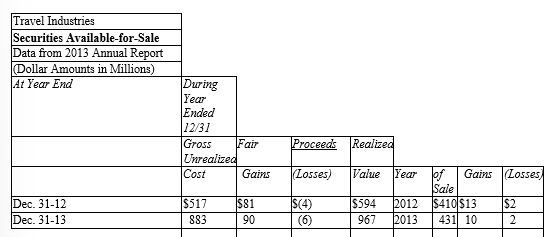 Required:
a. What was the cost of the securities available-for-sale that Travel Industries sold during the year 2013?
b. What was the cost of the securities available-for-sale that Travel Industries purchased during the year 2013?
c. What was Travel Industries' Other Comprehensive Income related to securities available-for-sale for 2013?
d. What were the total gains or losses, net, both realized and unrealized on Travel Industries' securities available-for-sale during the year 2013?
Required:
a. What was the cost of the securities available-for-sale that Travel Industries sold during the year 2013?
b. What was the cost of the securities available-for-sale that Travel Industries purchased during the year 2013?
c. What was Travel Industries' Other Comprehensive Income related to securities available-for-sale for 2013?
d. What were the total gains or losses, net, both realized and unrealized on Travel Industries' securities available-for-sale during the year 2013?
(Essay)
4.9/5 (68)
(68) Discuss the accounting for debt securities held to maturity and arguments against this approach.
(Essay)
4.8/5 (79)
(79) (CMA adapted, Jun 97 #12) Refer to the Manley Company example.Assuming that the above securities are properly classified as held-to-maturity securities under U.S.GAAP, the unrealized holding gain or loss as of May 31, Year 7, would
(Multiple Choice)
4.7/5 (75)
(75) The provisions of IFRS require firms to classify marketable securities into which of the following categories?
(Multiple Choice)
4.8/5 (76)
(76) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)