



 Chat with AI
Exam 6: Quality of Accounting Information and Adjustments to Reported Financial Statement Data

Exam 1: Overview of Financial Reporting, Financial Statement Analysis, and Valuation67 Questions
Exam 2: Asset and Liability Valuation and Income Measurement49 Questions
Exam 3: Income Flows Versus Cash Flows: Key Relationships in the Dynamics of a Business55 Questions
Exam 4: Profitability Analysis69 Questions
Exam 5: Risk Analysis63 Questions
Exam 6: Quality of Accounting Information and Adjustments to Reported Financial Statement Data52 Questions
Exam 7: Revenue Recognition and Related Expenses52 Questions
Exam 8: Liability Recognition and Related Expenses61 Questions
Exam 9: Intercorporate Entities55 Questions
Exam 10: Forecasting Financial Statements41 Questions
Exam 11: Risk-Adjusted Expected Rates of Return and the Dividends Valuation Approach30 Questions
Exam 12: Valuation: Cash-Flow-Based Approaches41 Questions
Exam 13: Valuation: Earnings-Based Approaches47 Questions
Exam 14: Valuation: Market-Based Approaches50 Questions
Select questions type


The date on which a firm commits itself to a formal plan to dispose of a segment is the

Free
(Multiple Choice)
4.9/5  (72)
(72) Correct Answer: Verified
B
Earnings are informative if they signal the portion of current period's due to a new product and the additional earnings in the future as a result of the ____________________ of this new earnings stream.
Free
(Short Answer)
4.8/5 (76)
(76) Correct Answer:Verified
Verifiedpersistence
The _________________________ is the date on which a firm commits itself to a formal plan to dispose of a business segment.
Free
(Short Answer)
4.7/5 (93)
(93) Correct Answer:Verified
Verifiedmeasurement date
Geyser Corp. reported net income of $390,000 in 2007. During 2007 Geyser reported a loss of $72,000 from a peripheral activity. The loss was included as part of income from continuing operations. Assuming that the loss is a one-time event and that Geyser has an effective tax rate of 35% calculate Geyser's adjusted net income. Show all of your calculations for credit.
In addition, discuss why analysts might make an adjustment of this type.
(Essay)
4.9/5 (79)
(79) During July 2007 Red Company decides to dispose of one of its subsidiaries which qualifies for accounting as a discontinued operation. At the July 2007 measurement date Red Company estimates that it will report net income of $200,000 dollars from the measurement date until the disposal date which is expected to be in April 2008. In addition, Red estimates that it will lose $300,000 on the sale of the segment. How much gain or loss on discontinued operations will Red report in its 2007 income statement (net of income taxes)?
(Multiple Choice)
4.7/5 (77)
(77) A ______________________________ is accounted for by spreading the effect of the prior year's misstatement over the current and future periods.
(Short Answer)
4.9/5 (84)
(84) Firm's choices and estimates within GAAP should be determined by
(Multiple Choice)
4.8/5 (84)
(84) Gains and losses that appear in Other Comprehensive Income are the result of value changes
(Multiple Choice)
4.9/5 (79)
(79) Which of the following is not a characteristic of an extraordinary item?
(Multiple Choice)
4.9/5 (85)
(85) When a long-lived asset loses its ability to generate future benefits GAAP requires firms to write down the assets to their fair values and recognize an ______________________________ in income from continuing operations.
(Short Answer)
4.7/5 (80)
(80) When evaluating the quality of accounting information the user should consider the reasonableness of the ____________________ made in applying GAAP.
(Short Answer)
4.7/5 (81)
(81) Many times a financial analyst may decide to make adjustments to the financial statements in order to make the statements more useful. Which of the following would not require an adjustment to the financial statement?
(Multiple Choice)
4.8/5 (86)
(86) A ____________________ of operations differs from a discontinuation of operations because the firm continues to operate in the business segment.
(Short Answer)
4.9/5 (72)
(72) When evaluating the quality of accounting information the user should consider the ____________________ of the measurements made.
(Short Answer)
5.0/5 (71)
(71) Which of the following is not considered a motive to manage earnings?
(Multiple Choice)
4.8/5 (74)
(74) Accounting information should provide a fair and complete representation about a number of a firm's characteristics, which of the following is not one of those characteristics?
(Multiple Choice)
4.7/5 (77)
(77) When a company makes a change in an estimate that it has used in its financial statements, it should account for the change by
(Multiple Choice)
4.8/5 (76)
(76) An _________________________ occurs when the carrying amount of a company's long-lived assets are not recoverable.
(Short Answer)
4.7/5 (79)
(79) Profit Corp. manufactures telecommunication equipment and has been profitable each year for the past ten years. During 2005 the company saw its core market decline sharply when a competitor introduced a significant new product technology. In response to the decline in business Profit Corp. announced a major restructuring of its operations. The restructuring plan which would be implemented in 2005 would involve the following changes (all of the charges are material):
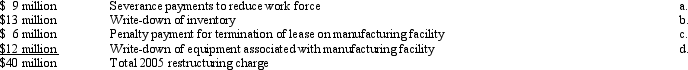 Profit Corp. has never previously restructured its operations and believes that it can return to profitability within two years based on its current research and development activity.
Required:
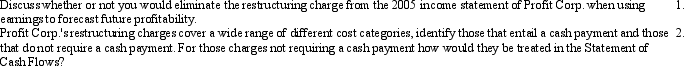
Profit Corp. has never previously restructured its operations and believes that it can return to profitability within two years based on its current research and development activity.
Required:
(Essay)
4.7/5 (66)
(66) Healy and Wahlen state that one type of earnings management occurs when managers use judgement in financial reporting to alter financial reports in order to mislead some stakeholder about the economic performance of the company. Earnings management is a consequence of a judgement by management which results in lower economic information content of the financial reports.
Discuss four reasons that discourage managers from practicing earnings management.
(Essay)
4.9/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)