



 Chat with AI
Exam 12: Intangibles

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


Burger Co. incurred the following costs during 2013 in the development and production of a new product: 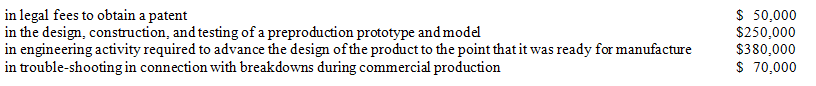 How much should be included in R&D expense for 2013?
 (Multiple Choice)
4.9/5  (88)
(88) Which of the following is not required to be disclosed in an entity's financial statements or accompanying footnotes?
(Multiple Choice)
4.8/5 (75)
(75) Costs for which of the following activities would not be included as part of research and development (R&D) costs?
(Multiple Choice)
4.9/5 (79)
(79) What characteristics do Intangible and tangible noncurrent assets have in common?
(Essay)
4.8/5 (80)
(80) Based on GAAP, most software development costs are likely to be
(Multiple Choice)
4.8/5 (87)
(87) The Jessie Company acquired a competitor company in January 2015. When Jessie's accountant recorded the purchase, she correctly recorded an amount for goodwill based on the expectation of the acquired company's earning a rate of return on its assets that was in excess of the industry's rate of return. In fact, the acquired company doubled the expected rate of return in 2015 and 2016. As a result of these increased earnings, in early 2017 the president of the Jessie Company asked the company's accountant to increase the amount recognized as goodwill.
Required:
a.Define the term "goodwill." In addition, discuss several possible factors that might contribute to a company having goodwill.
b.Discuss the accounting treatment under current GAAP for goodwill that is internally developed. Discuss the rationale for this treatment.
c.Discuss the accounting treatment under current GAAP for goodwill that is acquired through an external transaction.
d.Discuss the appropriateness of the president's request to increase the recorded amount of goodwill.
(Essay)
4.8/5 (91)
(91) In March of 2014, Marian Corp. applied for a trade name. Legal costs associated with the application were $25,000. At the time of filing the application, the company projected extra annual income to be generated through having the trade name to be $100,000. On Feb. 5, 2016, the company incurred $20,000 in an unsuccessful defense of the trade name.
Required:
a.What is the amount of income or expense associated with the trade name for the year 2014? For the year 2015? For the year 2016?
b.What is the accounting rationale for the amounts recorded in each year?
(Essay)
4.8/5 (71)
(71) During 2013, Debbie Company incurred $240,000 in legal fees in defending a patent with a carrying value of $4,500,000 against an infringement. Debbie's lawyers were not successful with the defense of the patent. The legal fees should be
(Multiple Choice)
4.8/5 (79)
(79) What factors should a company consider when estimating the useful life of an intangible asset?
(Essay)
4.8/5 (74)
(74) Certain activities are listed below.
a.Testing a new type of machine to evaluate its potential usefulness in production
b.Engineering follow-through in an early phase of commercial production
c.Totalcost of an R&D building-No alternative use
d.Salary of director of R&D
e.Current period depreciation on a building housing R&D activities (alternative future use)
f.General and administrative costs reasonably allocated to R&D projects
g.Patent acquired solely for use in a specific R&D project
Required:
List by letter the activities that would be considered in determining R&D costs.
(Essay)
5.0/5 (75)
(75) Which of the following statements concerning intangibles is true?
(Multiple Choice)
4.9/5 (84)
(84) Trademarks are considered to have an indefinite life and are therefore not subject to amortization.
(True/False)
4.8/5 (86)
(86) IFRS and GAAP differ in the application of the fair value concept for impairment tests applied to intangible assets.
Required:
Describe the fair value concept as it is applied for impairment tests in IFRS and GAAP, highlighting the differences.
(Essay)
4.9/5 (94)
(94) Costs for which of the following activities should not be included in research and development (R&D)?
(Multiple Choice)
4.9/5 (82)
(82) Identifiable intangible assets would include all of the following except
(Multiple Choice)
4.8/5 (80)
(80) At the date of purchase, materials, equipment, facilities, and intangibles purchased from others that have no alternative future uses in research and development or other activities should be
(Multiple Choice)
4.8/5 (84)
(84) On January 1, 2014, Sally, Inc. bought a patent for $100,000. There were ten years left of the patent's legal life. On July 1, 2016, the company successfully defended the patent in court at a cost of $30,000.
Required:
Compute the amount of patent amortization expense for 2016. Assume Sally calculates amortization to the nearest month and uses the straight-line method.
(Essay)
5.0/5 (73)
(73) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)