



 Chat with AI
Exam 19: Accounting for Postretirement Benefits

Exam 1: The Demand for and Supply of Financial Accounting Information89 Questions
Exam 2: Financial Reporting: Its Conceptual Framework87 Questions
Exam 3: Review of a Companys Accounting System146 Questions
Exam 4: The Balance Sheet and the Statement of Shareholders Equity112 Questions
Exam 5: The Income Statement and the Statement of Cash Flows151 Questions
Exam 6: Cash and Receivables149 Questions
Exam 7: Inventories: Cost Measurement and Flow Assumptions123 Questions
Exam 8: Inventories: Special Valuation Issues148 Questions
Exam 9: Current Liabilities and Contingencies128 Questions
Exam 10: Property, Plant, and Equipment: Acquisition and Subsequent Investments105 Questions
Exam 11: Depreciation, Depletion, Impairment, and Disposal143 Questions
Exam 12: Intangibles105 Questions
Exam 13: Investments and Long-Term Receivables140 Questions
Exam 14: Financing Liabilities: Bonds and Notes Payable171 Questions
Exam 15: Contributed Capital154 Questions
Exam 16: Retained Earnings and Earnings Per Share111 Questions
Exam 17: Advanced Issues in Revenue Recognition113 Questions
Exam 18: Accounting for Income Taxes108 Questions
Exam 19: Accounting for Postretirement Benefits98 Questions
Exam 20: Accounting for Leases149 Questions
Exam 21: The Statement of Cash Flows107 Questions
Exam 22: Accounting for Changes and Errors130 Questions
Exam 23: Time Value of Money Module121 Questions
Select questions type


If an employer were to account for a defined benefit pension plan on the cash basis, it would be a violation of the
(Multiple Choice)
4.9/5  (88)
(88) To improve usefulness of defined pension plans, GAAP requires disclosure of reconciliations of the beginning and ending amounts of the projected benefit obligation and fair value of the plan assets.
(True/False)
4.9/5 (78)
(78) Jennifer Corp's defined benefit pension plan had an amendment as of January 1, 2014, that retroactively included benefits of $1,500,000. The remaining service life of the employees impacted by this change is 10 years. Jennifer uses the straight-line method to amortize the prior service cost.
As of January 1, 2014, Jennifer had the following information related to its pension plan, including adjustments for the plan amendment:
 The actuary reported service cost of $600,000 in both 2014 and 2015. Annual payments to retirees totaled $90,000. The trustee of the plan assets reported the actual rate of return to be 11% in 2014.
Jennifer's annul year-end contribution to the plan equals the current year's service cost less actual return on plan assets plus interest growth of the projected benefit obligation and amortization of prior service costs and/or gains and losses as calculated for pension expense.
Required:
a.Compute Jennifer's 2014 contribution.
b.Compute Jennifer's 2014 pension expense.
c.Prepare the journal entry to record the pension expense and pension contribution.
d.Compute the December 31, 2014 balance in Pension Benefit Obligation.
e.Compute the December 31, 2014 balance in Plan Assets.
f.Prepare the adjusting journal entry to record the plan's adjustment to other comprehensive income at December 31, 2014.
g.Is Jennifer's plan overfunded or underfunded, and by how much, as of December 31, 2014?
The actuary reported service cost of $600,000 in both 2014 and 2015. Annual payments to retirees totaled $90,000. The trustee of the plan assets reported the actual rate of return to be 11% in 2014.
Jennifer's annul year-end contribution to the plan equals the current year's service cost less actual return on plan assets plus interest growth of the projected benefit obligation and amortization of prior service costs and/or gains and losses as calculated for pension expense.
Required:
a.Compute Jennifer's 2014 contribution.
b.Compute Jennifer's 2014 pension expense.
c.Prepare the journal entry to record the pension expense and pension contribution.
d.Compute the December 31, 2014 balance in Pension Benefit Obligation.
e.Compute the December 31, 2014 balance in Plan Assets.
f.Prepare the adjusting journal entry to record the plan's adjustment to other comprehensive income at December 31, 2014.
g.Is Jennifer's plan overfunded or underfunded, and by how much, as of December 31, 2014? (Essay)
4.8/5 (84)
(84) GAAP requires that a company record a loss and liability termination benefits when
(Multiple Choice)
4.8/5 (75)
(75) Disclosures for a defined benefit pension plan should include which of the following?
I.number of beneficiaries
II.reconciliation of the ending value of the projected benefit obligation
III.reconciliation of the ending fair value of the plan assets
IV.the composition of plan assets
V.the discount rate used
VI.expected long-term rate of return on plan assets
(Multiple Choice)
4.8/5 (83)
(83) Current GAAP requires that a company with a defined benefit pension plan disclose a reconciliation of the beginning and ending balances of the projected benefit obligation.
Required:
State the items that must be included in this disclosure.
(Essay)
5.0/5 (83)
(83) Which of the following statements is true regarding a defined contribution pension plan?
(Multiple Choice)
4.9/5 (81)
(81) The IASB amendment was to remove the smoothing of devices in pension accounting, which companies will have to recognize all changes in their projected benefit obligation and plan assets in the current period. These changes will be recorded in pension expense or other comprehensive income. With this change pension expense will have two components what are they and provide a brief explanation of both?
(Essay)
4.9/5 (72)
(72) GAAP for pension plans requires companies with defined benefit pension plans to
(Multiple Choice)
4.9/5 (77)
(77) Define the following:
expected postretirement benefit obligation (EPBO)
accumulated postretirement benefit obligation (APBO)
(Essay)
4.8/5 (66)
(66) Which of the following disclosures are required by GAAP for OPEBs?
(Multiple Choice)
4.9/5 (75)
(75) What four alternative methods for accounting for prior service cost were considered by accounting regulators?
(Essay)
4.9/5 (78)
(78) In 2014, the Ballaster Company decided to amend its defined benefit pension plan. The amendment gave 7 employees the right to receive future benefits based upon their prior service. Ballaster's actuary determined that the prior service cost for this amendment amounts to $550,000. One employee will retire in 1 year, 2 expect to retire in 2 years, 1 in three years, 1 in 4 years, and 2 in five years.
Required:
Using the straight line method compute the following:
1) the remaining service life (round to 5 decimals)
2) prepare an amortization schedule to amortize the prior service cost
(Essay)
4.9/5 (87)
(87) Marjorie, Inc.'s records contained the following data as of December 31, 2014, on its OPEB plan:  Required: Required:
a.Compute the OPEB expense for 2014.
b.Prepare the journal entry to record the 2014 OPEB expense.
Required: Required:
a.Compute the OPEB expense for 2014.
b.Prepare the journal entry to record the 2014 OPEB expense. (Essay)
4.9/5 (85)
(85) One type of post-retirement benefit other than pensions is healthcare benefits.
Required:
Discuss the major differences between postretirement healthcare benefits and pensions.
(Essay)
4.9/5 (71)
(71) The corridor is defined as 10% of the greater of the beginning of the year projected benefit obligation or the end of the year fair value of the plan.
(True/False)
4.9/5 (68)
(68) The following information is provided regarding a company's pension plan:
 Required:
a.Prepare the December 31 journal entry to record pension expense.
b.Explain the difference between "interest cost" and the "expected return on plan assets."
Required:
a.Prepare the December 31 journal entry to record pension expense.
b.Explain the difference between "interest cost" and the "expected return on plan assets." (Essay)
4.9/5 (80)
(80) Teresa Company had the following information related to its pension plan: 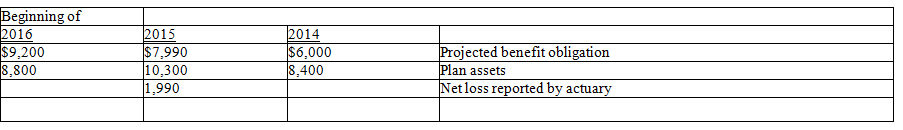 For simplicity, an average remaining service life fof 3 years is always used.
An additional net loss of $1990 was reported as of January 1, 2015 (see table). This amount has been included in the January 1, 2015. projected benefit obligation balance.
Required:
Compute the amount of loss that should be included in pension expense in:
a.2015
b.2016
For simplicity, an average remaining service life fof 3 years is always used.
An additional net loss of $1990 was reported as of January 1, 2015 (see table). This amount has been included in the January 1, 2015. projected benefit obligation balance.
Required:
Compute the amount of loss that should be included in pension expense in:
a.2015
b.2016
(Essay)
4.9/5 (85)
(85) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)