



 Chat with AI
Exam 2: Consolidation of Financial Information

Exam 1: The Equity Method of Accounting for Investments119 Questions
Exam 2: Consolidation of Financial Information118 Questions
Exam 3: Consolidations - Subsequent to the Date of Acquisition121 Questions
Exam 4: Consolidated Financial Statements and Outside Ownership116 Questions
Exam 5: Consolidated Financial Statements - Intercompany Asset Transactions127 Questions
Exam 6: Intercompany Debt, Consolidated Statement of Cash Flows, and Other Issues114 Questions
Exam 7: Consolidated Financial Statements - Ownership Patterns and Income Taxes117 Questions
Exam 8: Segment and Interim Reporting113 Questions
Exam 9: Foreign Currency Transactions and Hedging Foreign Exchange Risk93 Questions
Exam 10: Translation of Foreign Currency Financial Statements97 Questions
Exam 11: Worldwide Accounting Diversity and International Accounting Standards60 Questions
Exam 12: Financial Reporting and the Securities and Exchange Commission76 Questions
Exam 13: Accounting for Legal Reorganizations and Liquidations83 Questions
Exam 14: Partnerships: Formation and Operation88 Questions
Exam 15: Partnerships: Termination and Liquidation70 Questions
Exam 16: Accounting for State and Local Governments78 Questions
Exam 17: Accounting for State and Local Governments51 Questions
Exam 18: Accounting for Not-For-Profit Organizations64 Questions
Exam 19: Accounting for Estates and Trusts80 Questions
Select questions type


For each of the following situations, select the best letter answer to reflect the effect of the numbered item on the acquirer's accounting entry at the date of combination when separate incorporation will be maintained. Items (4) and (6) require two selections.
(A) Increase Investment account.
(B) Decrease Investment account.
(C) Increase Liabilities.
(D) Increase Common stock.
(E) Decrease common stock.
(F) Increase Additional paid-in capital.
(G) Decrease Additional paid-in capital.
(H) Increase Retained earnings
(I) Decrease Retained earnings
_____1. Direct costs.
_____2. Indirect costs.
_____3. Stock issue costs.
_____4. Contingent consideration.
_____5. Bargain purchase.
_____6. In-process research and development acquired.
(Short Answer)
4.7/5  (70)
(70) Bullen Inc. acquired 100% of the voting common stock of Vicker Inc. on January 1, 20X1. The book value and fair value of Vicker's accounts on that date (prior to creating the combination) follow, along with the book value of Bullen's accounts:  Assume that Bullen issued 12,000 shares of common stock with a $5 par value and a $42 fair value for all of the outstanding stock of Vicker. What is the consolidated balance for Land as a result of this acquisition transaction?
 (Multiple Choice)
4.8/5 (86)
(86) The financial statements for Jode Inc. and Lakely Corp., just prior to their combination, for the year ending December 31, 2010, follow. Lakely's buildings were undervalued on its financial records by $60,000. 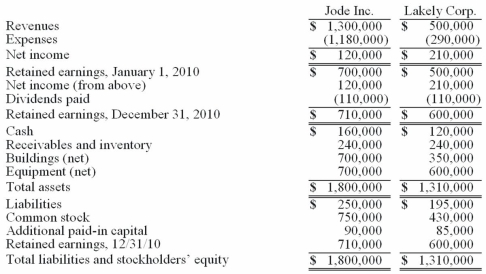 On December 31, 2010, Jode issued 54,000 new shares of its $10 par value stock in exchange for all the outstanding shares of Lakely. Jode's shares had a fair value on that date of $35 per share. Jode paid $34,000 to an investment bank for assisting in the arrangements. Jode also paid $24,000 in stock issuance costs to effect the acquisition of Lakely. Lakely will retain its incorporation.
Determine consolidated Additional paid-in Capital at December 31, 2010.
On December 31, 2010, Jode issued 54,000 new shares of its $10 par value stock in exchange for all the outstanding shares of Lakely. Jode's shares had a fair value on that date of $35 per share. Jode paid $34,000 to an investment bank for assisting in the arrangements. Jode also paid $24,000 in stock issuance costs to effect the acquisition of Lakely. Lakely will retain its incorporation.
Determine consolidated Additional paid-in Capital at December 31, 2010. (Essay)
4.8/5 (87)
(87) The financial statements for Goodwin, Inc., and Corr Company for the year ended December 31, 20X1, prior to Goodwin's acquisition business combination transaction regarding Corr, follow (in thousands):  On December 31, 20X1, Goodwin issued $600 in debt and 30 shares of its $10 par value common stock to the owners of Corr to acquire all of the outstanding shares of that company. Goodwin shares had a fair value of $40 per share. Goodwin paid $25 to a broker for arranging the transaction. Goodwin paid $35 in stock issuance costs. Corr's equipment was actually worth $1,400 but its buildings were only valued at $560.
Compute the consolidated revenues for 20X1.
On December 31, 20X1, Goodwin issued $600 in debt and 30 shares of its $10 par value common stock to the owners of Corr to acquire all of the outstanding shares of that company. Goodwin shares had a fair value of $40 per share. Goodwin paid $25 to a broker for arranging the transaction. Goodwin paid $35 in stock issuance costs. Corr's equipment was actually worth $1,400 but its buildings were only valued at $560.
Compute the consolidated revenues for 20X1. (Multiple Choice)
4.8/5 (70)
(70) The financial statements for Jode Inc. and Lakely Corp., just prior to their combination, for the year ending December 31, 2010, follow. Lakely's buildings were undervalued on its financial records by $60,000. 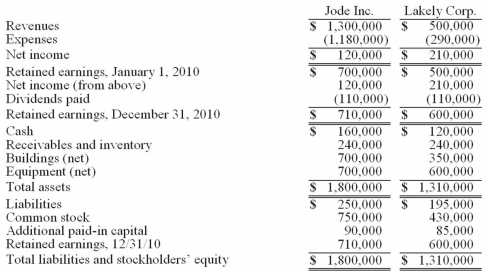 On December 31, 2010, Jode issued 54,000 new shares of its $10 par value stock in exchange for all the outstanding shares of Lakely. Jode's shares had a fair value on that date of $35 per share. Jode paid $34,000 to an investment bank for assisting in the arrangements. Jode also paid $24,000 in stock issuance costs to effect the acquisition of Lakely. Lakely will retain its incorporation.
Required:
Determine consolidated net income for the year ended December 31, 2010.
On December 31, 2010, Jode issued 54,000 new shares of its $10 par value stock in exchange for all the outstanding shares of Lakely. Jode's shares had a fair value on that date of $35 per share. Jode paid $34,000 to an investment bank for assisting in the arrangements. Jode also paid $24,000 in stock issuance costs to effect the acquisition of Lakely. Lakely will retain its incorporation.
Required:
Determine consolidated net income for the year ended December 31, 2010. (Essay)
4.8/5 (94)
(94) On January 1, 20X1, the Moody Company entered into a transaction for 100% of the outstanding common stock of Osorio Company. To acquire these shares, Moody issued $400 in long-term liabilities and 40 shares of common stock having a par value of $1 per share but a fair value of $10 per share. Moody paid $20 to lawyers, accountants, and brokers for assistance in bringing about this acquisition. Another $15 was paid in connection with stock issuance costs. Prior to these transactions, the balance sheets for the two companies were as follows:  Note: Parentheses indicate a credit balance. In Moody's appraisal of Osorio, three assets were deemed to be undervalued on the subsidiary's books: Inventory by $10, Land by $40, and Buildings by $60.
Compute the amount of consolidated land at date of acquisition.
Note: Parentheses indicate a credit balance. In Moody's appraisal of Osorio, three assets were deemed to be undervalued on the subsidiary's books: Inventory by $10, Land by $40, and Buildings by $60.
Compute the amount of consolidated land at date of acquisition. (Multiple Choice)
4.9/5 (69)
(69) Salem Co. had the following account balances as of December 1, 2010: 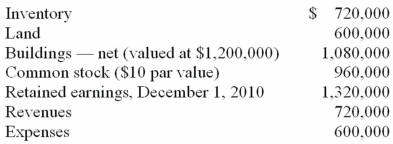 Bellington Inc. transferred $1.7 million in cash and 12,000 shares of its newly issued $30 par value common stock (valued at $90 per share) to acquire all of Salem's outstanding common stock.
Assume that Bellington paid cash of $2.8 million. No stock is issued. An additional $50,000 is paid in direct combination costs.
Required:
For Goodwill, determine what balance would be included in a December 1, 2010 consolidation.
Bellington Inc. transferred $1.7 million in cash and 12,000 shares of its newly issued $30 par value common stock (valued at $90 per share) to acquire all of Salem's outstanding common stock.
Assume that Bellington paid cash of $2.8 million. No stock is issued. An additional $50,000 is paid in direct combination costs.
Required:
For Goodwill, determine what balance would be included in a December 1, 2010 consolidation. (Essay)
4.9/5 (81)
(81) Fine Co. issued its common stock in exchange for the common stock of Dandy Corp. in an acquisition. At the date of the combination, Fine had land with a book value of $480,000 and a fair value of $620,000. Dandy had land with a book value of $170,000 and a fair value of $190,000.
Required:
What was the consolidated balance for Land in a consolidated balance sheet prepared at the date of the acquisition combination?
(Essay)
4.7/5 (82)
(82) The financial balances for the Atwood Company and the Franz Company as of December 31, 20X1, are presented below. Also included are the fair values for Franz Company's net assets.  Note: Parenthesis indicate a credit balance Assume an acquisition business combination took place at December 31, 20X1. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid.
Compute consolidated cash at the completion of the acquisition.
Note: Parenthesis indicate a credit balance Assume an acquisition business combination took place at December 31, 20X1. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid.
Compute consolidated cash at the completion of the acquisition. (Multiple Choice)
4.8/5 (75)
(75) The financial balances for the Atwood Company and the Franz Company as of December 31, 20X1, are presented below. Also included are the fair values for Franz Company's net assets.  Note: Parenthesis indicate a credit balance Assume an acquisition business combination took place at December 31, 20X1. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid.
Compute consolidated goodwill at the date of the acquisition.
Note: Parenthesis indicate a credit balance Assume an acquisition business combination took place at December 31, 20X1. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid.
Compute consolidated goodwill at the date of the acquisition. (Multiple Choice)
4.9/5 (86)
(86) On January 1, 20X1, the Moody Company entered into a transaction for 100% of the outstanding common stock of Osorio Company. To acquire these shares, Moody issued $400 in long-term liabilities and 40 shares of common stock having a par value of $1 per share but a fair value of $10 per share. Moody paid $20 to lawyers, accountants, and brokers for assistance in bringing about this acquisition. Another $15 was paid in connection with stock issuance costs. Prior to these transactions, the balance sheets for the two companies were as follows:  Note: Parentheses indicate a credit balance. In Moody's appraisal of Osorio, three assets were deemed to be undervalued on the subsidiary's books: Inventory by $10, Land by $40, and Buildings by $60.
What amount was recorded as the investment in Osorio?
Note: Parentheses indicate a credit balance. In Moody's appraisal of Osorio, three assets were deemed to be undervalued on the subsidiary's books: Inventory by $10, Land by $40, and Buildings by $60.
What amount was recorded as the investment in Osorio? (Multiple Choice)
4.9/5 (81)
(81) The financial balances for the Atwood Company and the Franz Company as of December 31, 20X1, are presented below. Also included are the fair values for Franz Company's net assets.  Note: Parenthesis indicate a credit balance Assume an acquisition business combination took place at December 31, 20X1. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid.
Compute consolidated equipment (net) at the date of the acquisition.
Note: Parenthesis indicate a credit balance Assume an acquisition business combination took place at December 31, 20X1. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid.
Compute consolidated equipment (net) at the date of the acquisition. (Multiple Choice)
4.8/5 (77)
(77) Flynn acquires 100 percent of the outstanding voting shares of Macek Company on January 1, 20X1. To obtain these shares, Flynn pays $400 cash (in thousands) and issues 10,000 shares of $20 par value common stock on this date. Flynn's stock had a fair value of $36 per share on that date. Flynn also pays $15 (in thousands) to a local investment firm for arranging the acquisition. An additional $10 (in thousands) was paid by Flynn in stock issuance costs. The book values for both Flynn and Macek as of January 1, 20X1 follow. The fair value of each of Flynn and Macek accounts is also included. In addition, Macek holds a fully amortized trademark that still retains a $40 (in thousands) value. The figures below are in thousands. Any related question also is in thousands. 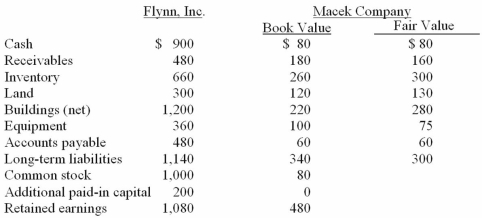 What amount will be reported for consolidated common stock?
 (Multiple Choice)
4.8/5 (82)
(82) Prior to being united in a business combination, Botkins Inc. and Volkerson Corp. had the following stockholders' equity figures:  Botkins issued 56,000 new shares of its common stock valued at $3.25 per share for all of the outstanding stock of Volkerson. Assume that Botkins acquired Volkerson on January 1, 2010. Immediately afterwards, what is consolidated Common Stock?
 (Multiple Choice)
4.8/5 (66)
(66) The financial statements for Goodwin, Inc., and Corr Company for the year ended December 31, 20X1, prior to Goodwin's acquisition business combination transaction regarding Corr, follow (in thousands):  On December 31, 20X1, Goodwin issued $600 in debt and 30 shares of its $10 par value common stock to the owners of Corr to acquire all of the outstanding shares of that company. Goodwin shares had a fair value of $40 per share. Goodwin paid $25 to a broker for arranging the transaction. Goodwin paid $35 in stock issuance costs. Corr's equipment was actually worth $1,400 but its buildings were only valued at $560.
Compute the goodwill arising from this acquisition at December 31, 20X1.
On December 31, 20X1, Goodwin issued $600 in debt and 30 shares of its $10 par value common stock to the owners of Corr to acquire all of the outstanding shares of that company. Goodwin shares had a fair value of $40 per share. Goodwin paid $25 to a broker for arranging the transaction. Goodwin paid $35 in stock issuance costs. Corr's equipment was actually worth $1,400 but its buildings were only valued at $560.
Compute the goodwill arising from this acquisition at December 31, 20X1. (Multiple Choice)
4.7/5 (85)
(85) Carnes has the following account balances as of May 1, 2010 before an acquisition transaction takes place.  The fair value of Carnes' Land and Buildings are $650,000 and $550,000, respectively. On May 1, 2010, Riley Company issues 30,000 shares of its $10 par value ($25 fair value) common stock in exchange for all of the shares of Carnes' common stock. Riley paid $10,000 for costs to issue the new shares of stock. Before the acquisition, Riley has $700,000 in its common stock account and $300,000 in its additional paid-in capital account. What will be the consolidated additional paid-in capital as a result of this acquisition?
 (Multiple Choice)
4.8/5 (70)
(70) Presented below are the financial balances for the Atwood Company and the Franz Company as of December 31, 2010, immediately before Atwood acquired Franz. Also included are the fair values for Franz Company's net assets at that date.  Note: Parenthesis indicate a credit balance Assume a business combination took place at December 31, 2010. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid to effect this acquisition transaction. To settle a difference of opinion regarding Franz's fair value, Atwood promises to pay an additional $5.2 (in thousands) to the former owners if Franz's earnings exceed a certain sum during the next year. Given the probability of the required contingency payment and utilizing a 4% discount rate, the expected present value of the contingency is $5 (in thousands).
Compute consolidated retained earnings as a result of this acquisition.
Note: Parenthesis indicate a credit balance Assume a business combination took place at December 31, 2010. Atwood issued 50 shares of its common stock with a fair value of $35 per share for all of the outstanding common shares of Franz. Stock issuance costs of $15 (in thousands) and direct costs of $10 (in thousands) were paid to effect this acquisition transaction. To settle a difference of opinion regarding Franz's fair value, Atwood promises to pay an additional $5.2 (in thousands) to the former owners if Franz's earnings exceed a certain sum during the next year. Given the probability of the required contingency payment and utilizing a 4% discount rate, the expected present value of the contingency is $5 (in thousands).
Compute consolidated retained earnings as a result of this acquisition. (Multiple Choice)
4.9/5 (78)
(78) The financial statements for Goodwin, Inc., and Corr Company for the year ended December 31, 20X1, prior to Goodwin's acquisition business combination transaction regarding Corr, follow (in thousands):  On December 31, 20X1, Goodwin issued $600 in debt and 30 shares of its $10 par value common stock to the owners of Corr to acquire all of the outstanding shares of that company. Goodwin shares had a fair value of $40 per share. Goodwin paid $25 to a broker for arranging the transaction. Goodwin paid $35 in stock issuance costs. Corr's equipment was actually worth $1,400 but its buildings were only valued at $560.
Compute the consolidated receivables and inventory for 20X1.
On December 31, 20X1, Goodwin issued $600 in debt and 30 shares of its $10 par value common stock to the owners of Corr to acquire all of the outstanding shares of that company. Goodwin shares had a fair value of $40 per share. Goodwin paid $25 to a broker for arranging the transaction. Goodwin paid $35 in stock issuance costs. Corr's equipment was actually worth $1,400 but its buildings were only valued at $560.
Compute the consolidated receivables and inventory for 20X1. (Multiple Choice)
5.0/5 (73)
(73) Describe the accounting for direct costs, indirect costs, and issuance costs under the acquisition method of accounting for a business combination.
(Essay)
4.9/5 (92)
(92) On January 1, 20X1, the Moody Company entered into a transaction for 100% of the outstanding common stock of Osorio Company. To acquire these shares, Moody issued $400 in long-term liabilities and 40 shares of common stock having a par value of $1 per share but a fair value of $10 per share. Moody paid $20 to lawyers, accountants, and brokers for assistance in bringing about this acquisition. Another $15 was paid in connection with stock issuance costs. Prior to these transactions, the balance sheets for the two companies were as follows:  Note: Parentheses indicate a credit balance. In Moody's appraisal of Osorio, three assets were deemed to be undervalued on the subsidiary's books: Inventory by $10, Land by $40, and Buildings by $60.
What amount was recorded as goodwill arising from this acquisition?
Note: Parentheses indicate a credit balance. In Moody's appraisal of Osorio, three assets were deemed to be undervalued on the subsidiary's books: Inventory by $10, Land by $40, and Buildings by $60.
What amount was recorded as goodwill arising from this acquisition? (Multiple Choice)
4.7/5 (68)
(68) 
Filters
- Essay(0)
- Multiple Choice(0)
- Short Answer(0)
- True False(0)
- Matching(0)